
Azenta (AZTA) Draws Attention As Automation Story Meets A Pricey Valuation
Azenta (AZTA) has caught investors' attention after a recent price move, with the stock closing at US$39.35 and posting mixed short term returns over the past week and month.
Those mixed daily moves sit against a much stronger backdrop, with Azenta posting a 30 day share price return of 25.6% and a 90 day gain of 60.55%. The 1 year total shareholder return of 28.05% contrasts with weaker 3 and 5 year total shareholder returns, which indicates that momentum has recently picked up even as longer term holders are still working through earlier declines.
Scan beyond Azenta and explore other potential momentum stories by checking out the hand picked 19 high quality undiscovered gems that currently have strong fundamentals but limited market attention.
Azenta has a specialised life sciences business and a share price that has just sprinted ahead. The real tension now is whether that quality is already fully reflected in the valuation.
Most Popular Narrative: 12% Overvalued
Azenta closed at $39.35 compared with a narrative fair value of $35.25, so the current price sits ahead of that framework while still leaning on future profitability and margin repair to justify the gap.
The ongoing trend of life sciences digitization and automation is reflected in Azenta's improved operational execution and introduction of more automated solutions. These efficiency gains, alongside investments in R&D and product management, are associated with significant gross margin and EBITDA margin expansion, and point to potential net margin improvements with scale.
See why 3 investors see Azenta as 12% overvalued.
Result: Fair Value of $35.25 (OVERVALUED)
Still, Azenta’s narrative meets some friction, with delayed orders in higher margin equipment and softer gene synthesis demand, both capable of pressuring revenue and profitability.
Find out about the key risks to this Azenta narrative.
Another View on Azenta’s Valuation
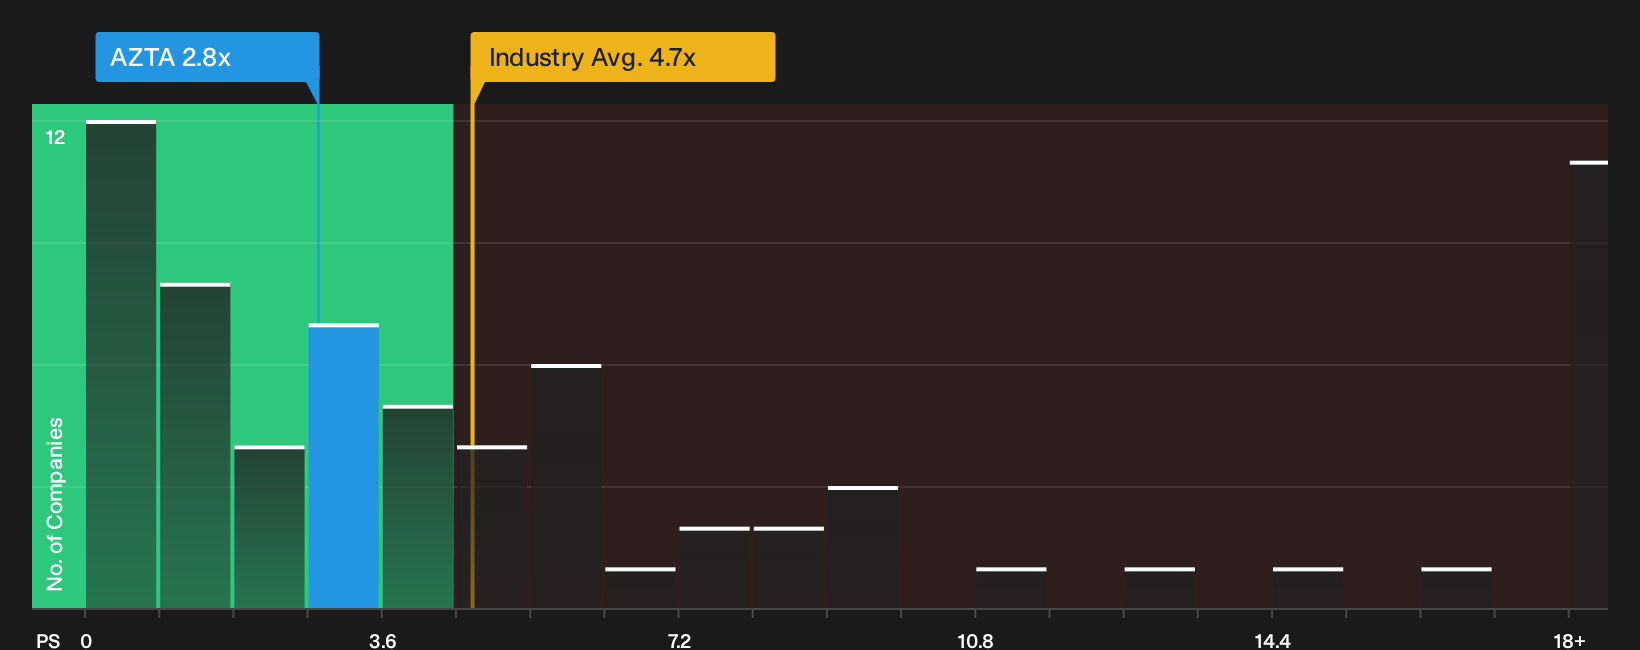
The first narrative has Azenta overvalued at $39.35 compared with a $35.25 fair value anchored on earnings forecasts. Yet the P/S ratio tells a different story. At 2.8x, it sits well below the US Life Sciences industry at 4.7x and the peer group at 16.3x, and even below an estimated fair ratio of 3x. That gap suggests investors are paying less per dollar of current sales than many similar businesses, which raises the question of whether the risk now lies more in future execution than in today’s sticker price.
To see how those sales based signals line up with earnings expectations and market sentiment, review the fuller valuation breakdown for Azenta through See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Azenta is mixed on price but quietly upbeat on fundamentals, which means the next move is on you. Act while the data is fresh, compare the narrative to the numbers, and pressure test your own thesis using the 2 key rewards.
Looking for more investment ideas beyond Azenta?
If Azenta has sharpened your focus, do not stop here. Use the Simply Wall Street Screener to surface fresh opportunities that fit your checklist.
- Target resilient compounders by scanning companies with stronger cash generation and sensible valuations through the 27 high quality undervalued stocks.
- Prioritise capital preservation and steadier rides by filtering for businesses with healthier finances using the 31 resilient stocks with low risk scores.
- Hunt for underfollowed opportunities by checking the list of solid balance sheet and fundamentals (25 results) that rarely make headlines but still line up with robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com