
Why Wynn Resorts Fell Even As Profit Rose
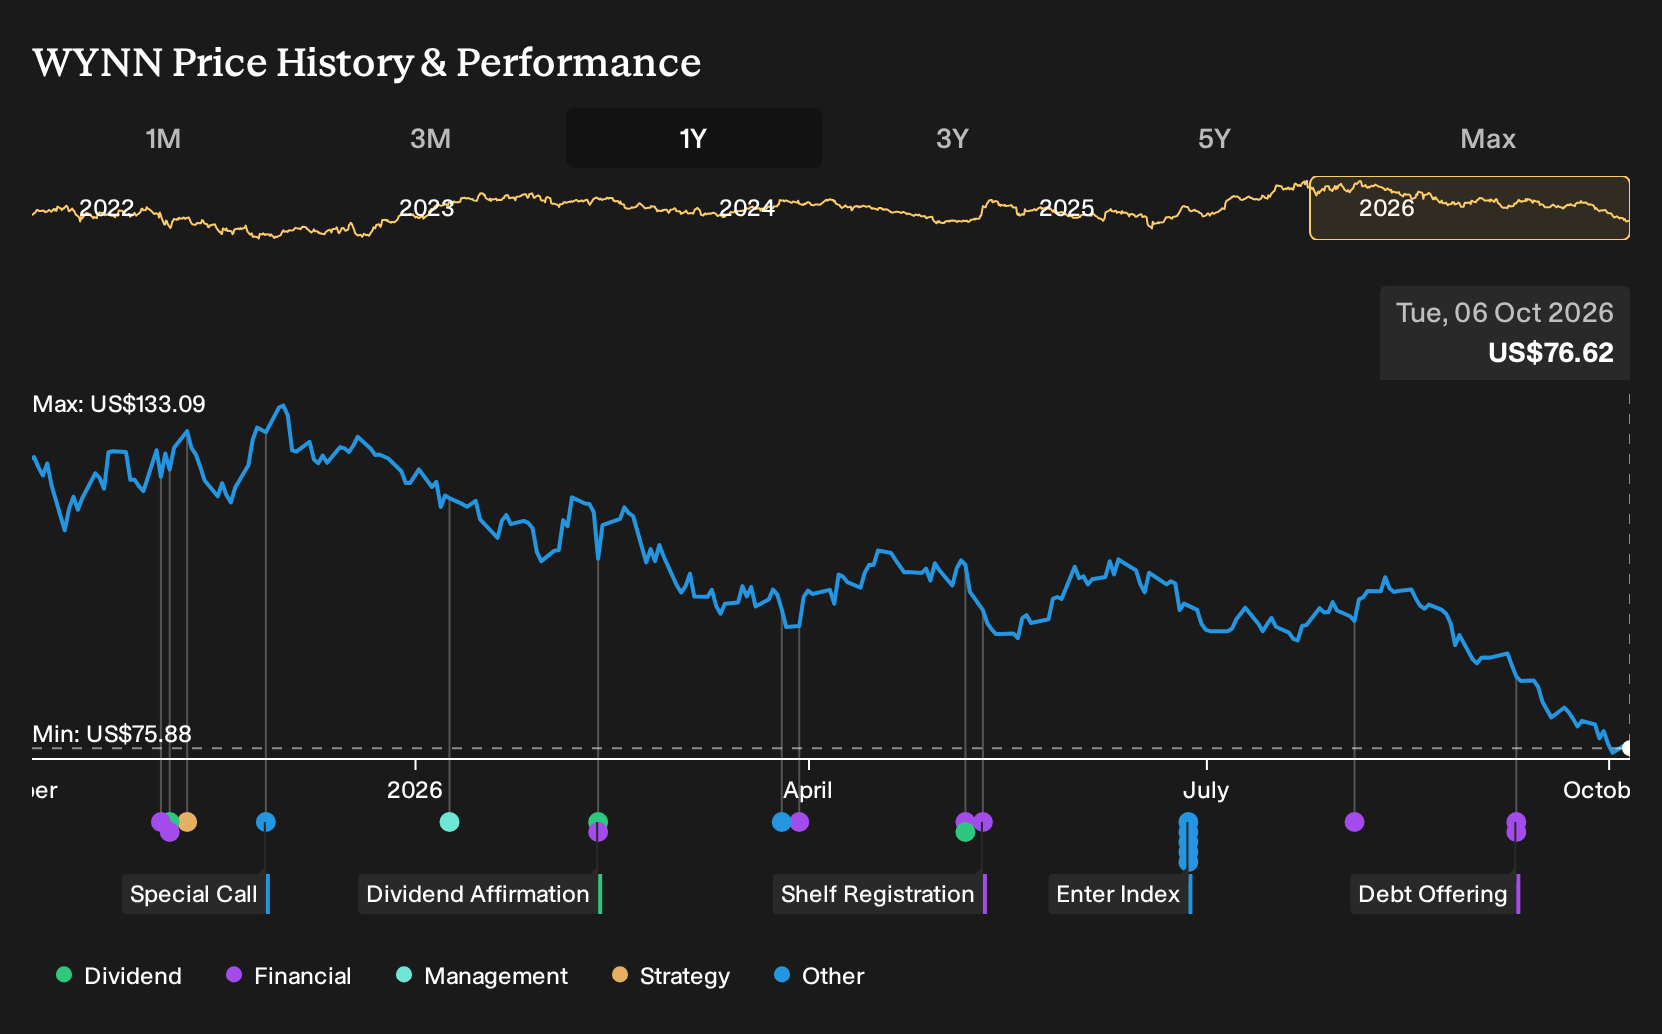
Wynn Resorts reported rising revenue and profit, yet anyone who stuck with the shares was rewarded with pain instead of celebration. Holding Wynn Resorts over the past year would have meant a 37.1% loss, including dividends. If you had been weighing a fresh investment back in October 2025, with upbeat commentary on Asia and the UAE on the table, what clues were already there that the business case and the share price might part ways so sharply?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Wynn Resorts. Zero in on 27 high quality undervalued stocks for companies trading below our estimates.
The Two Competing Stories Around Wynn Resorts
The shares cost US$125 at the start of the period, and anyone looking at Wynn Resorts then had to choose between two very different but reasonable stories.
On the bullish side, the Fair Value sat at US$135. This outlook was built around the expectation that Wynn Al Marjan Island would open up a new premium tourism hub and that revenue would grow 4.9% a year with margins rising toward 8.4%.
The bearish Narrative put Fair Value at US$101. This view emphasized digital gambling pressure on physical resorts, a 1.6% annual revenue decline assumption, and ongoing exposure to Macau regulation and geopolitical risk.
What The Results Tested In The Wynn Resorts Story
Wynn Resorts then reported Q2 2026 revenue of US$1.86b and net income of US$140.1m, with net margin rising from 3.8% to 7.5%. That outcome leaned toward the bullish case that expected improving profitability. Large capital commitments to Wynn Al Marjan Island and The Enclave in Macau kept the cautious view alive on execution and balance sheet risk, so the evidence cut both ways.
The lesson is simple. When a thesis leans on better margins, watch the reported net margin and required capital spend together, not just the top line or the headline project.
What The Fall In Wynn Resorts Might Be Paying You For Today
Wynn Resorts now trades at US$76.62, and the selected Narrative places Fair Value above that level on its own assumptions about future cash generation. The argument centers on whether premium-focused projects in Macau, Las Vegas, and the UAE can eventually carry the extra spending and debt.
After a share price decline of 37.1% over the past year, the key question is what has to go right from here. A buyer today would need to believe that capital-heavy developments and higher labor costs still translate into healthy incremental returns once the new capacity is up and running.
"A key factor is that Wynn Resorts successfully executes capital-intensive projects such as the Enclave tower in Macau and Wynn Al Marjan Island, while managing higher labor costs so that incremental returns justify the spending."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Where Could You Get There Earlier?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 44% below our estimate - advises on regulatory compliance, safety risks and technical disputes for specialized industries.
- Company 2 - 33% below our estimate - links compressed offshore project schedules to demand for subsea equipment and services.
- Company 3 - 24% below our estimate - sells high-performance chips supporting AI workloads integrated with proprietary development tools.
Three companies from the same screener. Open the full list of 25 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com