
Vertiv Holdings Co (VRT) Could Be 44% Undervalued Following Operations Leadership Change
Vertiv Holdings Co (VRT) is back in focus after appointing Michael Resha as Executive Vice President of Manufacturing, Logistics and Operational Excellence. This leadership shift is aimed at execution as demand for digital infrastructure grows.
Vertiv’s leadership reshuffle lands at a time when momentum has cooled in the short run. The share price is down about 10% over 30 days and roughly 20% over 90 days, while the year to date share price return is 44% and the 1 year total shareholder return is almost 60%. Multi year total shareholder returns are extremely high, which hints that investors are reassessing near term execution risks after a very strong run, while still crediting Vertiv Holdings Co with meaningful longer term value creation.
Scan how Vertiv Holdings Co fits into the wider build out of data and AI infrastructure by comparing it against our hand picked list of 91 AI infrastructure stocks.
Vertiv Holdings Co now trades at a modest discount to both analyst targets and an intrinsic value estimate after a sharp pullback. Are investors sensibly pricing execution risk, or underrating the new operating playbook?
Most Popular Narrative: 43.7% Undervalued
According to the most followed narrative, Vertiv Holdings Co screens as materially undervalued, with a fair value of $450 against a last close of $253.14. This frames the recent pullback less as a collapse and more as a reset in expectations.
They have essentially built a moat around the "thermal wall." As AI chips get faster and hotter, the standard air-cooling systems used by everyone else are hitting their physical limit. Vertiv is not just selling equipment; they are selling what some view as the only viable path to higher computing density. When you combine their installed base with their ability to design integrated, end-to-end power and cooling solutions, they can move from being a vendor to a more deeply entrenched partner.
See why 93 investors see Vertiv Holdings Co as 44% undervalued.
Result: Fair Value of $450 (UNDERVALUED)
Still, this narrative about undervalued Vertiv Holdings Co can weaken if large AI data center projects are delayed or if rival liquid cooling suppliers pressure its pricing power.
Find out about the key risks to this Vertiv Holdings Co narrative.
Another View: Vertiv Holdings Co Through The Earnings Lens
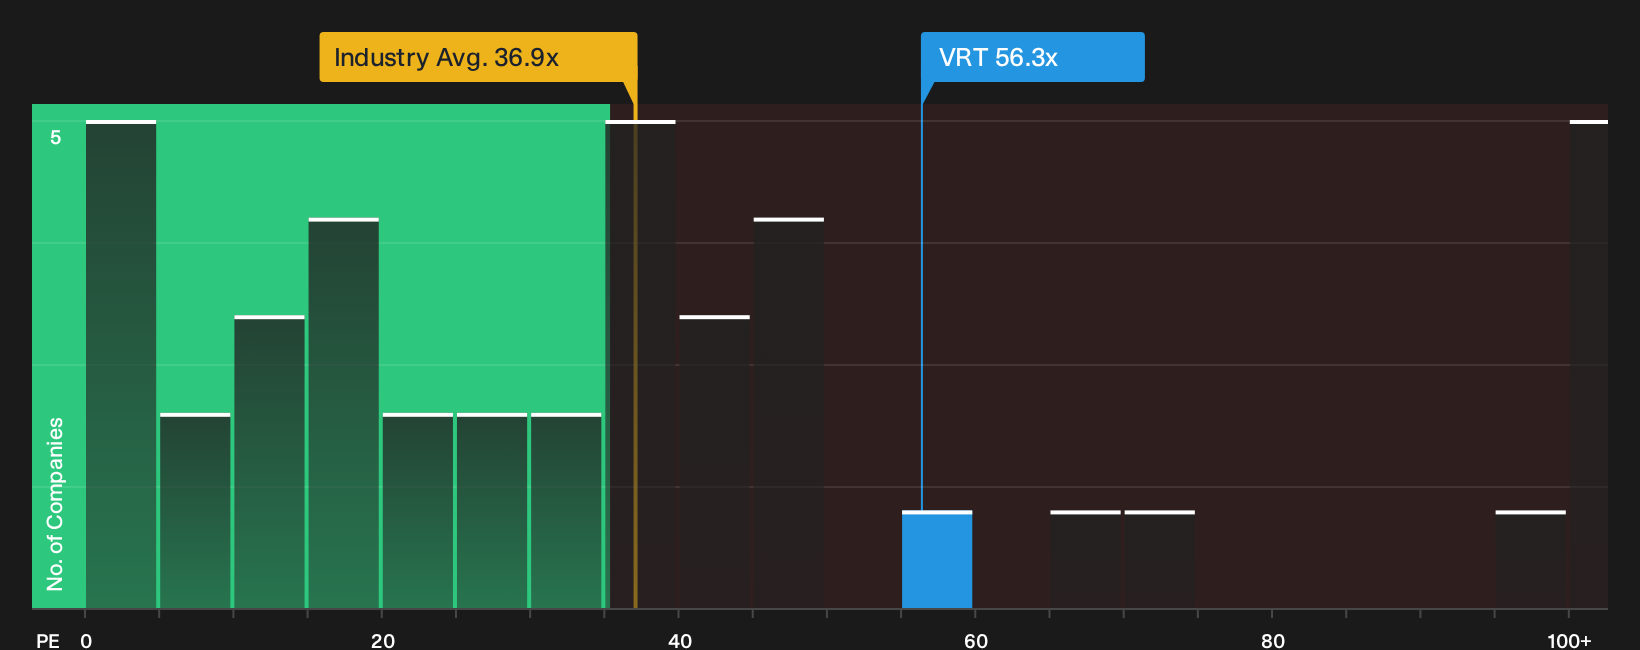
Vertiv Holdings Co screens as undervalued on our cash flow estimate, with the $253.14 share price sitting about 3.8% below an SWS DCF model value of $263.12. The P/E story is different though. At 56.3x versus a fair ratio of 50.9x and a US Electrical industry average of 36.9x, investors are paying a rich headline multiple. Is that premium headroom or valuation risk if sentiment cools again?
See what the numbers say about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Vertiv Holdings Co so far. If you want to move fast and form your own view, start by weighing its 4 key rewards.
Looking for more Vertiv Holdings Co sized ideas?
Do not stop your research with Vertiv Holdings Co. Broaden your opportunity set with a few focused screens that surface very different types of potential candidates.
- Target resilient cash generators by reviewing a list of solid balance sheet and fundamentals (25 results) that can better withstand shocks and still keep compounding through tougher conditions.
- Hunt for mispriced opportunities by scanning our 27 high quality undervalued stocks where fundamentals and price look out of sync in your favor.
- Spot future leaders early by tracking a 19 high quality undiscovered gems before the wider market starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com