
Earnings Preview: What to Expect From Bloom Energy's Report
Bloom Energy Corporation (BE), headquartered in San Jose, California, designs, manufactures, sells, and installs solid oxide fuel cell (SOFC) systems for on-site power generation. Valued at $87.1 billion by market cap, the company offers solid oxide fuel cells that convert natural gas, biogas, and hydrogen into electricity without combustion, resulting in low CO2 emission. The leading provider of SOFC technology is expected to announce its fiscal third-quarter earnings for 2026 in the near future.
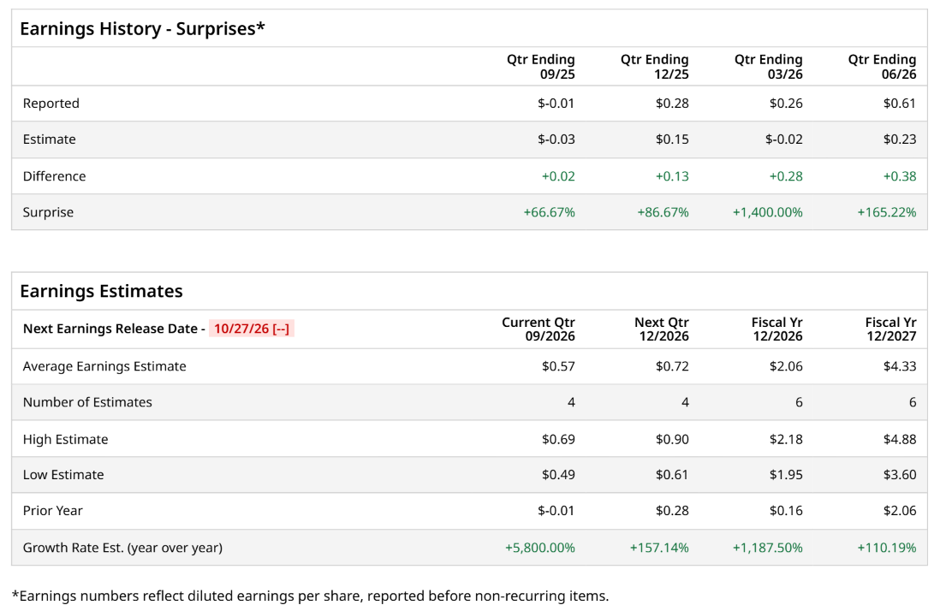
Ahead of the event, analysts expect Bloom Energy to report a profit of $0.57 per share on a diluted basis, up significantly from loss of $0.01 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Bloom Energy to report EPS of $2.06, up remarkably from $0.16 in fiscal 2025. Its EPS is expected to rise 110.2% year over year to $4.33 in fiscal 2027.
BE stock has significantly outperformed the S&P 500 Index’s ($SPX) 16% gains over the past 52 weeks, with shares up 240.1% during this period. Similarly, it substantially outperformed the State Street Industrial Select Sector SPDR ETF’s (XLI) 10.6% gains over the same time frame.
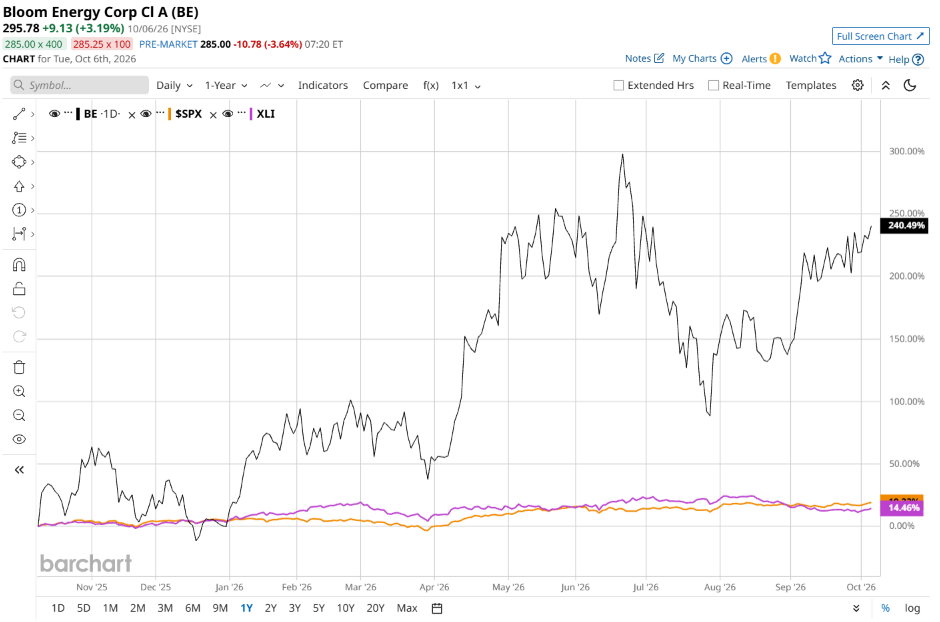
BE has outperformed primarily by positioning its solid-oxide fuel cells as a rapid, on-site, 24/7 power solution for the surging energy demands of AI data centers and utility-scale projects. Investor confidence has been propelled by major growth catalysts, including expanding manufacturing capacity toward 2 GW with a new facility in Fremont, key project wins like Nebius Group N.V.’s (NBIS) 300 MW AI data center, and utility interest such as Ameren Corporation (AEE) Missouri’s proposed 500 MW fuel cell integration. Furthermore, a massive boost came from expanding its financing partnership with Brookfield Asset Management Ltd. (BAM) to $25 billion, effectively removing the high upfront capital hurdle for customers scaling large AI infrastructure. While the stock has faced brief volatility due to project delays, such as a permitting setback for a natural gas pipeline serving Oracle Corporation’s (ORCL) Project Jupiter, the overwhelming long-term demand for off-grid, low-emission power in the AI ecosystem continues to drive its strong upward trajectory.
Analysts’ consensus opinion on BE stock is moderately bullish, with a “Moderate Buy” rating overall. Out of 27 analysts covering the stock, 11 advise a “Strong Buy” rating, two suggest a “Moderate Buy,” 13 give a “Hold,” and one recommends a “Strong Sell.” While BE currently trades above its mean price target of $285.82, the Street-high price target of $354 suggests an upside potential of 19.7%.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.