
Lumentum Could See a $3.3 Billion Payoff. Nvidia’s Optics Shift Is Moving Faster Than Expected.
Nvidia’s Optics Shift Is Arriving Early
GF Securities believes Nvidia (NVDA) is rolling out co-packaged optics faster than expected, and it sees Lumentum (LITE) as a key winner. Co-packaged optics build the light-based parts that move data into the chip's package itself. Near-packaged optics place them on the board nearby, where they're easier to replace. Both rely on lasers, which Lumentum supplies. GF said TSMC (TSM) has added testing capacity to support the ramp. It expects Nvidia to ship about 100,000 of these switches in 2027. For Lumentum, GF forecasts laser revenue from both technologies of about $928 million in 2027, rising to roughly $3.3 billion in 2028.
Lumentum Wins Either Way
What I like most is where that 2028 growth comes from. About $2.55 billion is expected to come from near-packaged optics, far more than the $750 million from co-packaged optics. The reason I like this is that GF expects Nvidia to develop both versions side by side, including for its future Feynman chips. Lumentum supplies lasers for both, so it doesn’t need to bet on which design wins. I believe that removes one of the biggest risks in a new technology shift.
My bigger concern is how long this could take. These systems aren’t expected to roll out widely until the second half of 2027, and new hardware ramps often slip.
The Growth Could Justify the Price
The forward GAAP P/E of 45.82x has no meaningful five-year average, since past losses distort Lumentum’s history. The forward price-to-sales ratio of 13.75x is more than 2.5 times its five-year average of 5.30x. This shows the market now treats it as an AI growth story. The EPS outlook explains the premium. Analysts expect earnings to rise about 151% this fiscal year and 59% the next. At fiscal 2028 earnings, the P/E would drop to roughly 29x, around the time GF expects optics revenue to surge. Lumentum also holds about $1 billion more cash than debt. I think the growth could justify the price if it arrives as expected.
GF’s forecast gives Lumentum a clear path to much bigger sales. What matters now is whether Nvidia’s rollout stays on schedule.
About LITE Stock
Lumentum Holdings provides optical and photonic products. It operates through two segments: Components, which includes lasers and other optical chips, and Systems, which includes cloud transceivers and optical circuit switches. In recent years, it has become a crucial backbone of the global AI boom. Founded in 2015, the company is headquartered in San Jose, California.
LITE stock surged over 580% over the last year, thanks mainly to booming AI data center demand for its optical networking components and record earnings. In contrast, iShares US Telecommunications ETF (IYZ) was up only 30% during the same period. The trend has continued this year as well, with LITE up 183% YTD, while the ETF rose 25% during the same period.
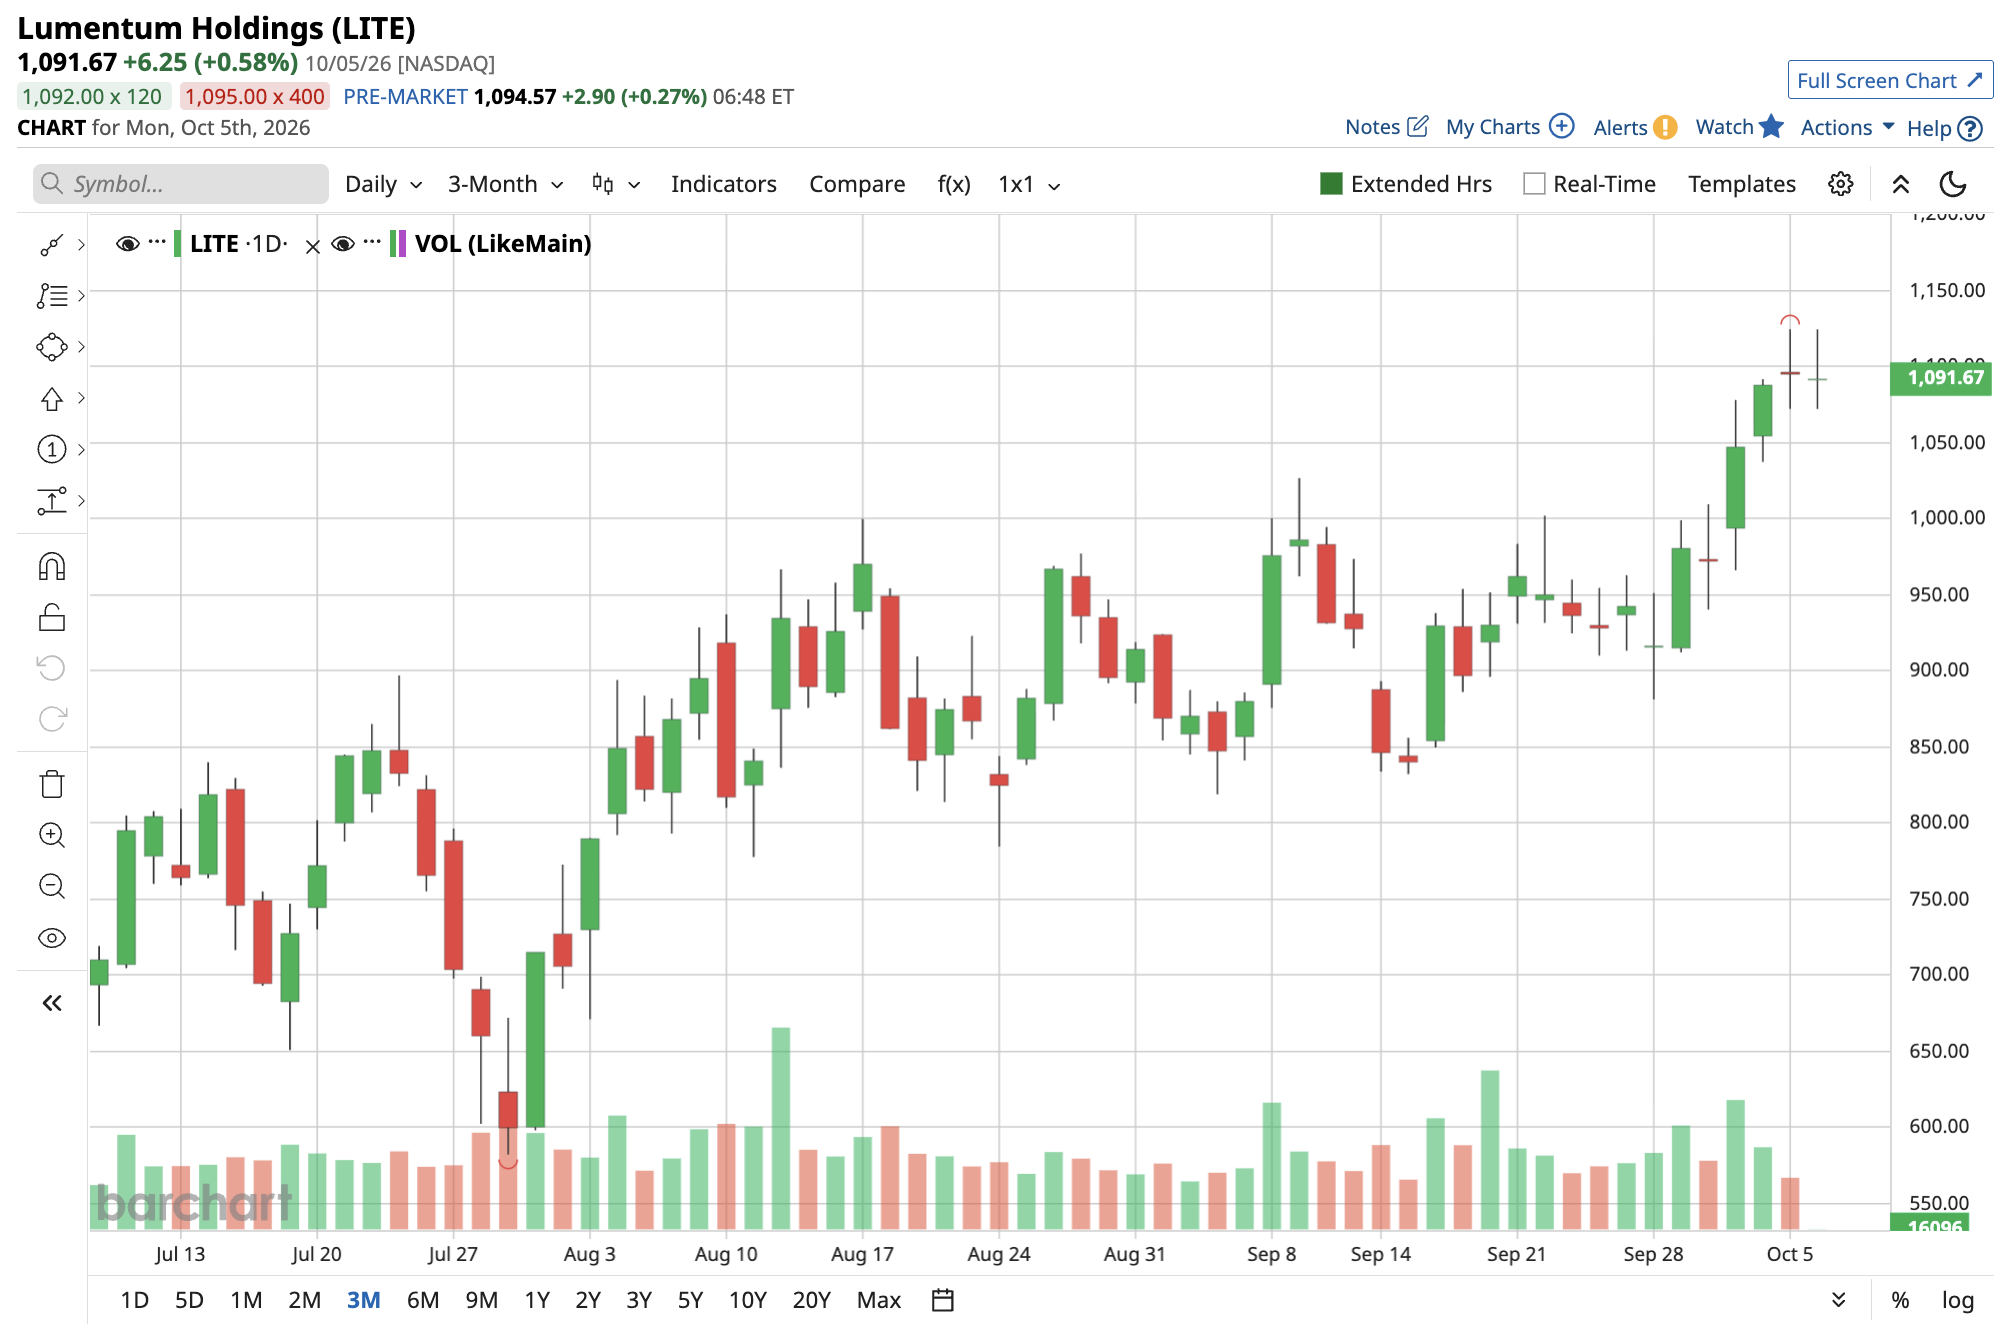
Lumentum's Outlook Signals Continued AI-Driven Demand
Lumentum reported its fourth-quarter fiscal 2026 earnings on August 11. Revenue came in at $1.01 billion, up 109% year-over-year. Non-GAAP diluted earnings per share came in at $3.23, comfortably beating the Wall Street consensus of $2.95. The quarter also showed meaningful operating leverage. Non-GAAP operating margin for the quarter was 36.6%, up 250 basis points sequentially.
For the first quarter of fiscal 2027, Lumentum guided revenue of $1.225 billion to $1.275 billion, implying over 130% growth at the midpoint. Non-GAAP EPS is expected to be $4.05 to $4.35. CEO Michael Hurlston said AI demand puts Lumentum on track to reach its $1.25 billion quarterly revenue target more than a quarter early. Lumentum also holds a co-packaged optics order worth several hundred million dollars, due in the first half of 2027, which supports GF’s outlook.
What Do Analysts Expect for Lumentum Stock?
Along with GF Securities, others on Wall Street have also grown more bullish on the stock lately. On Oct. 5, Stifel Nicolaus raised its price target from $1,100 to $1,232 and kept a Buy rating. Analyst Ruben Roy says limited supply remains the main constraint on AI infrastructure buildouts. Just a few days prior to this, Citi also raised its price target from $1,200 to $1,400 while keeping a Buy rating.
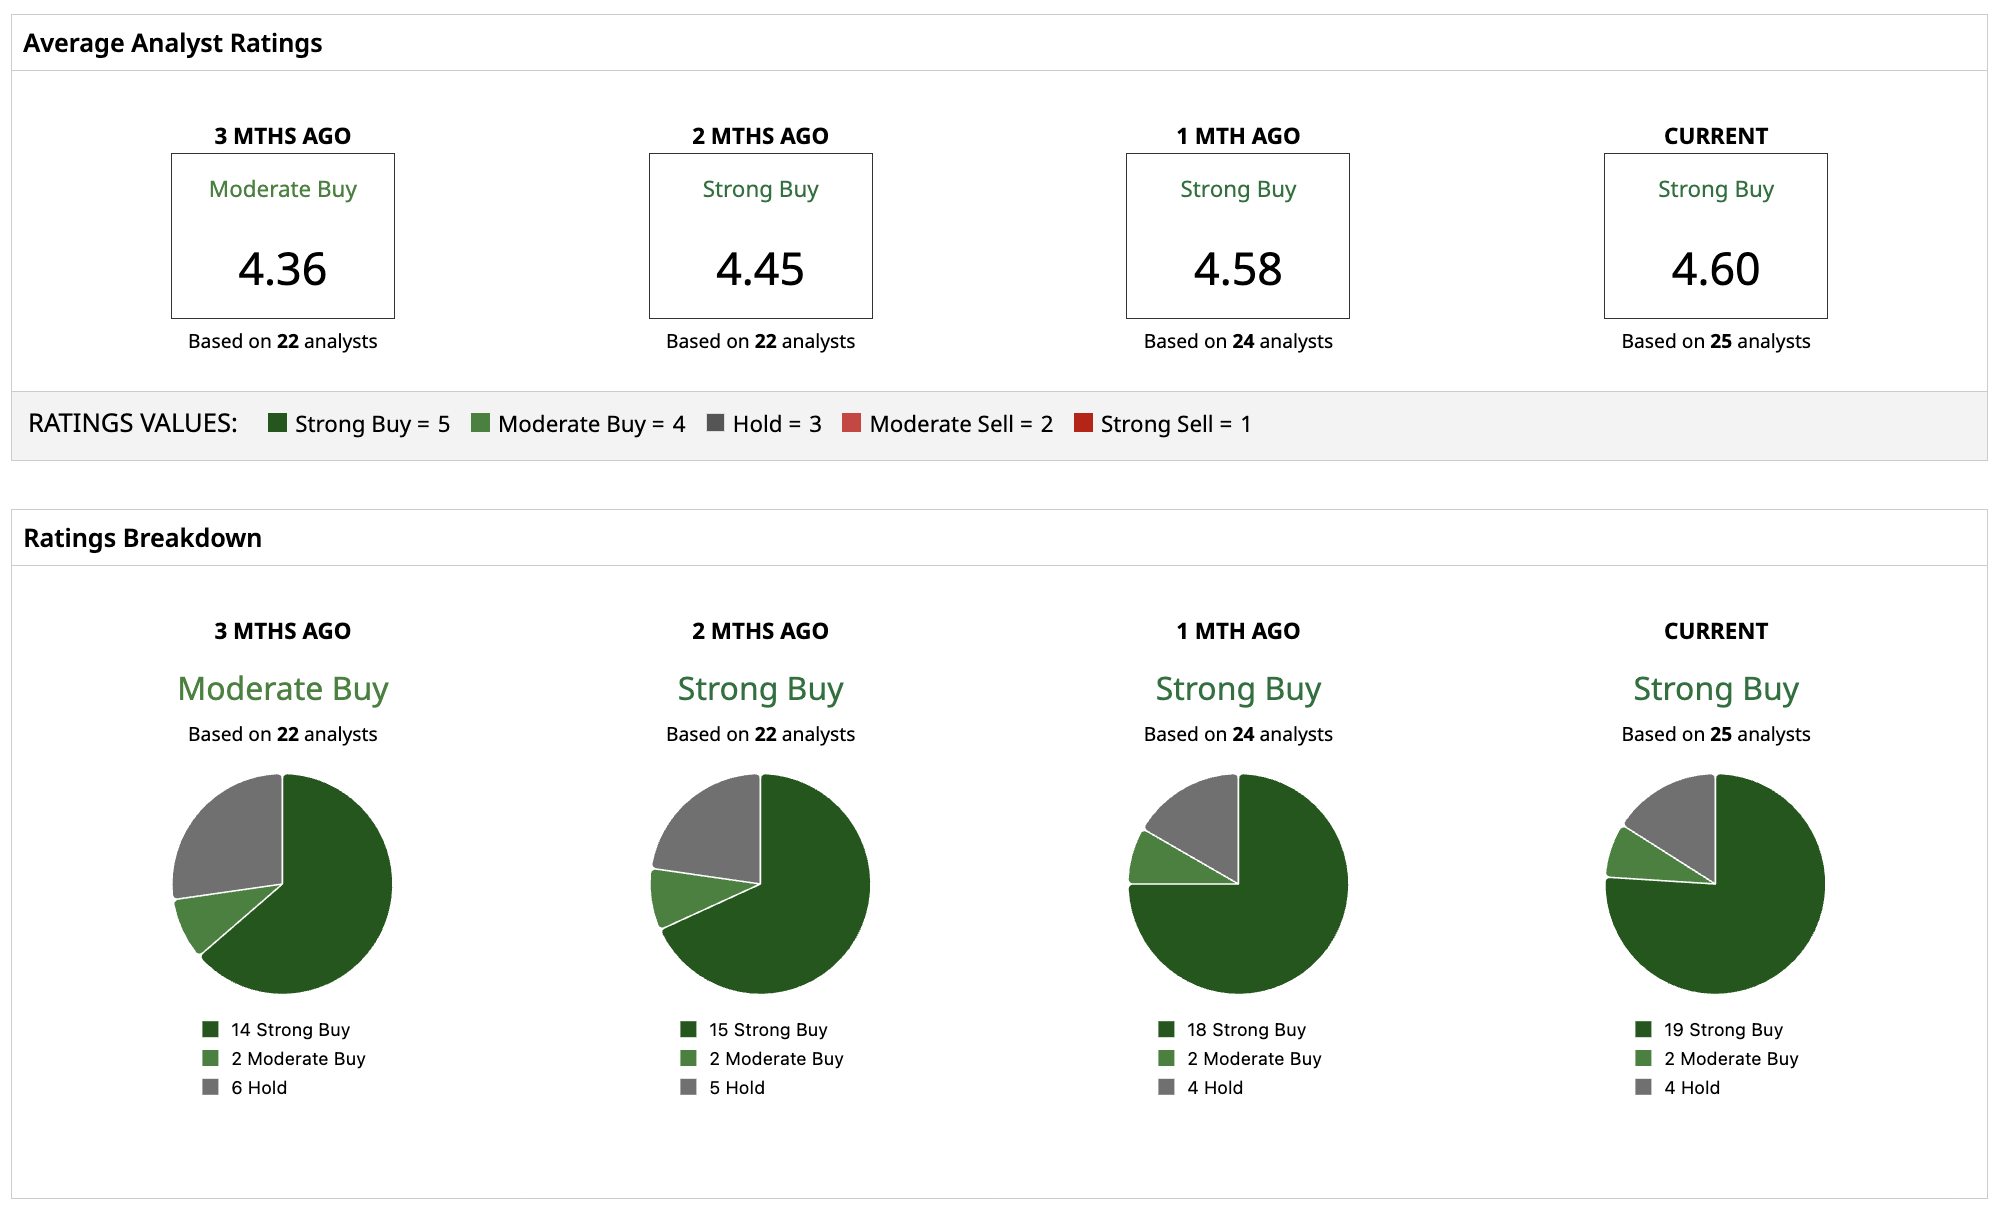
Based on 25 Wall Street analysts, Lumentum holds a Strong Buy rating with a mean price target of $1,149.40, indicating a modest 5% upside. The small upside suggests much of the optics growth is already priced in.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.