
Kennametal (KMT) Could Be 3% Overvalued On Its Cost Cutting Narrative
Kennametal (KMT) has quietly drawn fresh attention after a solid run, with the stock up about 7% over the past week and year-to-date returns above 15%.
That brief rally fits into a wider upswing for Kennametal, with a 1-year total shareholder return of about 60.9% and a 3-year total shareholder return near 48.7%, signaling momentum that has recently outpaced the more modest 90-day share price return.
Scan beyond Kennametal's run and consider other industrials showing strong fundamentals in our hand-picked list of solid balance sheet and fundamentals (25 results) for potential ideas to research next.
The sharp move in Kennametal has already rewarded early buyers, yet a wide gap between recent price action and its implied intrinsic value still sits on the table. How much of that spread can realistically close from here?
Most Popular Narrative: 3% Overvalued
Kennametal's most followed narrative pegs fair value at $32.43, slightly below the last close of $33.41. This frames the recent price strength as running a touch ahead of its modeled worth while still tethered to fundamentals shaped by cash flow assumptions and a 9.16% discount rate.
The company is actively rightsizing capacity and executing structural cost reductions, including plant closures and workforce optimization. These actions are projected to produce US$125 million in run rate savings by fiscal 2028. Together with the US$27 million of restructuring savings already realized in fiscal 2026 and the reiterated US$110 million savings goal by fiscal 2027, these initiatives could provide multi year support for net margins and earnings.
See why 4 investors see Kennametal as 3% overvalued.
Result: Fair Value of $32.43 (OVERVALUED)
Still, the Kennametal story could look very different if tungsten pricing benefits fade faster than expected, or if demand softens in key industrial and aerospace markets.
Find out about the key risks to this Kennametal narrative.
Another View: Kennametal Through The Earnings Lens
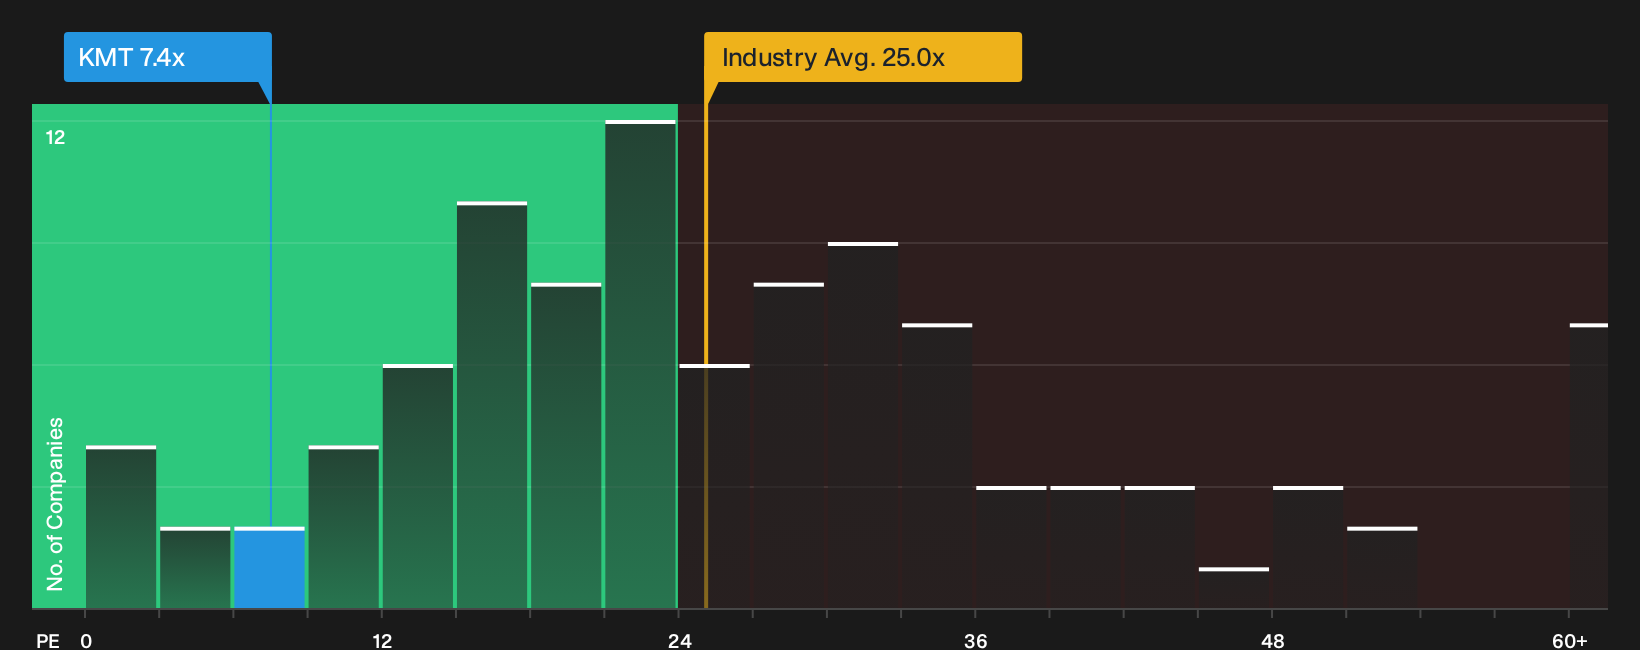
The consensus narrative tags Kennametal as roughly 3% overvalued against a $32.43 fair value, yet the current P/E of 7.4x tells a very different story. That multiple sits well below the estimated fair ratio of 9.8x and far under the US Machinery average of 24.7x, which points to a wide gap between what recent earnings suggest and what the market is prepared to pay. Is that discount a useful margin of safety or a sign that investors expect today’s earnings power to fade?
To see how that valuation gap is built from the ground up, including comparisons with peers and the fair ratio the market could move toward, take a closer look at our detailed multiples breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Kennametal's value case are clear, so move quickly to test the numbers, weigh both risks and rewards, and then decide where you stand with the 4 key rewards and 4 important warning signs
Looking for more Kennametal-like investment ideas?
If Kennametal has sharpened your interest, do not stop here. Use the Simply Wall Street Screener to spot other opportunities before they move without you.
- Target companies that combine quality and a valuation gap by reviewing our hand picked 27 high quality undervalued stocks.
- Strengthen your income side by studying stocks in the 8 dividend fortresses that aim to pair higher yields with resilience.
- Dial down portfolio risk by focusing on financially robust businesses through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com