
How Strong Earnings Will Impact CarMax (KMX) Investors
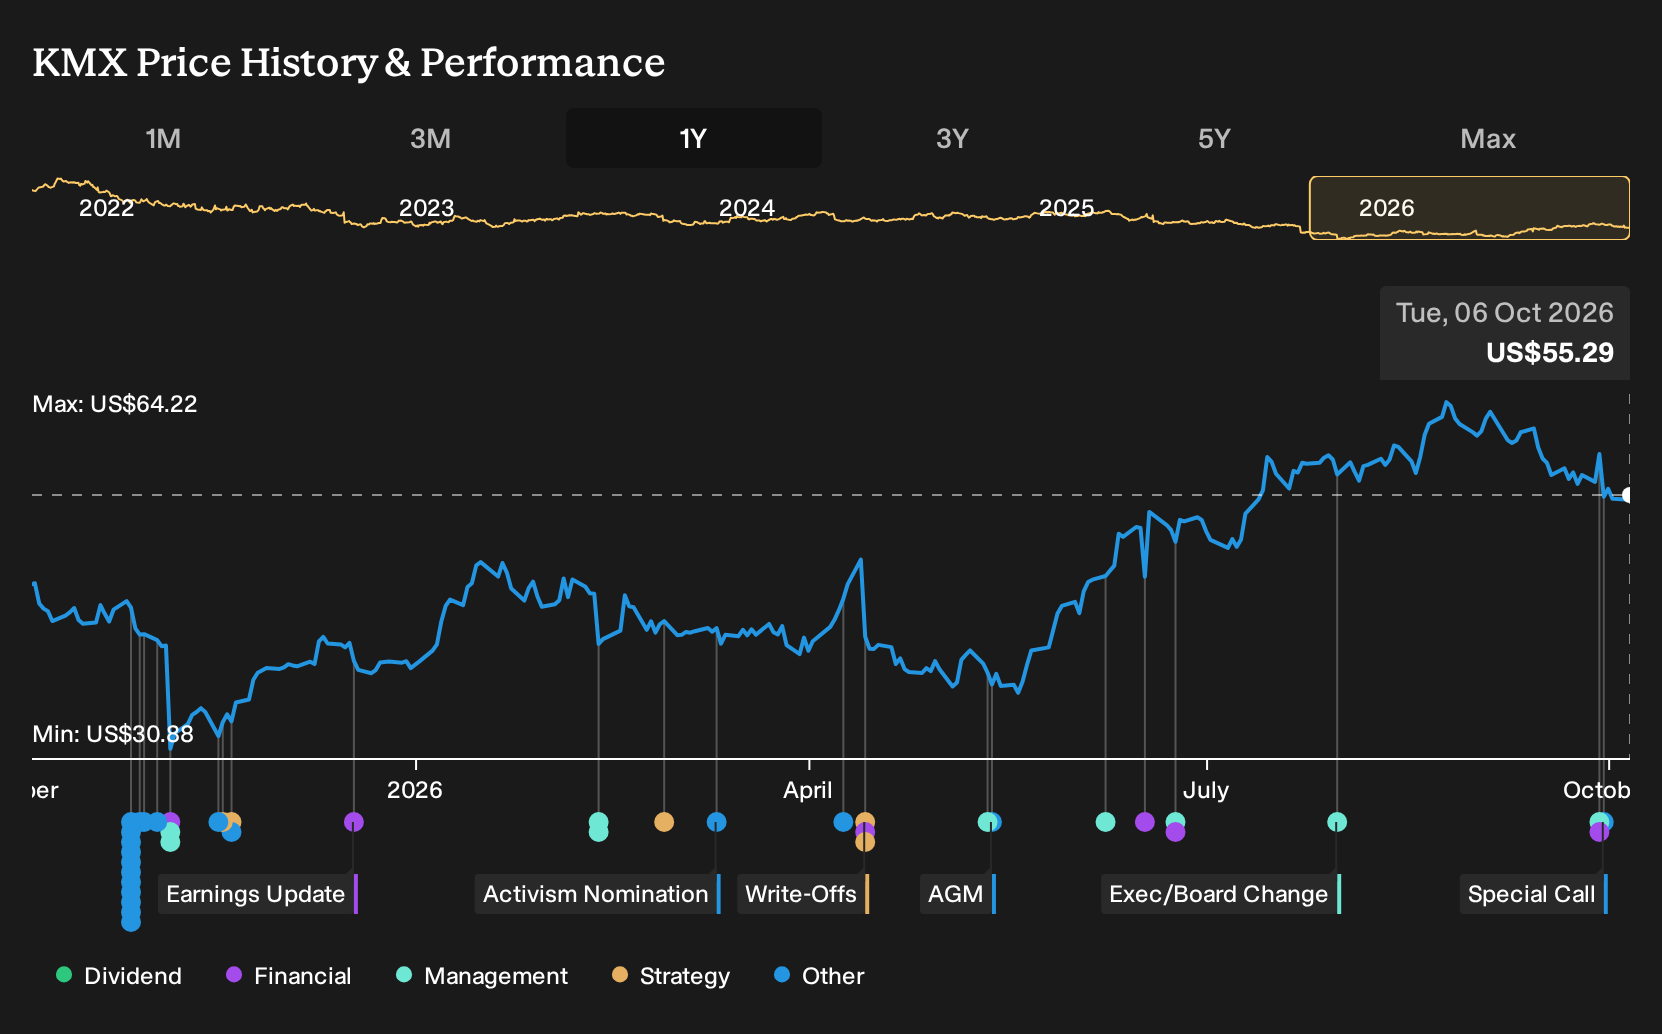
- CarMax reported second quarter sales of US$208.44 million and net income of US$165.29 million, alongside senior leadership changes focused on digital, customer experience, and centralized strategy functions.
- The new Executive Vice President, Chief Digital and Customer Officer role signals a push to closely align marketing, product, Edmunds, and data tools around one integrated buying journey.
- We will now see how CarMax's higher earnings and new Chief Digital and Customer Officer could influence the broader investment narrative.
CarMax Investment Narrative Recap
To own CarMax, you need to believe its used car model can translate digital investment and omnichannel execution into steadier profitability, even as margins stay under pressure. In the short term, the swing factor still looks like unit economics. Wholesale profit per vehicle, reconditioning costs, and credit loss provisioning remain the levers that could move earnings most quickly.
The recent quarter showed higher sales and net income alongside the new Shift into GEAR leadership structure. That supports the execution story but does not immediately change the main risk. Debt coverage by operating cash flow and thin 1% net margins still leave little room for error if sourcing costs or credit losses worsen.
The most relevant update for that catalyst is Elizabeth Dirgins stepping in as Executive Vice President, Chief Digital and Customer Officer. Her remit spans marketing, product, Edmunds, and digital tools. That places a single owner over the full customer path, from first search through closing the deal online or in store.
For you, the question is whether this setup helps CarMax drive more consistent omnichannel traffic, improve lead conversion, and sharpen pricing without eroding per unit profit. If execution is strong, it could support the existing earnings growth forecasts. If customer acquisition costs rise or inventory turns slow, the margin and cash flow risks remain front and center.
CarMax's analyst narrative projects US$29.7b revenue and US$811.7m earnings by 2029. That sits on a forecast of fairly flat yearly revenue growth and requires an earnings increase of about US$519m from US$292.4m today.
Uncover why CarMax's fair value indicates a 13% potential upside to its current price, while that discount to CarMax's story may not last long.
Exploring Other Perspectives
Some of the most optimistic analysts anchor their alternate CarMax view on Shift into GEAR and omnichannel and AI projects driving used unit comps well ahead of consensus. Before this leadership news, they were modelling about US$31.2b of revenue and US$847.2m of earnings by 2029. You can treat today’s appointments and earnings jump as new information that may push those narratives closer together or further apart, and then explore which version of the story you find more convincing.
Explore 5 other CarMax fair value estimates, including one that suggests up to 63% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and independent judgment.
- A great starting point for your CarMax research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CarMax. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CarMax's overall financial health at a glance.
Looking For More Investment Ideas Beyond CarMax?
If you want to put CarMax in context, the next step is to compare it with other businesses that show different mixes of balance sheet strength, income potential, and risk. The Simply Wall St Screener can help you quickly surface a focused short list rather than sifting through hundreds of tickers on your own.
- If capital preservation ranks high for you, start with a set of companies that score well on stability and financial resilience through our 31 resilient stocks with low risk scores.
- For investors who care about robust finances supporting long term compounding, filter for stocks with strong cash positions and sensible leverage via the list of solid balance sheet and fundamentals (25 results).
- If you prefer to hunt for underfollowed opportunities, scan a pre filtered basket of quality businesses flying under the radar using the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com