
AstraZeneca (LSE:AZN) Stock Looks Below Fair Value As Spending Rises
AstraZeneca has been active on the deal and research front, while the share price has drifted and now trades well below its early-year levels. That raises a straightforward question for investors about whether today’s valuation is still in line with the earnings power of the business.
- Over the past 5 years the stock has delivered a 49.2% total return, so anyone looking at AstraZeneca today is really asking whether that longer run justifies the current earnings multiple.
- The recent US$2b commitment to Summit Therapeutics and the opening of a US$1b research hub in Massachusetts can support expectations for future oncology revenue, but they also mean higher upfront spending that matters for how investors think about near term earnings and cash generation.
- There is a second opinion on AstraZeneca worth weighing. See what analysts think AstraZeneca's shares could be worth.
The issue now is whether the earnings that AstraZeneca generates today, and what investors reasonably expect from them, are enough to support the current share price.
If you want to pressure test AstraZeneca’s current P/E against other businesses, it can help to compare it with 6 high quality undervalued stocks.
Is AstraZeneca a Bargain on Earnings?
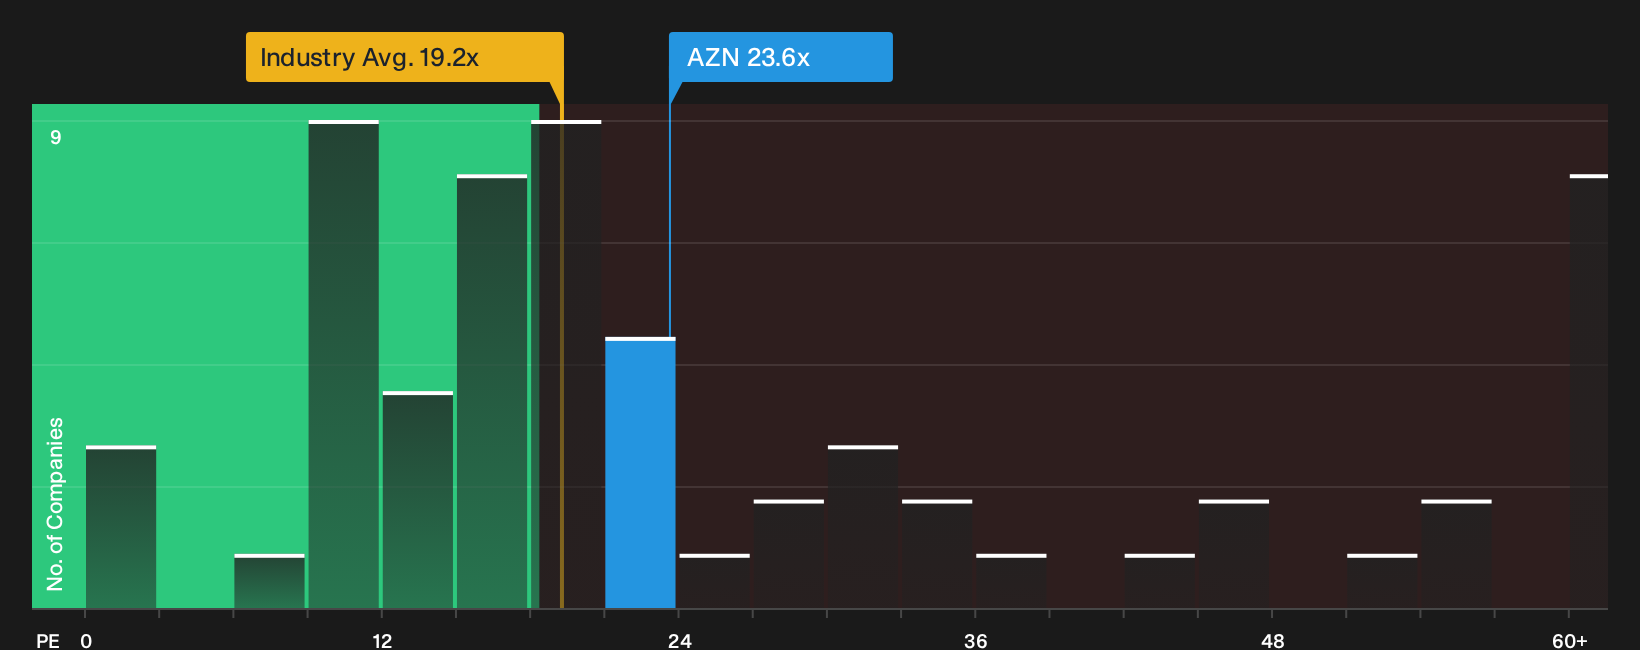
AstraZeneca is usually judged on earnings, so the P/E ratio is a natural starting point for the price tag you see on the screen. The stock trades on about 23.6x earnings, which sits slightly above the wider Pharmaceuticals industry average near 21.7x. Against a peer group closer to 46.8x, the market is not giving this business the same headline multiple as some larger growth oriented drug makers.
The fair multiple implied by a tailored model that factors in AstraZeneca’s margins, size and sector risk sits above the current 23.6x. This points to the shares screening as undervalued on this framework. Because the recent US$2b Summit Therapeutics deal and the US$1b R&D hub in Massachusetts both raise upfront spending expectations, the fact that the P/E still comes in below that fair reference level suggests investors are not paying a full premium for the oncology pipeline. Explore the numbers behind AstraZeneca's P/E valuation.
The AstraZeneca Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where AstraZeneca's valuation question leaves off by spelling out which assumptions on growth, profitability and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price, while tying each hypothesis about AstraZeneca's future catalysts and risks to its own estimate of fair value so you can later compare which storyline is tracking reality on the Community page.
Community views on AstraZeneca are split between investors who see more upside in the current price and others who think expectations already bake in a lot of the good news.
Bull case: 25% undervalued
"The company's robust and diversified late-stage pipeline, particularly in oncology, rare diseases, and cardiovascular/metabolic therapies, is set to deliver multiple blockbuster launches over the next several years…"
Discover why this Narrative puts AstraZeneca at 25% undervalued.
Bear case: roughly fairly valued
"The looming expiration of patents on key blockbuster drugs like Tagrisso, Farxiga, and Imfinzi exposes AstraZeneca to biosimilar and generic competition that is almost certain to erode high-margin revenue streams…"
Explore why this Narrative puts AstraZeneca at roughly fairly valued.
Before you act on AstraZeneca’s valuation, one more piece matters
Price tags and pipelines only tell part of the story for AstraZeneca, because the people steering the course and how their rewards line up with your interests can tilt the risk and return profile in quiet but important ways. See who runs AstraZeneca and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com