
Is XPO (XPO) Trading At A Discount Following Its New Service Center Openings?
XPO (XPO) has just added new service centers in Mesa, Arizona and Cameron, Missouri, expanding its freight footprint in the Phoenix and Kansas City areas and sharpening its competitive position.
For context, XPO shares trade at US$183.49, with a 1-day share price return of 0.34% and a 7-day share price return of 3.45%. The 30-day and 90-day share price returns are down 4.98% and 10.31% respectively, yet the year-to-date share price return of 32.21% and 1-year total shareholder return of 38.58% point to positive momentum over a longer stretch, supported by earlier expansion moves and now reinforced by the Mesa and Cameron openings.
Scan more freight and logistics players that share XPO’s network expansion theme with a curated set of 44 power grid technology and infrastructure stocks to see how other infrastructure heavyweights are positioning for demand.
XPO now trades about 21% below an intrinsic value estimate and roughly 25% under the average analyst target after its latest service center openings. Is that discount caution well placed or is it starting to look excessive?
Most Popular Narrative: 21% Undervalued
The most followed XPO thesis pegs fair value around $231.83 per share, well above the last close at $183.49. This frames the current pullback as a valuation gap rather than the end of the story.
The company is positioned to benefit from an industry wide reset in LTL capacity. Service center counts and door counts at the sector level are down since 2021, while XPO has raised its own tractor, trailer, and door capacity and now carries more than 30% excess doors, which can support shipment growth and revenue as freight demand recovers.
See why 12 investors see XPO as 21% undervalued.
On this view, the 20.9% discount to an estimated fair value uses an 8.56% discount rate and relies on XPO converting its LTL network density, AI driven productivity tools and European options into higher earnings and free cash flow over time. The gap between the $183.49 share price and the roughly $231.83 narrative fair value highlights the tension between recent share price weakness and a model that focuses on improving profitability and cash generation.
Result: Fair Value of $231.83 (UNDERVALUED)
Still, this XPO story can break if freight end markets stay soft for a long stretch, or if rising driver and labor costs outpace productivity gains.
Find out about the key risks to this XPO narrative.
Another View: What XPO’s P/E Is Telling You
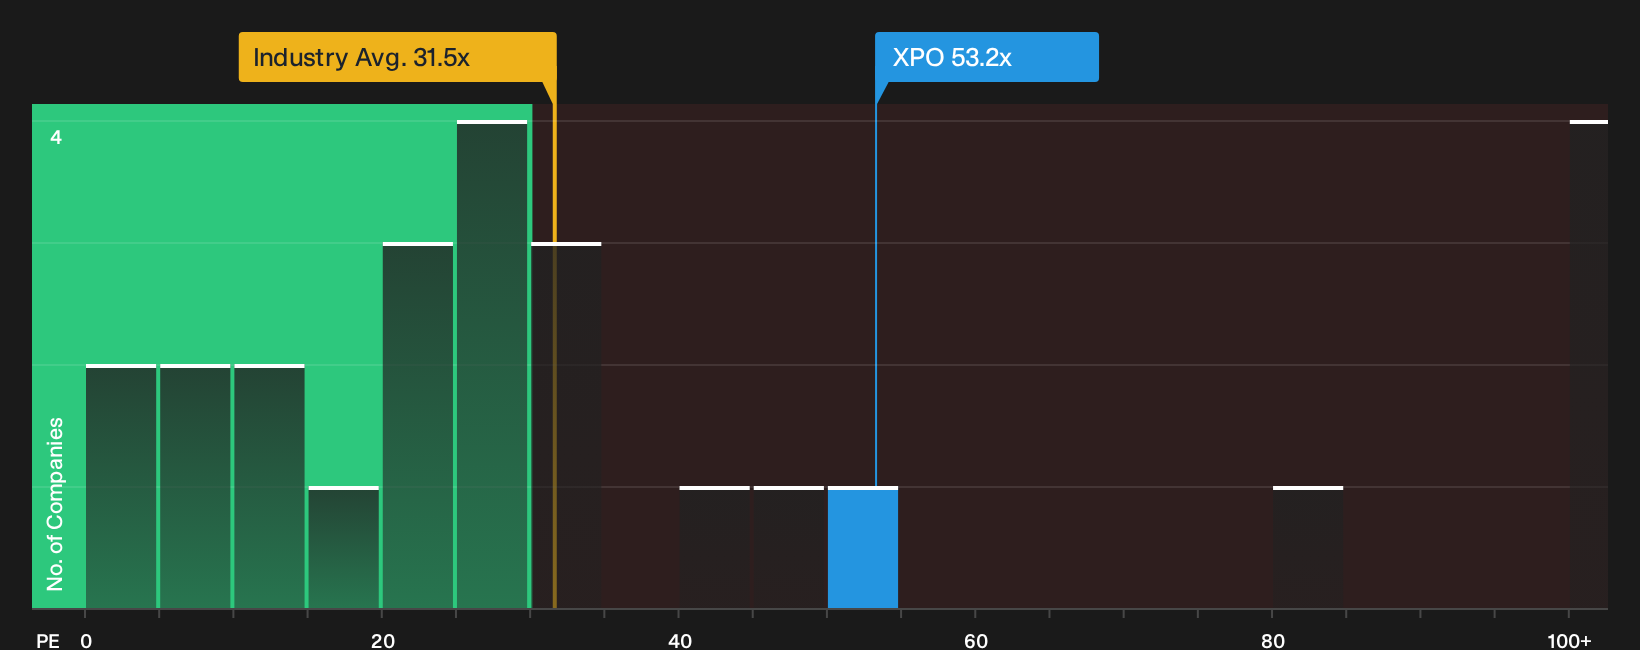
There is a catch. While XPO screens as about 21% below an intrinsic value estimate, the stock trades on a P/E of 53.2x compared with roughly 32x for the wider US Transportation group and a fair ratio of 21.8x that the market could move toward over time.
That multiple is cheaper than the 69x peer average, yet still far above the fair ratio, which points to meaningful valuation risk if sentiment cools or earnings delivery slips even modestly. The question for you is whether the quality and growth profile justify paying this kind of premium today.
To see how that premium lines up against detailed valuation work, including industry and peer comparisons, See what the numbers say about this price — find out in our valuation breakdown..
Here is how the current P/E stacks up against sector levels visually, which can help you judge how far sentiment may have to move if expectations reset,
Next Steps
If this mix of optimism and caution around XPO feels familiar, use it as a prompt to check the numbers yourself and move fast while sentiment is still forming. Then carefully weigh both sides of the ledger by reviewing 3 key rewards and 2 important warning signs.
Looking for more XPO style investment ideas?
If XPO has sharpened your interest, do not stop here. Broaden your watchlist now, before the next wave of opportunities moves without you.
- Target potential mispricing by scanning a curated set of 27 high quality undervalued stocks that pair robust fundamentals with prices that lag their underlying strength.
- Build steadier cash flow potential by reviewing a focused group of 8 dividend fortresses that prioritize consistent payouts alongside financial resilience.
- Reduce portfolio stress by filtering for a 31 resilient stocks with low risk scores that screens companies with sturdier balance sheets and lower risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com