
DKS (TSE:4461) Invests ¥10b In Capacity Following Data Center Buzz But Is It Fully Valued
DKS (TSE:4461) has put a roughly ¥10b capital investment on the table after its September 30 board meeting, targeting expanded capacity for low-dielectric resin materials related to data center and high-speed communications demand.
That investment decision comes after a powerful run in DKS shares. The stock has delivered a 22.03% 1 month share price return and a 58.73% 3 month share price return. The 1 year total shareholder return of 177.10% and a very large 3 year total shareholder return suggest that investors are already pricing in stronger growth potential and a different risk profile than in the past.
Scan for other chemical and materials stocks tied to data centers and high-speed communications by reviewing the hand picked 92 AI infrastructure stocks that fit a similar infrastructure demand story.
DKS has already sprinted higher on the data center story, and a ¥10b buildout is now locked in. The real task is deciding whether that reshapes value enough to justify jumping in today or waiting for calmer prices.
Preferred P/E of 21.4x for DKS: Is it justified?
Valuation for DKS now leans heavily on what investors are willing to pay for each yen of profit. At a P/E of 21.4x, the share price reflects a richer tag than many peers even after the recent surge to ¥16,730.
The P/E ratio compares the current share price with earnings per share. For a chemicals and materials business like DKS, it acts as a quick gauge of how much optimism investors are attaching to its profit profile, including the data center and high-speed communications exposure that is drawing attention.
DKS is trading on 21.4x earnings while the estimated fair P/E from the SWS fair ratio model sits lower at 18.4x. That gap implies the market is pricing in stronger or more resilient profits than the fair ratio suggests investors might eventually be willing to pay.
Peer context is even starker. DKS carries a 21.4x P/E against a JP Chemicals industry average of 13x and a peer group average of 13.5x. This signals a clear valuation premium and a level the share rating could move toward if sentiment cools.
Explore the SWS fair ratio for DKS.
Result: Price-to-earnings of 21.4x (OVERVALUED)
Still, the data center story for DKS can stumble if high-speed communications investment slows, or if the ¥10b capacity build drags on profitability longer than expected.
Find out about the key risks to this DKS narrative.
Another View: What The DCF Model Says About DKS
The market is charging a premium P/E for DKS, yet the SWS DCF model points in a different direction. On that cash flow view, the stock price of ¥16,730 sits about 1% below an estimated value of ¥16,891.78, which frames a much tighter pricing gap than the earnings multiple suggests. So is the crowd paying up too far, or is the DCF being too cautious?
For a closer look at how that cash flow estimate is built and what assumptions drive it, Look into how the SWS DCF model arrives at its fair value.
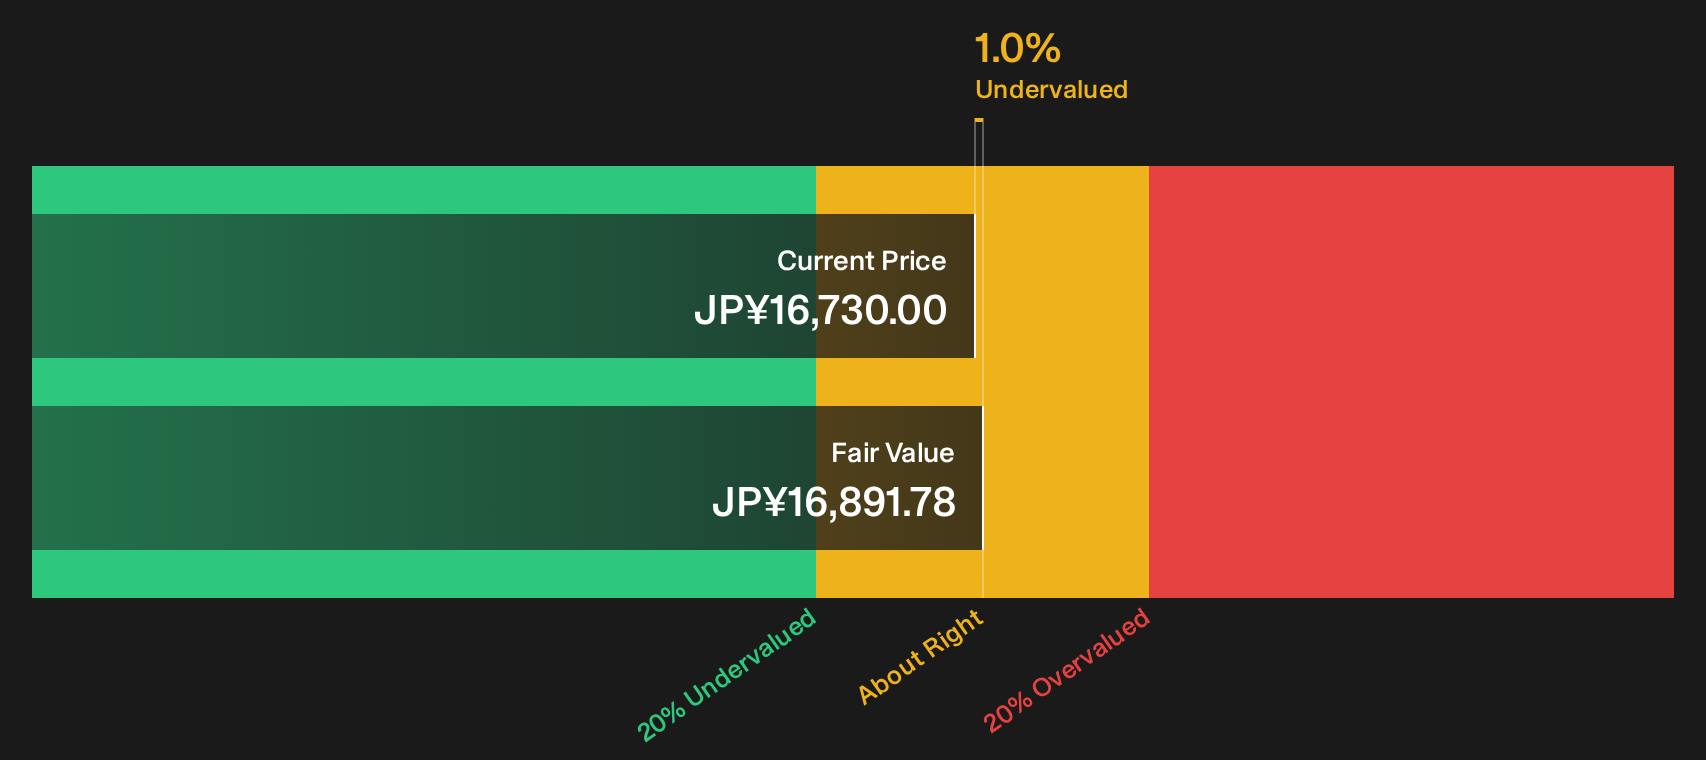
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DKS for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Opinions are mixed on whether DKS now appears expensive or fairly priced. Review the latest data while it is current and form your own view with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond DKS?
If you stop with DKS, you only see one angle. Broaden your watchlist with fresh setups that could match different goals, risk levels, and income needs.
- Target potential mispricing by scanning a 15 high quality undervalued stocks that filters for quality fundamentals paired with prices that may not fully reflect the underlying business strength.
- Build a steadier base of holdings through a 22 resilient stocks with low risk scores focused on companies with more resilient profiles and lower overall risk scores.
- Spot earlier stage potential by reviewing a 1 elite penny stocks with strong financials that highlights smaller stocks with stronger financials than many investors might expect.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com