
Rivian (RIVN) Stock May Trade At A Premium As Delivery Outlook Holds
Rivian Automotive has seen its share price fall 26.1% over the past three years, which puts the focus squarely on whether the current US$14.51 price still lines up with the sales the business is generating. With the market reassessing expectations after a mixed share price record, the question now is how that recent performance and the latest updates feed into a sales based valuation story.
- The stock’s 26.1% decline over three years raises the question of what investors are currently paying for each dollar of Rivian’s sales and how much future revenue growth is already assumed in the price.
- Rivian’s reaffirmed outlook for future vehicle deliveries, combined with Amazon’s plan to roll out new safety technology across a large portion of its Rivian powered delivery fleet, can support expectations for how quickly sales may scale from here and how efficiently those volumes might translate into revenue.
- The analysts covering Rivian Automotive have run their own numbers. See what analysts think Rivian Automotive's shares could be worth.
The issue now is whether Rivian’s current share price is adequately supported by its sales, given its recent stock performance and these business developments.
If you are weighing Rivian Automotive against other possibilities and want a wider set of ideas, a focused stock screen can be a useful second starting point. In particular, you may want to consider something like 27 high quality undervalued stocks.
Does Rivian Automotive Look Pricey on Sales?
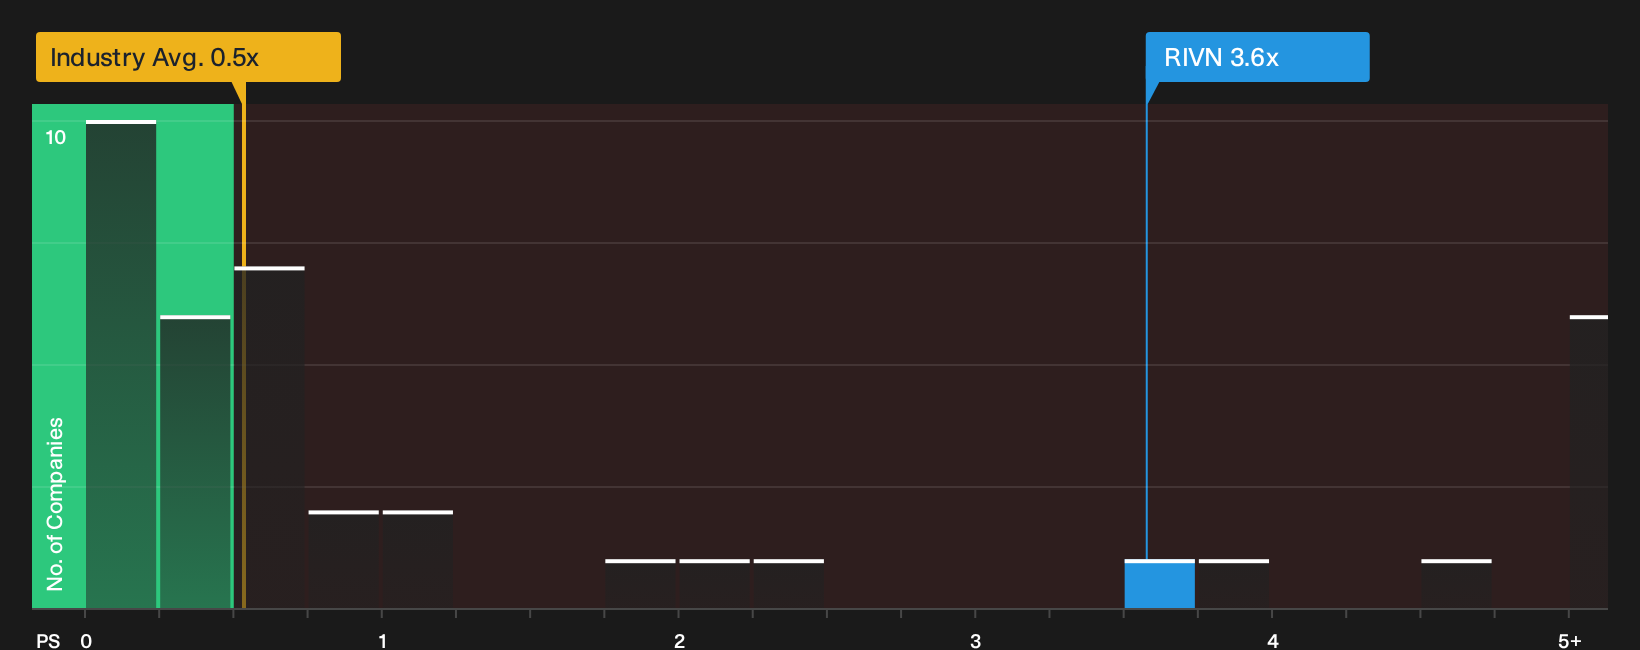
P/S suits Rivian Automotive because investors are still focused on revenue scale rather than profits. On this yardstick, the shares trade on about 3.6x P/S, compared with an Auto industry average near 0.5x and a peer group around 0.5x. That is a sizeable premium to what investors are paying for sales elsewhere in the sector.
Because the P/S that might be expected for Rivian, after adjusting for its growth profile, margins, size and risk, sits lower than the current 3.6x, the stock screens overvalued on this framework. Despite reaffirmed delivery guidance and Amazon’s plans to extend Rivian powered vans with added safety tech, the valuation still asks you to pay a higher multiple of revenue than the industry norm for that progress. Explore the numbers behind Rivian Automotive's P/S valuation.
The Rivian Automotive Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Rivian Automotive leaves off and explain what would need to happen to its future growth, margins and earnings for the shares to be worth materially more or less than today’s price. The Community page serves as the home base for those scenarios. Each narrative ties a fair value to a specific storyline about Rivian Automotive's potential catalysts and key risks so you can track over time which version seems closest to reality.
The Simply Wall St community is split on Rivian Automotive, with one camp seeing upside and another arguing the current tag already bakes in a lot of good news.
Bull case: 25% undervalued
"Vertical integration in technology especially in autonomy, battery, and software combined with growing software & services revenue is expected to open new high-margin revenue streams..."
Discover why this Narrative puts Rivian Automotive at 25% undervalued.
Bear case: 12% overvalued
"Even with over US$14b of existing and targeted liquidity from cash, public equity, loans, and partner funding, the combination of multi year capital expenditure for R2, the Georgia plant, autonomy hardware, and robotaxi commitments means Rivian Automotive could still need additional external capital if execution slips..."
Explore why this Narrative puts Rivian Automotive at 12% overvalued.
The share price is only one piece of the Rivian Automotive puzzle
What you pay today is just one side of the decision. Another lens comes from where professional forecasts suggest this business might be a few years from now, and how that lines up with the current tag. Explore where analysts expect Rivian Automotive to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com