
Marathon Petroleum (MPC) Gets A Diesel Tax Tailwind As Fair Value Questions Linger
Marathon Petroleum (MPC) moved back into focus after a new executive order deferred federal excise taxes on dyed diesel used on highways, creating fresh attention on the stock’s diesel exposure and refining earnings power.
Recent price action has been strong, with a 7 day share price return of 10.29% and a 90 day move of 54.04%, as investors react to Marathon Petroleum’s heavier diesel exposure, solid refining throughput updates, and regulatory headlines on excise tax relief. That momentum sits on top of a very large 5 year total shareholder return of about 6.5x, suggesting that the latest diesel tax decision is being interpreted as another supportive factor rather than a one off spike.
Spot other refiner plays that could echo Marathon Petroleum’s momentum and tax tailwinds by scanning our hand picked 44 power grid technology and infrastructure stocks.After a move that took Marathon Petroleum up more than 50% in 90 days and left the share price above the average analyst target, the real puzzle now is whether valuation still leaves meaningful upside or mostly reflects the story already.
Most Popular Narrative: 15% Overvalued
Marathon Petroleum last closed at $432.36, while the most followed narrative pegs fair value at $375.50. The current price already leans ahead of that assessment and puts more pressure on future execution to justify the premium.
The numbers suggest that a fairly valued, bearish view on Marathon Petroleum already reflects strong refining margins, substantial cash returns, and continued MPLX growth. This limits the potential upside for the share price if conditions simply remain where they are.
See why 64 investors see Marathon Petroleum as 15% overvalued.
Result: Fair Value of $375.50 (OVERVALUED)
Still, a U.S. diesel export ban or tighter rules on foreign flagged vessels in Marathon Petroleum’s logistics chain could quickly challenge today’s earnings and valuation narrative.
Find out about the key risks to this Marathon Petroleum narrative.
Another View: Marathon Petroleum Through A Cash Flow Lens
While the analyst narrative pegs Marathon Petroleum at a fair value of $375.50 and flags the stock as overvalued, the SWS DCF model points in the opposite direction. On that framework, MPC at $432.36 trades at roughly a 26% discount to an estimated future cash flow value of $582.93. These are two very different answers. Which one matches how you think the diesel cycle and refinery cash generation will actually play out?
Look into how the SWS DCF model arrives at its fair value.
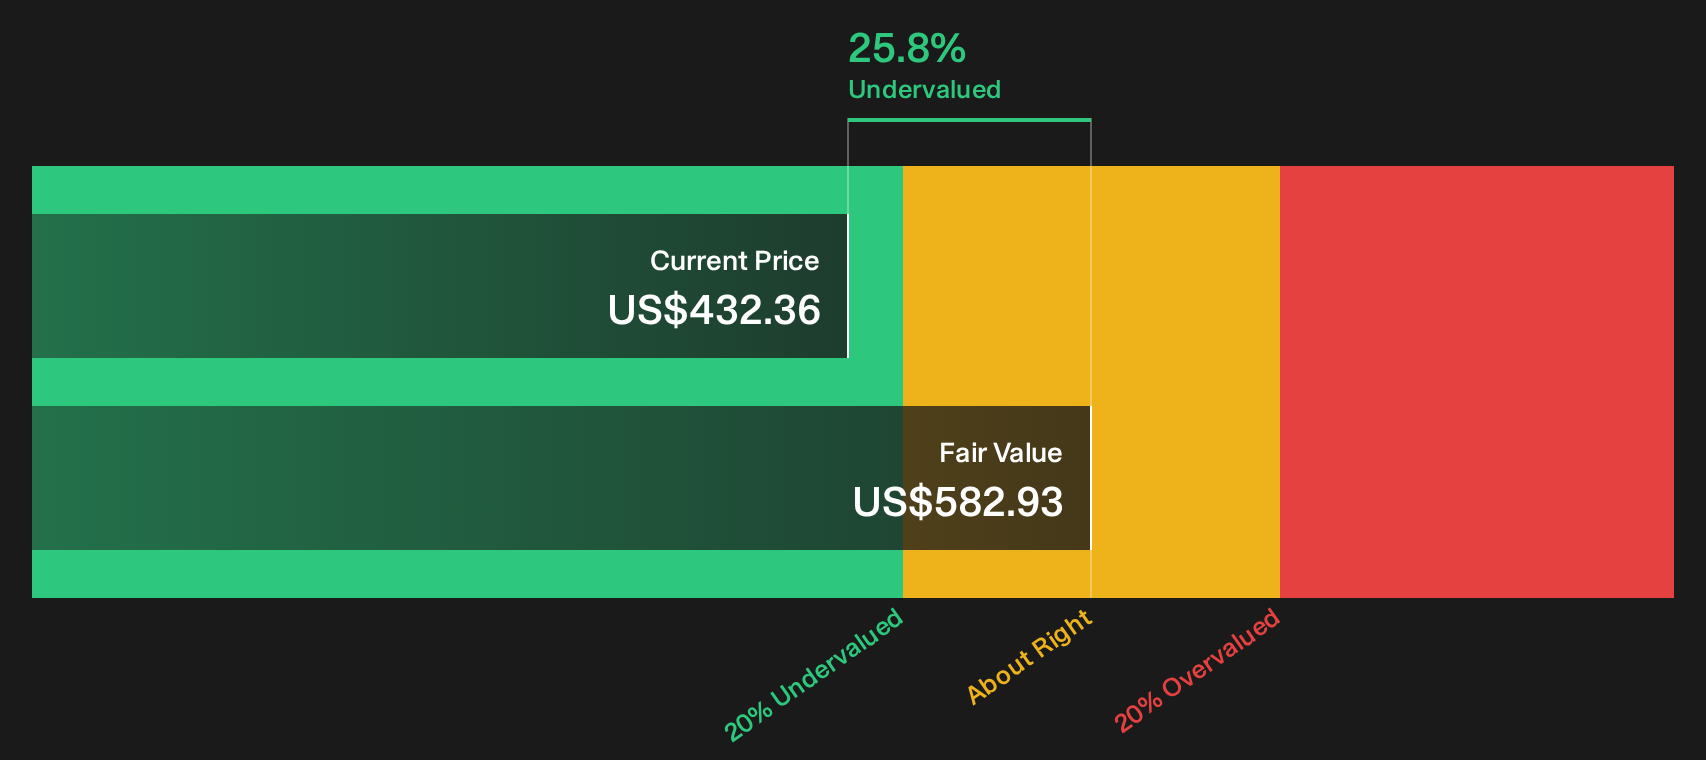
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Marathon Petroleum for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Marathon Petroleum is split, with some investors focused on opportunities and others zeroing in on pressure points, so move fast and weigh the full picture for yourself with 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Marathon Petroleum?
Do not stop with Marathon Petroleum. Fresh opportunities keep surfacing, and a few targeted screeners can help you spot them before the crowd moves in.
- Zero in on potential value opportunities by scanning our hand picked 27 high quality undervalued stocks with cleaner balance sheets and stronger cash generation profiles.
- Strengthen your income stream by reviewing 8 dividend fortresses that combine higher yields with more resilient payout histories.
- Dial down portfolio risk by focusing on 31 resilient stocks with low risk scores that score better on financial health and volatility controls.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com