
Why Canadian Utilities (TSX:CU) Is Getting Attention Today
Emera Incorporated has agreed to acquire a 47.6% stake in Canadian Utilities (TSX:CU) from shareholders other than ATCO in a merger of equals valued at approximately CA$6.8b.
Canadian Utilities has seen its share price slip over the past quarter, with a 90 day share price return of -5.19% and a softer 30 day move, even though the year to date share price return of 17.32% and a 1 year total shareholder return of 34.53% point to momentum that has been building over a longer stretch.
Scan how Canadian Utilities fits into the wider power and infrastructure story by weighing it against 44 power grid technology and infrastructure stocks riding similar M&A and grid investment themes.
After a year where Canadian Utilities has quietly stacked up strong total returns, the Emera deal now pins a clear reference value to the shares. Does it still make sense to buy in today or to wait for a cheaper entry as the merger process plays out and sentiment shifts around the implied exchange terms?
Most Popular Narrative: 8% Undervalued
At a last close of CA$50.20 against a narrative fair value of CA$54.71, Canadian Utilities is framed as modestly mispriced, with that gap resting heavily on how its capital projects and regulation interact over time.
Substantial investment in grid modernization and expansion, including major projects like the Central East Transfer-Out and 90%-contracted Yellowhead pipeline, positions Canadian Utilities to capitalize on rising power and gas demand from electrification and industrial growth, supporting future increases in rate base and long-term revenue growth.
See why 40 investors see Canadian Utilities as 8% undervalued.
The most followed narrative uses a 6.35% discount rate and ties that to expected earnings of CA$1.1b by about July 2029, alongside a P/E multiple of 16.4x on those projected profits. That set of assumptions underpins the CA$54.71 fair value mark and helps explain why the narrative currently treats the shares as undervalued relative to the recent CA$50.20 trading level.
Result: Fair Value of CA$54.71 (UNDERVALUED)
Still, regulatory disputes in Alberta and the heavy capital required for projects like Yellowhead could pressure Canadian Utilities if cost recovery or funding terms disappoint.
Find out about the key risks to this Canadian Utilities narrative.
Another View: What Multiples Say About Canadian Utilities
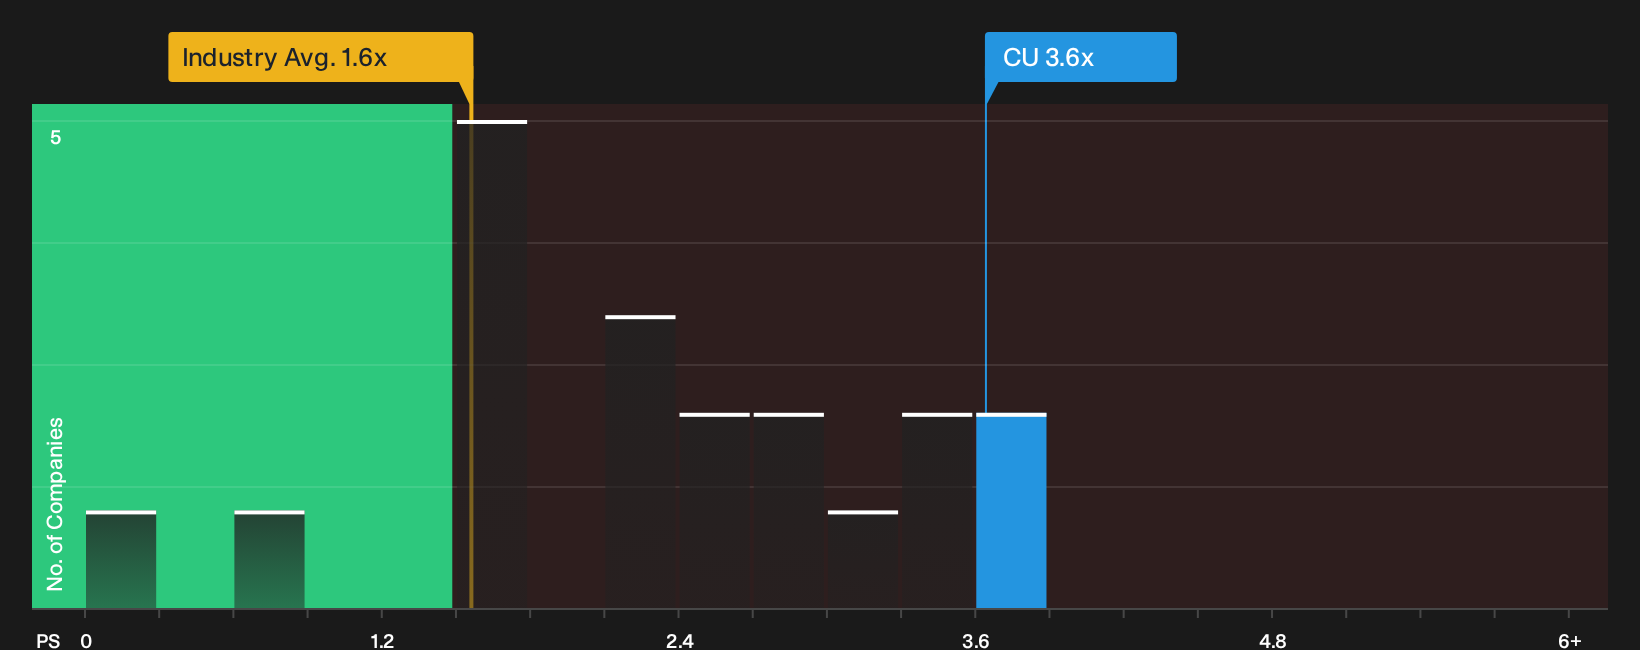
The cash flow narrative paints Canadian Utilities as undervalued, yet the simple sales-based yardstick sends a different message. At a P/S of 3.6x against a global integrated utilities average of 1.5x and a fair ratio of 2.7x, the stock screens as expensive. Which signal should carry more weight for you?
See what the numbers say about this price in our valuation breakdown, then compare it with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Canadian Utilities and the Emera deal make this a judgment call, so move fast on your own research and weigh both sides by checking the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Canadian Utilities?
If the Emera and Canadian Utilities story has sharpened your focus on regulated assets and cash flow resilience, cast the net wider with a few targeted screens.
- Spot potential mispricing opportunities early by scanning companies flagged as high quality yet out of favour through the 7 high quality undervalued stocks.
- Dial back portfolio risk by focusing on businesses that pair sturdy finances with measured volatility using the 8 resilient stocks with low risk scores.
- Get ahead of the crowd by reviewing financially sound smaller companies that the market has not fully paid attention to via the 8 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com