
3 US Tech Stocks Offering Broader AI Infrastructure Exposure Beyond Mega Caps
AI enthusiasm now sits at the center of S&P 500 earnings forecasts, with a handful of giants carrying much of the profit story. That concentration creates both excitement and discomfort for anyone who does not want a portfolio tied to just a few mega-caps. This piece looks at how that tension spills over into less crowded US low mega-cap ideas and highlights three stocks from our screener that appear positively exposed to the current AI-driven narrative.
The three stocks below are only a small sample of what fits this theme, and the full screen surfaced 11 more companies with equally compelling stories that are not covered here. If you want to go beyond the headline ideas, head straight into the US Low-Mega-Cap Diversified Equity Strategies screener to analyze, filter, and identify the diversified low mega-cap exposures that best match your own playbook.
TD SYNNEX (SNX)
Overview: TD SYNNEX is a global IT distributor and solutions aggregator that connects enterprise customers to a wide range of hardware, software, cloud, and AI services across many vendors.
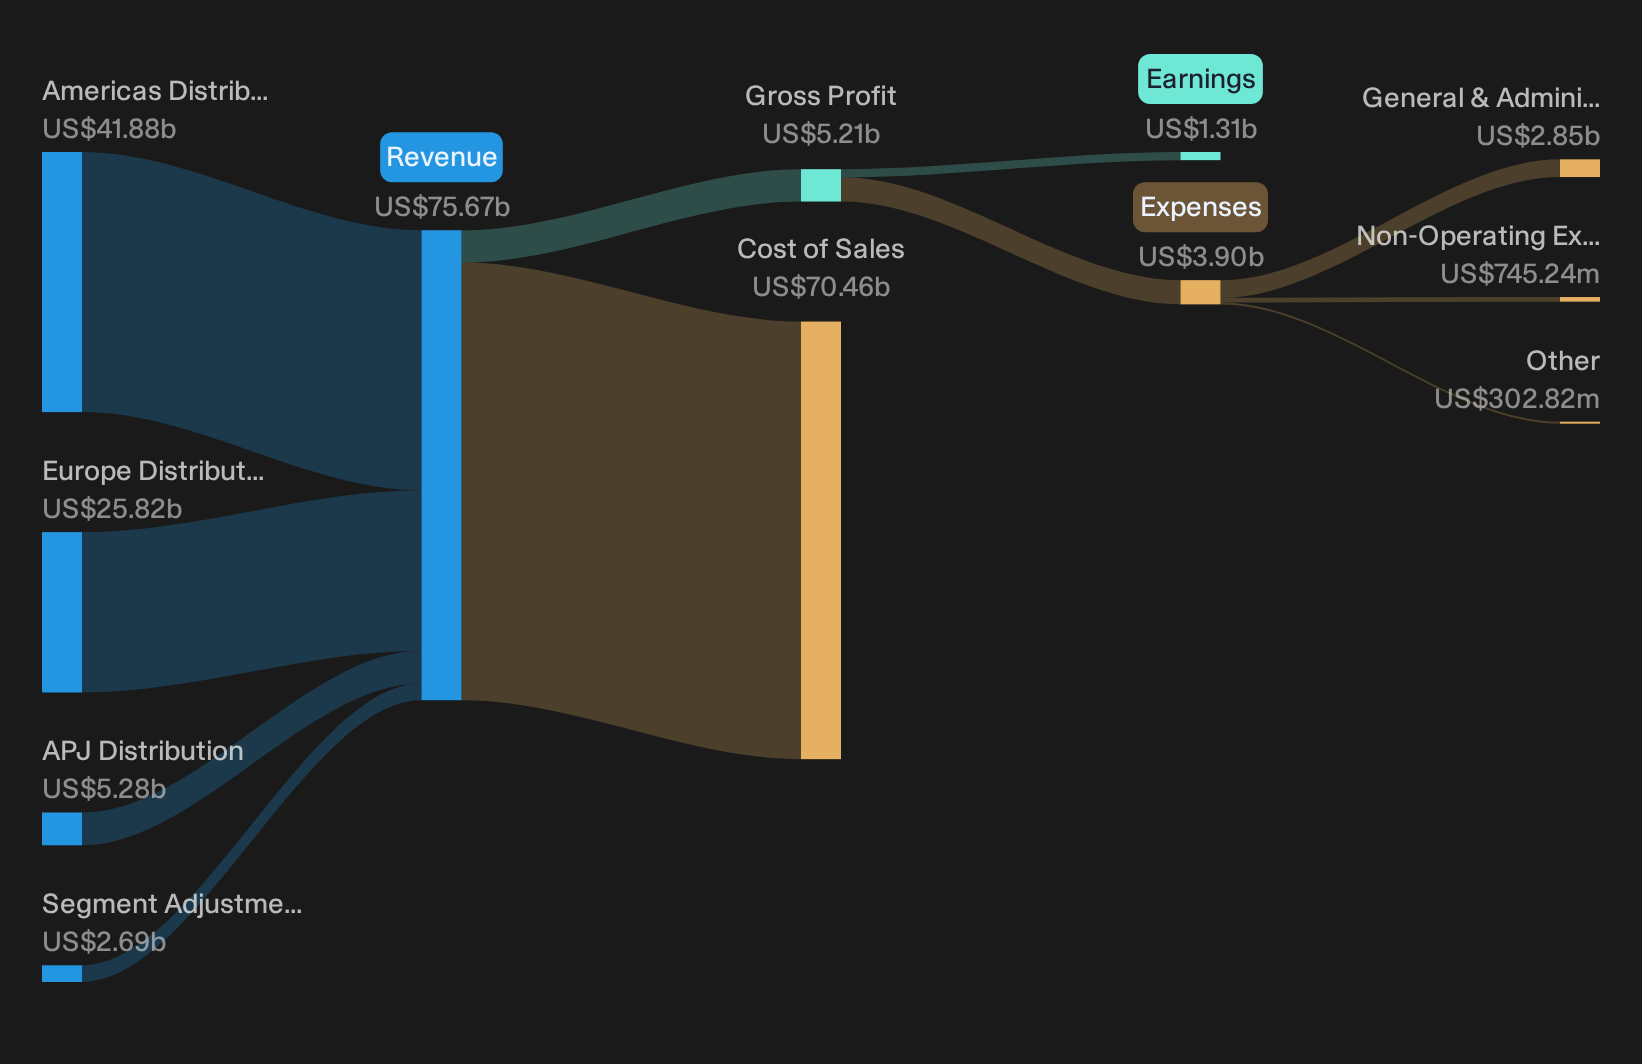
Operations: TD SYNNEX generates about US$41.9b from Americas Distribution, US$25.8b from Europe Distribution, and US$5.3b from APJ Distribution, with segment adjustments of US$2.7b.
Market Cap: US$22.1b
TD SYNNEX fits this low mega-cap diversification theme by giving you broad exposure to enterprise tech and AI infrastructure without concentrating everything in a single hardware or semiconductor champion.
"Ongoing data center build-outs and the proliferation of hybrid/cloud IT infrastructure, as evidenced by high growth in the Advanced Solutions and Hyve businesses, are increasing demand for complex integration and lifecycle services, which support improved net margins via higher-value offerings."
What ultimately matters for TD SYNNEX is how one pressure on the balance between AI-driven demand and funding risk shapes those margin ambitions.
That margin question is exactly what the full narrative for TD SYNNEX unpacks, tracing where TD SYNNEX’s AI exposure could accelerate returns and where funding risk might still be masking pressure.
Jabil (JBL)
Overview: Jabil provides design, engineering, manufacturing, and supply chain services across electronics, healthcare, automotive, cloud, and connected devices for global clients.
Market Cap: US$31.5b
Jabil fits the US Low-Mega-Cap Diversified Equity Strategies theme because its contract manufacturing model spreads AI-related demand across many sectors instead of tying your exposure to a single mega-cap chip or platform stock.
"Jabil's acquisition of Pharmaceutics International, Inc. opens access to a $20 billion market, suggesting potential revenue growth and improved margins by expanding its pharmaceutical solutions offering."
The real swing factor for Jabil is how one underappreciated cost pressure ultimately shapes the margin profile investors are counting on.
That margin swing hinges on how Jabil handles that cost pressure, and the full narrative for Jabil maps where earnings power could be accelerating or quietly capped.

Avnet (AVT)
Overview: Avnet distributes electronic components and embedded solutions worldwide, connecting suppliers with diversified customers across industrial, medical, telecom, and automation markets.
Operations: Avnet generates about US$25.9b from Electronic Components and US$1.8b from Farnell, with revenue spread across the United States, Taiwan, China, and other global hubs.
Market Cap: US$8.7b
Avnet fits the US Low-Mega-Cap Diversified Equity Strategies theme as a way to stay tied into AI hardware demand while spreading risk across many suppliers, customers, and regions rather than any single mega-cap story.
"Recovery in global demand led by growth in Asia and improving bookings and backlog across regions remains in focus, with management now pointing to tight supply, extended lead times in more than 50% of product categories and book to bill ratios above 1.0, which together point to potential support for Avnet revenue and order visibility."
The key consideration for the Avnet narrative now is how one mix shift in that demand cycle ultimately feeds through to margins and cash generation.
That mix shift is exactly what the full narrative for Avnet unpacks, separating accelerating AI demand from the risks that could quietly stall Avnet’s cash engine.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the next breakout ideas rarely stay under the radar for long. Identify fresh momentum plays before the crowd, while the data still matters, and consider them early in your process.
- Spot income workhorses early and review the 8 dividend fortresses before yields are influenced by more investors seeking dependable cash streams.
- Track the next infrastructure backbone and scan the 92 AI infrastructure stocks while these potential enablers of AI demand are still priced like supporting players.
- Monitor the trend toward smarter grids and use the 44 power grid technology and infrastructure stocks while these potential grid upgrade beneficiaries remain relatively overlooked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com