
Asian Growth Companies With High Insider Ownership To Watch
As Asian markets navigate a landscape marked by fluctuating economic indicators and evolving policy measures, investors are increasingly focused on identifying growth opportunities within the region. In such an environment, companies with high insider ownership can be particularly appealing as they often signal strong alignment between management and shareholder interests, making them noteworthy candidates for those seeking to capitalize on growth potential.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 106.6% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Fulin Precision (SZSE:300432) | 10.8% | 66.5% |
We'll examine a selection from our screener results.
Trigiant Group (SEHK:1300)
Simply Wall St Growth Rating: ★★★★★★
Overview: Trigiant Group Limited is an investment holding company that manufactures and sells feeder cables, optical fiber cables, flame-retardant flexible cables, and other accessories for mobile communications and telecommunication equipment in China, with a market cap of HK$5.83 billion.
Operations: The company's revenue segments include CN¥1.12 billion from feeder cable series, CN¥170.11 million from new-type electronic components, CN¥1.48 billion from flame-retardant flexible cable series, and CN¥465.76 million from optical fiber cable series and related products.
Insider Ownership: 29.6%
Earnings Growth Forecast: 68% p.a.
Trigiant Group Limited, with substantial insider ownership, has reported strong financial performance for the first half of 2026, including a significant increase in net income to CNY 208.45 million. The company's revenue and earnings are forecast to grow substantially faster than the Hong Kong market averages. Despite recent share price volatility, Trigiant is trading below its estimated fair value and maintains a high return on equity forecast. Strategic investments in AI Data Centres could drive future growth further.
- Click here and access our complete growth analysis report to understand the dynamics of Trigiant Group.
- Insights from our recent valuation report point to the potential undervaluation of Trigiant Group shares in the market.
Kotobuki Spirits (TSE:2222)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Kotobuki Spirits Co., Ltd. is a Japanese company that produces and sells sweets, with a market capitalization of approximately ¥390.10 billion.
Operations: The company's revenue is primarily derived from its Shukrei segment at ¥37.60 billion, followed by KCC at ¥23.67 billion, Kotobukiseika Group at ¥16.77 billion, and Sales Subsidiaries contributing ¥7.98 billion.
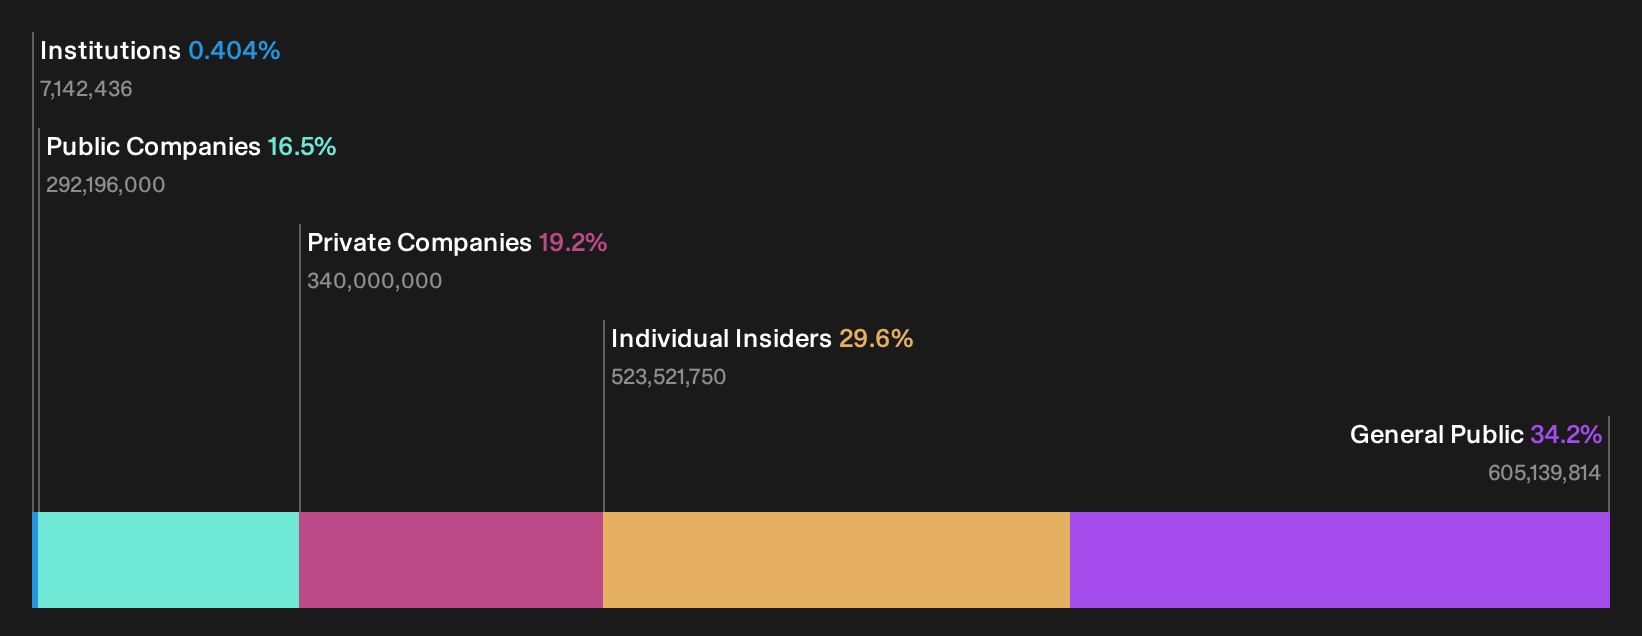
Insider Ownership: 29.5%
Earnings Growth Forecast: 13.4% p.a.
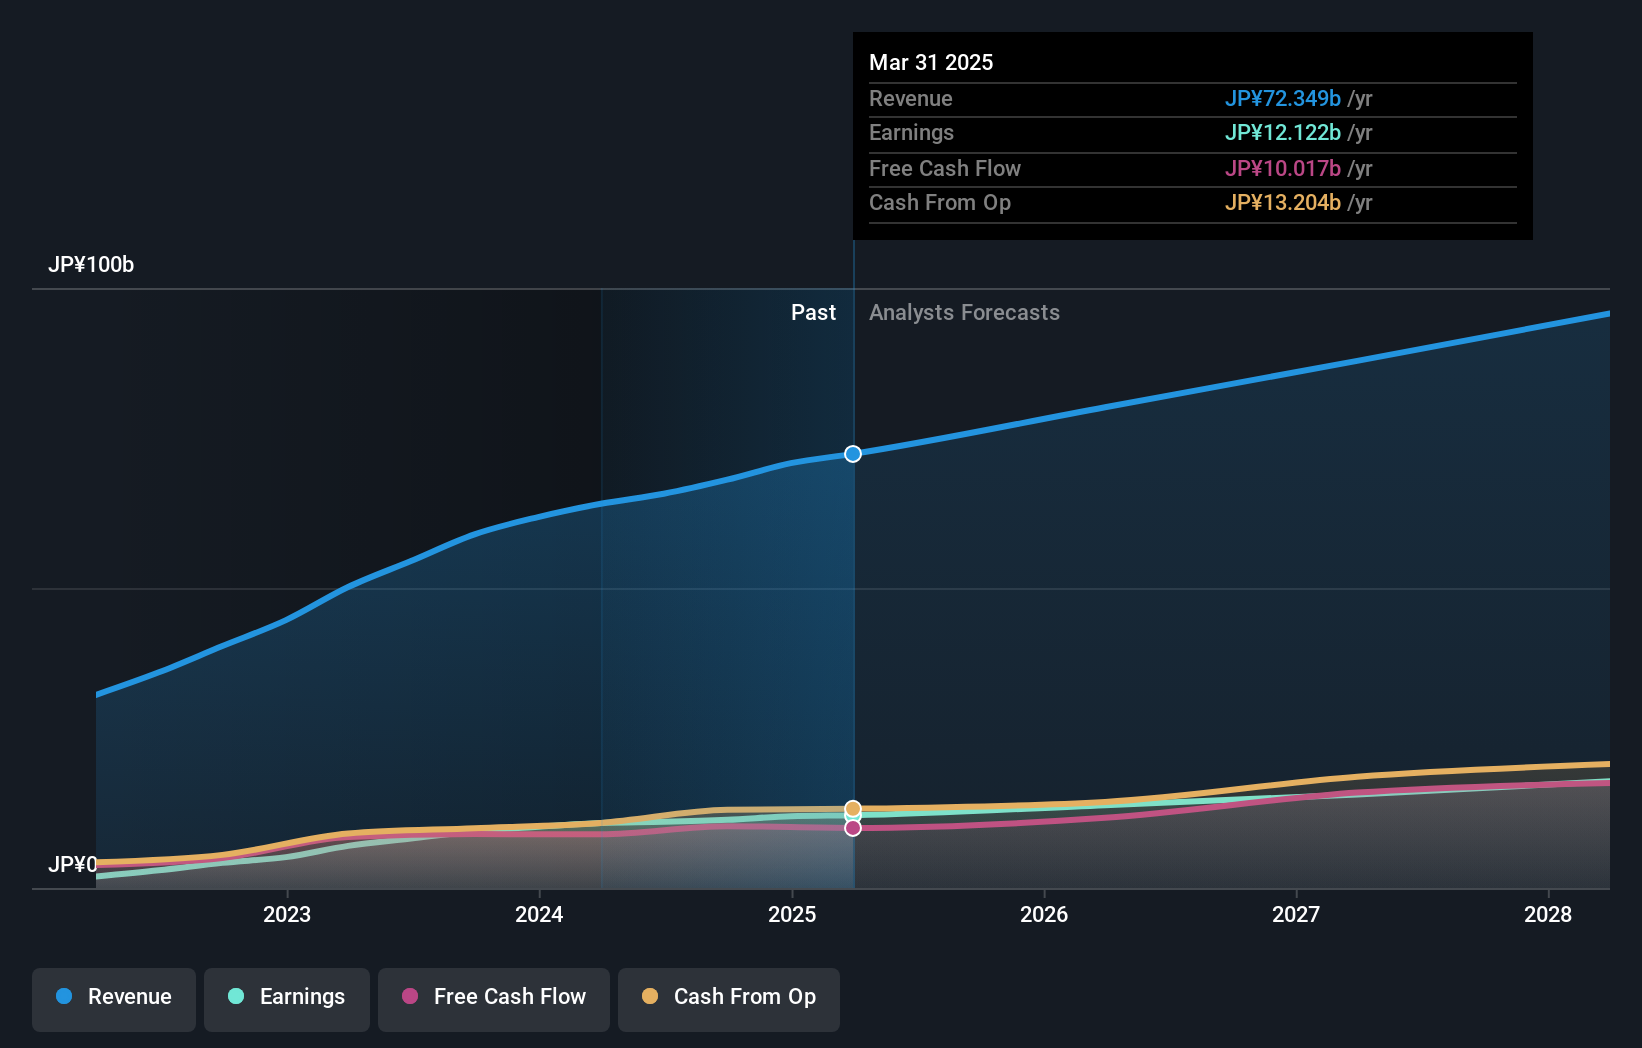
Kotobuki Spirits, with high insider ownership, shows promising growth prospects. Its earnings are projected to grow faster than the Japanese market average at 13.4% annually, while revenue is expected to rise by 8.4% per year. Trading below its estimated fair value and with a strong return on equity forecast of 26.2%, it offers potential upside as analysts agree on a price increase of 22.7%. Recent changes in dividend policy aim to enhance shareholder returns through more frequent payouts.
- Dive into the specifics of Kotobuki Spirits here with our thorough growth forecast report.
- According our valuation report, there's an indication that Kotobuki Spirits' share price might be on the cheaper side.
Quanta Computer (TWSE:2382)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Quanta Computer Inc. is engaged in the manufacturing, processing, and sale of laptop computers and cloud-computing server-related products across the United States, Mainland China, the Netherlands, Japan, and other international markets with a market cap of approximately NT$1.29 trillion.
Operations: The company generates revenue primarily from its Electronics Sector, which amounts to NT$6.20 billion.
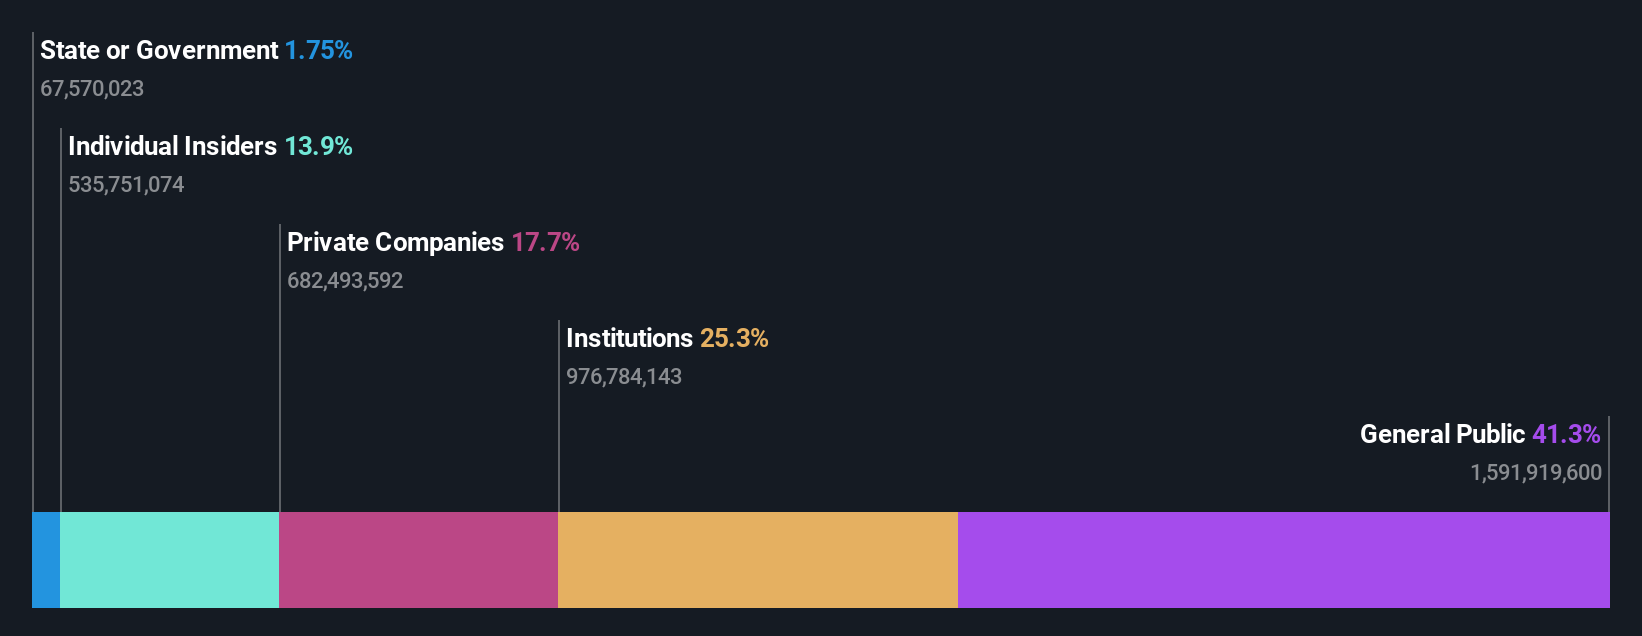
Insider Ownership: 13.9%
Earnings Growth Forecast: 18.6% p.a.
Quanta Computer, despite recent index exclusions, maintains strong growth prospects with high insider ownership. Revenue is forecast to grow at 28.9% annually, outpacing the Taiwan market average. A recent licensing agreement with Lumus Ltd. enhances its AR capabilities, potentially boosting future revenues. Although its earnings growth of 18.6% per year lags behind the market's 25.8%, Quanta trades below fair value and boasts a very high expected return on equity of 41.4%.
- Delve into the full analysis future growth report here for a deeper understanding of Quanta Computer.
- Upon reviewing our latest valuation report, Quanta Computer's share price might be too pessimistic.
Where To Now?
- Click this link to deep-dive into the 495 companies within our Fast Growing Asian Companies With High Insider Ownership screener.
- Seeking Other Investments? Outshine the giants: these 19 early-stage AI stocks could fund your retirement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com