
Telix Pharmaceuticals (ASX:TLX) Could Be 35% Below Fair Value On Pixclara Launch
Telix Pharmaceuticals (ASX:TLX) has begun dosing the first patients in the U.S. with Pixclara, its FDA-approved PET imaging agent for glioma, marking the commercial roll out of this brain cancer diagnostic.
That Pixclara milestone comes after a busy few weeks for Telix Pharmaceuticals, including FDA Fast Track status for its BiPASS prostate cancer imaging program. The share price now trades at A$15.87 with a year to date share price return of 39.7% and a 5 year total shareholder return of 181.88%, suggesting strong long term momentum despite some recent weakness over the past quarter.
Scan beyond Telix Pharmaceuticals and evaluate other healthcare-focused opportunities using our hand picked screener of 8 healthcare AI stocks that are aiming to turn advanced diagnostics into commercial traction.
After a 39.7% gain this year and a 5 year total shareholder return above 180%, is Telix Pharmaceuticals still offering meaningful upside, or has most of the easy money already been made once valuation is factored in?
Most Popular Narrative: 35% Undervalued
On the most followed valuation narrative, Telix Pharmaceuticals screens at a fair value of A$24.51 versus the current A$15.87. This puts a lot of weight on how its radiopharmaceutical platform and manufacturing footprint develop from here.
Vertical integration in radiopharmaceutical manufacturing and last mile distribution through RLS, ARTMS, Iso Therapeutics and other TMS sites, including planned cyclotron deployment, which can reduce reliance on third parties and over time may support gross margins and supply reliability, both key inputs to sustainable earnings.
See why 28 investors see Telix Pharmaceuticals as 35% undervalued.
Result: Fair Value of A$24.51 (UNDERVALUED)
Still, Telix Pharmaceuticals faces execution and regulatory overhangs. The SEC subpoena and lower margin TMS operations are both capable of undermining the current 35% undervaluation narrative.
Find out about the key risks to this Telix Pharmaceuticals narrative.
Another View: Telix Pharmaceuticals On Earnings Multiples
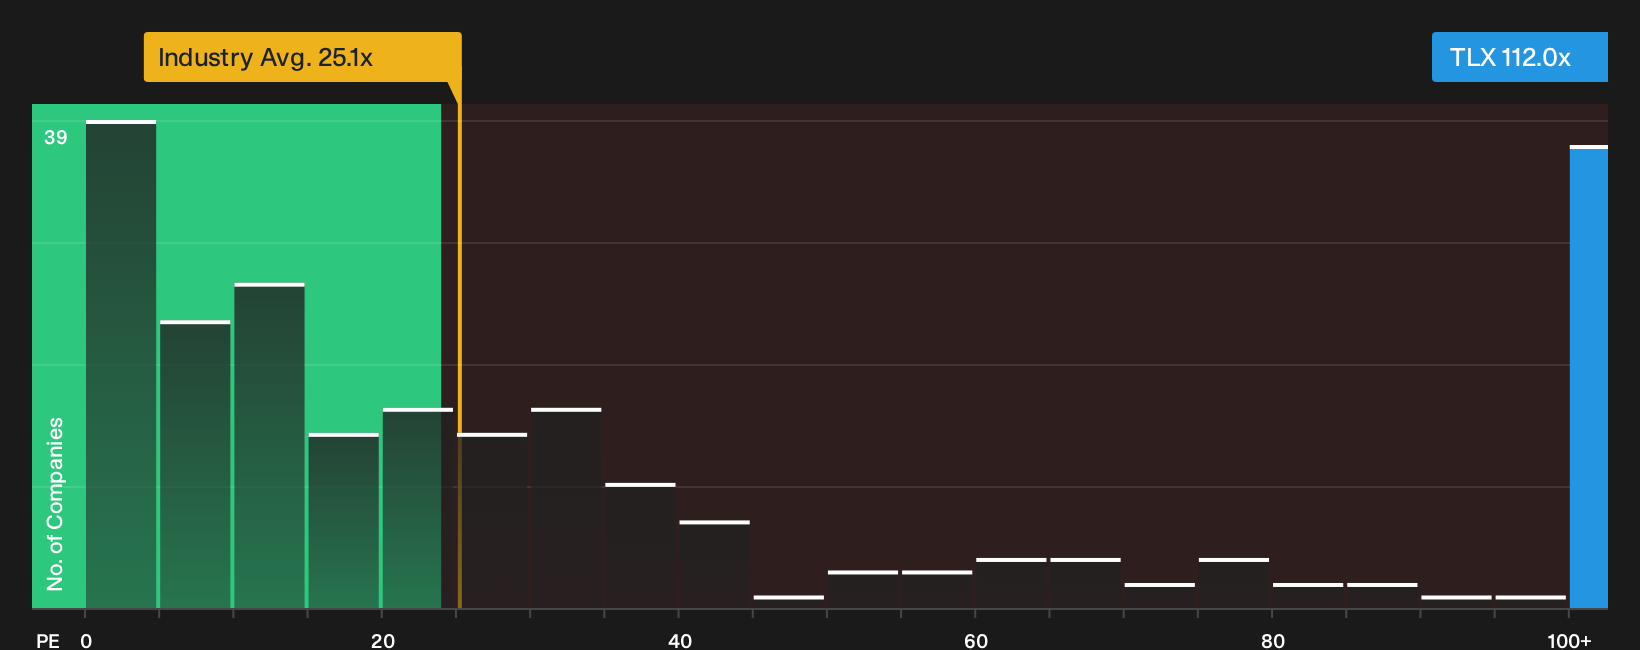
There is a catch. While the SWS fair value points to upside, Telix Pharmaceuticals trades on a P/E of 112x versus an estimated fair ratio of 51.2x, and peer averages closer to 25x to 27x. That is a rich earnings multiple. Is the current price already baking in a lot of the story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Telix Pharmaceuticals feels familiar, that is the point: investors are weighing real upside against real risk. Move quickly, test the numbers for yourself, then pressure-test both the bullish and cautious angles using our breakdown of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Telix Pharmaceuticals?
If Telix Pharmaceuticals has sharpened your focus, do not stop there. Broader context across other companies can tighten your process and reveal fresh ideas.
- Target quality at a discount by scanning our hand picked universe of 5 high quality undervalued stocks that pair strong fundamentals with pricing that may not fully reflect them.
- Prioritise resilience and sleep a little easier by checking companies in the 7 resilient stocks with low risk scores that our scoring flags as having sturdier profiles.
- Spot potential future leaders before the crowd catches on by reviewing the 15 high quality undiscovered gems with solid underlying numbers but limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com