
Camtek (CAMT) Stock Looks Above Fair Value After A 305% Run
Camtek has delivered strong share-price gains in recent years, which puts a sharper spotlight on whether the current US$154.55 level is well grounded in its sales. With that kind of move already on the board, investors are asking how much of the business performance is already reflected in the valuation.
- The stock has returned 304.9% over the past 5 years, which raises the question of how fully those gains already reflect Camtek's revenue power.
- The company’s focus on inspection and metrology tools ties its prospects closely to semiconductor production trends, so expectations for future sales may be playing an increasingly important role in how the market is pricing the shares.
- There is a second opinion on Camtek worth weighing. See what analysts think Camtek's shares could be worth.
For investors, the debate is whether Camtek’s current share price is adequately supported by its sales today and the revenue that the business may be able to generate over time.
If you are weighing whether Camtek's 304.9% five year return is fully captured in its current P/S level, it can help to compare it with a wider set of 92 AI infrastructure stocks.
Does Camtek Look Pricey on Sales?
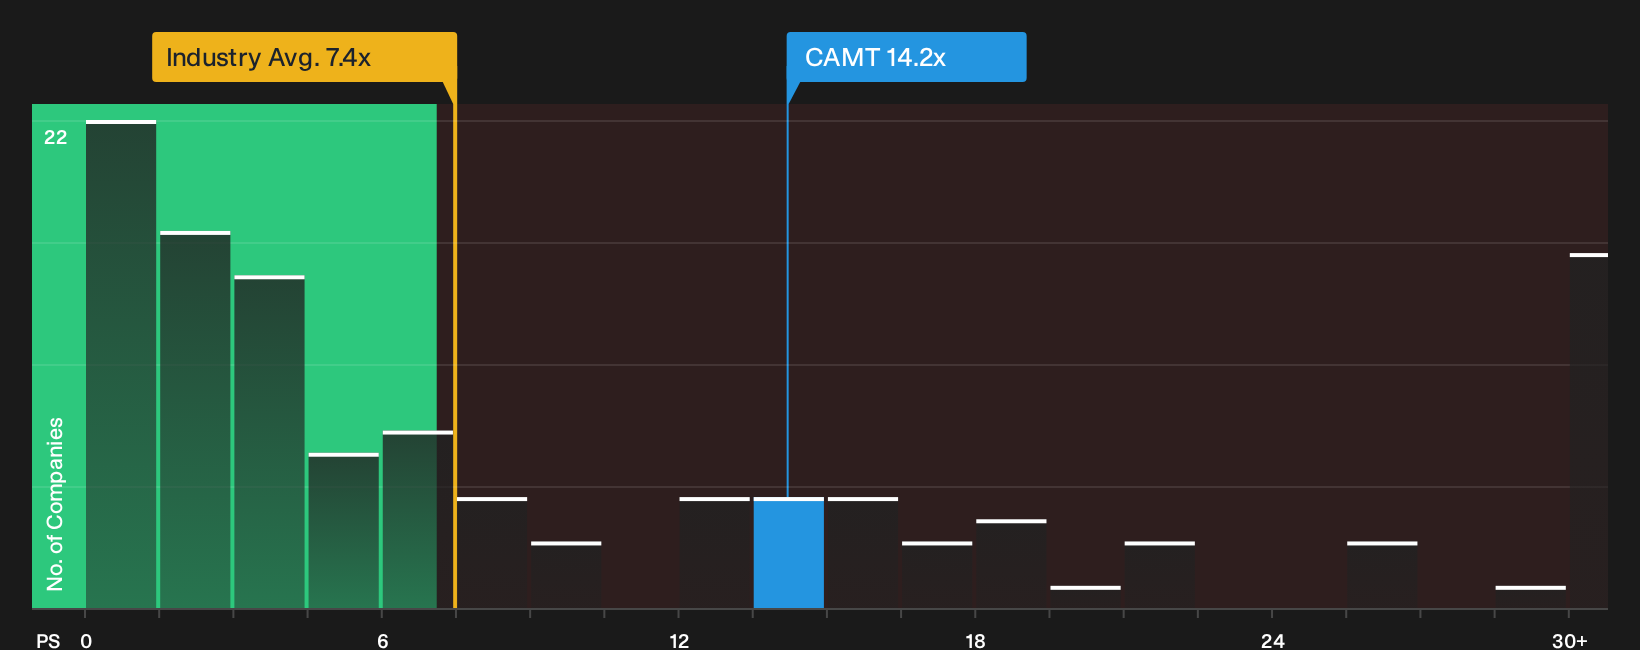
P/S is a clean fit for Camtek because revenue is a key reference point for how investors frame semiconductor equipment makers. At around 14.2x sales, Camtek trades below the peer group average of roughly 18.4x, yet it also sits well above the broader semiconductor industry’s P/S of about 7.4x. That mix indicates the market is giving the stock a stronger revenue tag than the typical chip stock, but not the highest multiple in its more focused peer set.
The fair P/S level implied by the valuation work, which blends Camtek’s growth profile, profitability, sector and risk into one reference point, comes in below the current 14.2x reading. That gap suggests the shares screen as overvalued on this framework, even with the discount to some peers, so an investor would need to be confident that the business can justify a richer sales tag over time for this pricing to feel comfortable. Explore the numbers behind Camtek's P/S valuation.
The Camtek Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Camtek valuation puzzle leaves off and explain which combinations of growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than today’s price. Each narrative links a fair value estimate to a specific mix of potential catalysts and risks so you can track over time which version of Camtek's story appears to be unfolding on the Community page.
Camtek draws two quite different readings from the community, with one group seeing more upside left while the other thinks expectations already run high.
Bull case: 15% undervalued
"Accelerating AI and high performance computing demand is feeding through to advanced packaging and HBM orders for Camtek, with roughly 80% of more than US$600 million of 2026 year to date orders tied to these applications..."
Discover why this Narrative puts Camtek at 15% undervalued.
Bear case: roughly fairly valued
"External reports that Camtek’s share price is trading 20 to 100% above some intrinsic value estimates with no recent insider buying point to expectations that current AI driven growth, margin targets and addressable market expansion will all be met..."
Explore why this Narrative puts Camtek at roughly fairly valued.
Before you focus on Camtek’s price tag, check what the red flags are saying
Camtek’s valuation story is only half the picture, because Simply Wall St’s checks have also highlighted specific areas of concern that some investors may want to review in detail before making a move. Take a closer look at 3 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com