
Centene (CNC) Stock Trades Below Fair Value After A 69% Run
Centene has had a strong run over the past year, which naturally puts the focus on whether the current share price lines up with what its sales can support. With fresh news around its role in a national credentialing program, the key issue for you is how much revenue power the market is now assuming.
- The stock has returned 69.0% over the past year, which raises the question of how much sales strength is already reflected in today's valuation.
- Centene's participation in CertifyOS's National Shared Credentialing Program with UnitedHealthcare and Cigna Healthcare may support expectations for more efficient operations and potentially steadier revenue from its relationships with healthcare providers.
- There is a second opinion on Centene worth weighing. See what analysts think Centene's shares could be worth.
The issue now is whether Centene's current share price is justified by the scale and quality of its sales.
If you want to test the same sales driven valuation question beyond Centene, line it up against a curated set of 29 high quality undervalued stocks.
Is Centene Still Cheap on Sales?
P/S fits Centene because revenue is the main yardstick investors use for large managed care groups where margins can be slim but contract scale matters.
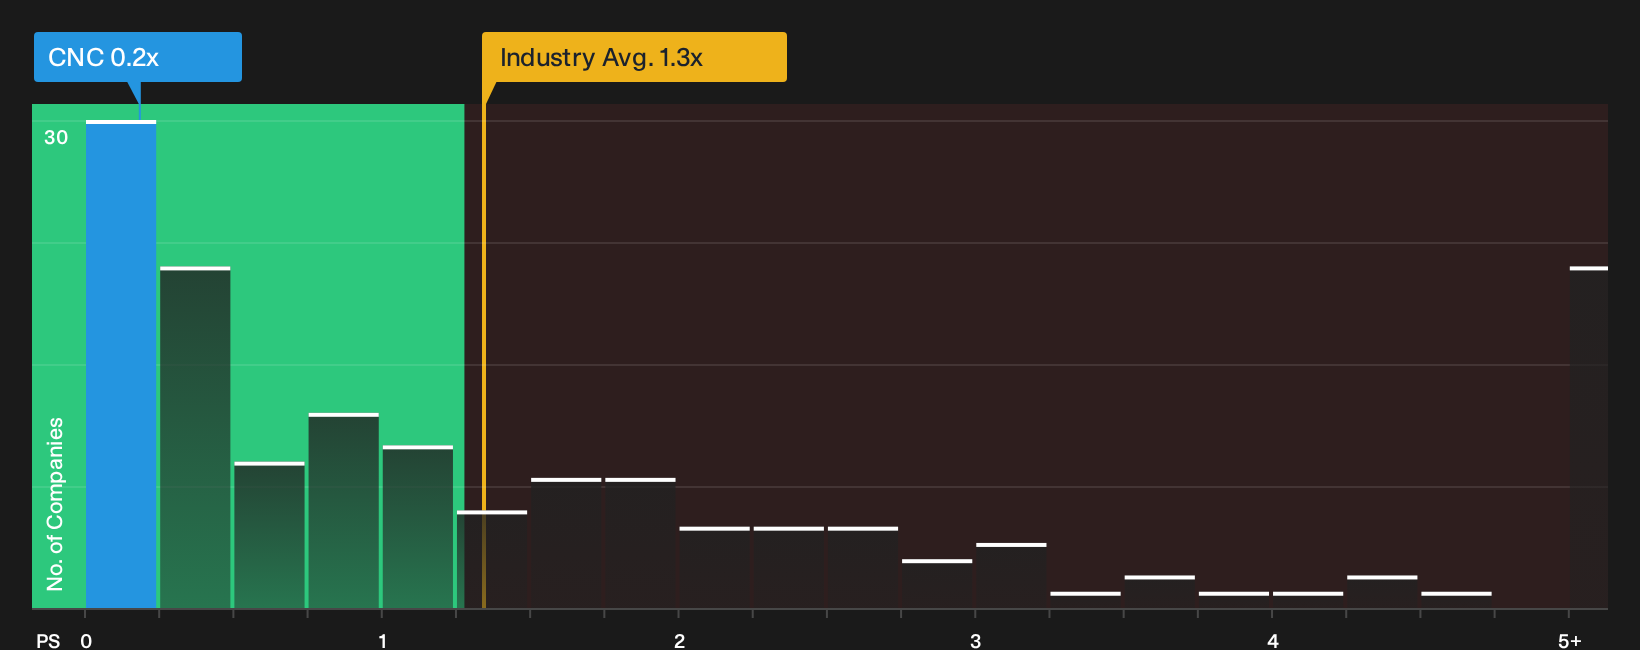
On that measure, Centene trades on a P/S of 0.2x, which is far below both the Healthcare industry average of 1.3x and the peer group average of 1.6x. Because the CertifyOS credentialing deal points to potential efficiency gains with providers, the current multiple suggests the market is still pricing the stock at a discount to broad sector expectations. The in house fair multiple model, which blends Centene's growth outlook, profitability profile, size and risk, indicates a higher ratio than where the shares trade today, so the stock screens as undervalued on this framework. That gap is what the valuation link below is designed to quantify in more detail. Explore the numbers behind Centene's P/S valuation.
The Centene Narrative: What Would Justify Today's Price?
Narratives pick up where Centene's low P/S puzzle leaves off by spelling out what kind of future on growth, margins and earnings would need to play out for the shares to be worth significantly more or less than today on Simply Wall St's Community page. Instead of giving you just one output from a ratio or model, they lay out the underlying path that figure depends on, so you can see over time whether Centene's actual performance keeps matching that script.
Community views on Centene are split between those who see more earnings power being ignored and those who think the recent strength already prices that in.
Bull case: 24% undervalued
"The Marketplace book is evolving toward a higher acuity Silver membership mix with sizeable risk adjustment receivables, which opens the door for Centene to treat this segment as a capital light fee platform..."
Discover why this Narrative puts Centene at 24% undervalued.
Bear case: 16% overvalued
"The numbers suggest that Centene’s share price already reflects a fairly valued, bullish case in which current guidance on earnings, risk adjustment settlements, Medicaid rate yields and PDP profitability is largely delivered and sustained over time..."
Explore why this Narrative puts Centene at 16% overvalued.
One more Centene question before you decide what the valuation really means
Price ratios tell you what the market currently assumes, but the next piece is how professional analysts map out Centene's revenue and earnings a few years from now and then compare that to today's setup. Explore where analysts expect Centene to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com