
CareTrust REIT (CTRE) Stock Could Be Undervalued At Today’s Price
CareTrust REIT has delivered a strong run over the past several years, which puts fresh focus on what investors are paying for its earnings today. With the share price recently at US$35.82 after some shorter term pullbacks, the key issue is how that track record lines up with the income stream the real estate trust is generating.
- Over the last 5 years the stock has gained 120.2%, which raises the question of whether that kind of return still lines up with the earnings power investors now see in CareTrust REIT.
- The business depends on leased healthcare properties, so rent coverage, occupancy and the reliability of tenant payments can heavily influence how investors value its current and future earnings stream.
- There is a second opinion on CareTrust REIT worth weighing. See what analysts think CareTrust REIT's shares could be worth.
The stock's next move may depend on whether CareTrust REIT's current earnings justify the price investors are now asked to pay.
If you want to cross check how today's earnings question for CareTrust REIT compares with other opportunities, scan through 29 high quality undervalued stocks.
Does CareTrust REIT Look Undervalued on Earnings?
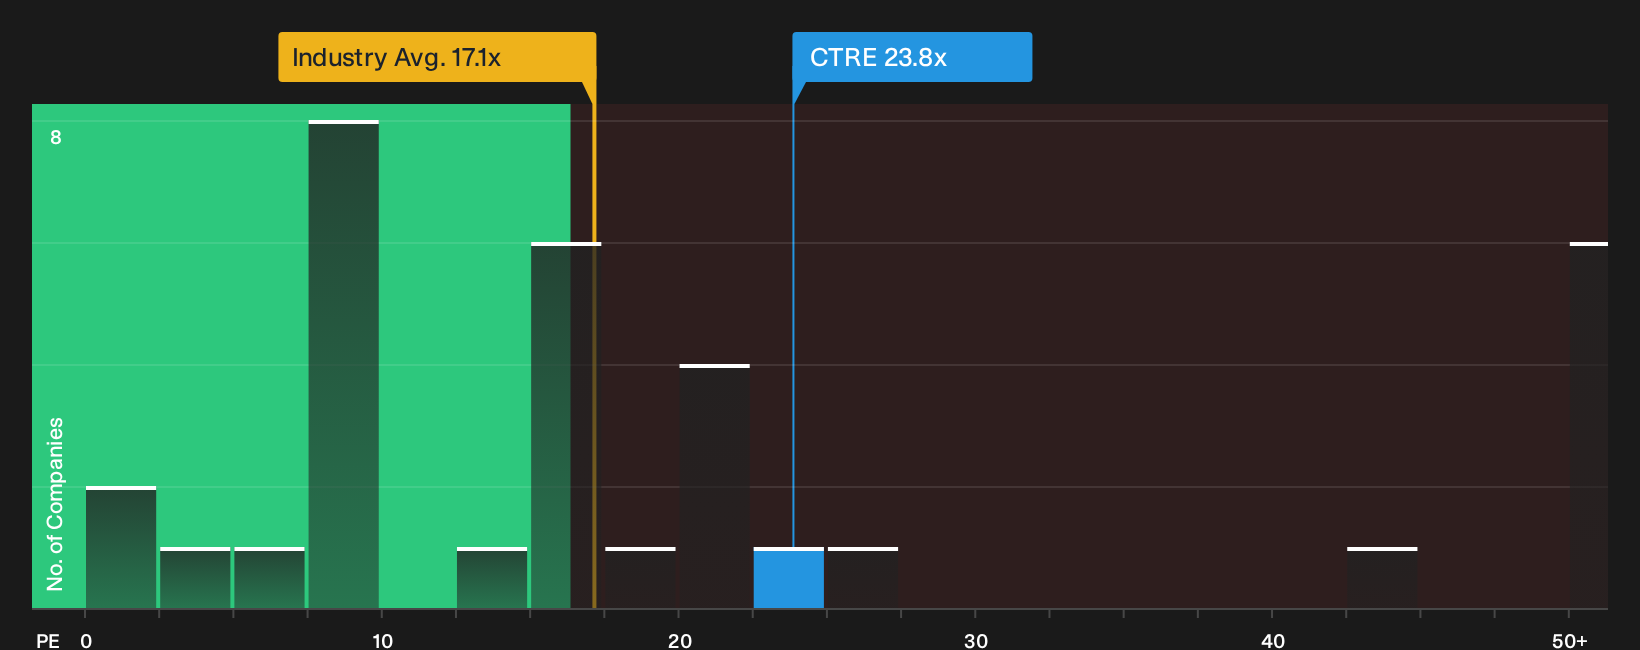
P/E fits CareTrust REIT because investors often focus on the earnings that support its dividend and acquisition pipeline. On this measure, the stock trades on about 23.8x earnings, compared with roughly 17.1x for the wider Health Care REITs group and a much higher 59.1x across its peer set. That mix indicates the shares are priced above the broad sector, but well below some of the more aggressively valued rivals.
The Fair Ratio model, which estimates the multiple you might expect given CareTrust REIT's sector, scale and risk profile, sits above the current P/E. That gap points to the shares screening as undervalued on this framework, even after the strong long term share price performance. For a holder or prospective buyer, the key question is whether the underlying earnings quality and rent coverage metrics justify the market paying closer to that higher implied multiple. Explore the numbers behind CareTrust REIT's P/E valuation.
The CareTrust REIT Narrative: What Would Justify Today's Price?
Narratives for CareTrust REIT pick up where the P/E discussion leaves off and map out which paths for rent coverage, margins and earnings would need to play out for the stock to look meaningfully cheaper or richer than it does today. Instead of a single output from one ratio or model, they unpack the future that number quietly assumes so you can watch how CareTrust REIT's actual performance lines up with that story over time on Simply Wall St's Community page.
One of the top community narratives on CareTrust REIT: 21% undervalued
"The main thing that has to go right is that CareTrust REIT continues to place capital with high quality operators and sustain current lease coverage…"
Discover why this Narrative puts CareTrust REIT at 21% undervalued.
One more angle on CareTrust REIT that is easy to miss
Current ratios only tell you what CareTrust REIT looks like today, while professional estimates for revenue, earnings and dividends over the next few years offer a separate benchmark to compare with the present share price. Explore where analysts expect CareTrust REIT to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com