
Onto Innovation (ONTO) Faces A Valuation Test Ahead Of Its December Analyst Meeting
Onto Innovation (ONTO) has set the date for its next major investor event, scheduling an analyst meeting at the New York Stock Exchange on 17 December 2026 to focus on market opportunities, products, and margins.
Recent trading has been choppy, with Onto Innovation’s share price down 2.97% over the last session and slightly lower over the past week, even after a 13.58% 1‑month share price gain and an 83.52% year to date share price return. The 1‑year total shareholder return of 118.80% signals strong longer term momentum, and the upcoming NYSE analyst meeting could either reinforce or test this as investors reassess growth potential and risk.
Scan beyond Onto Innovation and line up other potential semiconductor beneficiaries of this momentum shift using our hand picked 92 AI infrastructure stocks as a starting field of candidates.
After an 83.52% year-to-date share price return and a 118.80% 1-year total shareholder return, the question around Onto Innovation now shifts. Is meaningful upside still ahead, or has most of the easy move already happened as valuation stretches?
Most Popular Narrative: 20% Undervalued
The most followed narrative pegs Onto Innovation’s fair value at about $380 per share, well above the last close at $304.40. That gap has many investors asking whether the recent share price strength still reflects the full AI packaging story.
Onto Innovation is emerging as one of the most strategically important semiconductor equipment companies in the AI supply chain. While much investor attention remains focused on GPU manufacturers and memory suppliers, the next bottleneck increasingly lies in advanced packaging, the complex process of stacking, connecting, and inspecting AI chips and HBM memory at nanometer precision.
See why 38 investors see Onto Innovation as 20% undervalued.
According to FundamentalFlow, this valuation view leans heavily on advanced packaging exposure, the Dragonfly G5 qualification at TSMC, and leverage to HBM capacity investments. The narrative argues that these factors could shift how the market values Onto Innovation compared with more traditional semiconductor equipment peers.
That framing does not fully align with Simply Wall St’s own SWS DCF model, which currently places the future cash flow value near $286.50, below the present share price. The narrative fair value of about $380 instead reflects expectations for stronger revenue growth, forecast earnings expansion of roughly 49.8% a year, and higher future returns on equity than today’s 6.9% level.
Result: Fair Value of $380 (UNDERVALUED)
Still, Onto Innovation’s narrative can unravel if advanced packaging capex slows or if larger rivals use deeper R&D budgets to squeeze pricing and share.
Find out about the key risks to this Onto Innovation narrative.
Another View on Onto Innovation’s Valuation
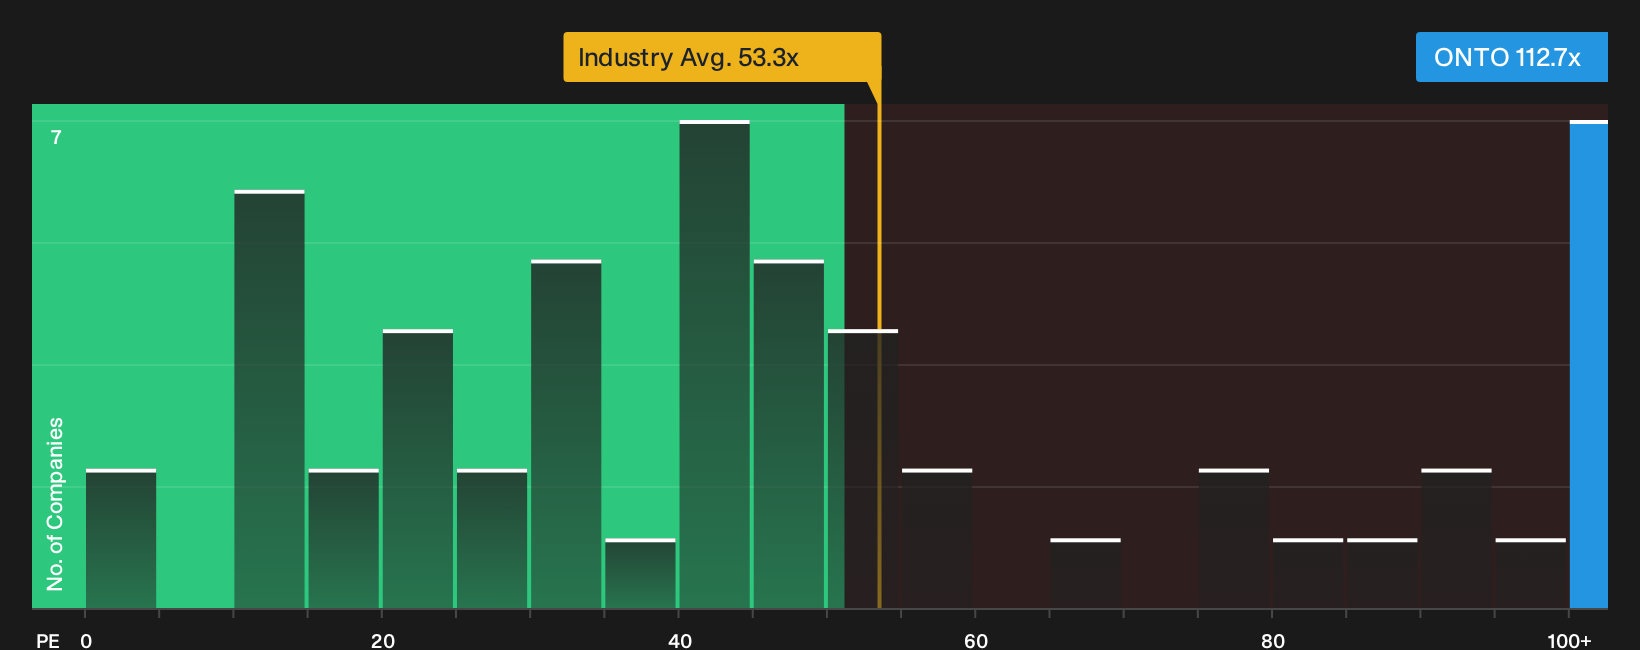
That $380 fair value case leans heavily on growth and margin potential. The market today is sending a very different signal. Onto Innovation trades on a P/E of 112.7x, which is more than double the US Semiconductor industry at 53.3x and above peer averages near 51.1x, while also sitting far above a fair ratio of 46x. For investors, the question is simple. How comfortable are you paying this kind of premium if sentiment cools?
For a closer look at what this premium means in practice, including how it could compress if expectations reset, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Onto Innovation feels familiar, move quickly, verify the data carefully, and weigh the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond Onto Innovation?
If Onto Innovation has sharpened your focus, broaden your watchlist now. Fresh opportunities rarely wait, and you do not want to spot them late.
- Target bigger upside potential by scanning for quality companies trading at compelling valuations through our 29 high quality undervalued stocks.
- Build a steadier income stream by reviewing resilient payers in the 7 dividend fortresses that combine yield with stronger fundamentals.
- Strengthen your downside protection by filtering for companies with sturdier finances using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com