
Is Tokyu (TSE:9005) Undervalued After Its Share Price Slide?
Tokyu (TSE:9005) has come under the spotlight after a period of weaker share performance, with the stock down over the past month and past 3 months, prompting investors to reassess the diversified transport and real estate group.
For context, Tokyu’s 1 year total shareholder return declined 7.68%, while the share price fell 12.60% year to date to ¥1,585. This points to fading momentum and suggests recent moves reflect shifting expectations around both growth prospects and risk.
Contrast Tokyu’s recent share slide with other transport and infrastructure plays by scanning our curated list of list of solid balance sheet and fundamentals (23 results) to explore potential alternatives that may exhibit steadier momentum.
Tokyu runs a broad transport and real estate operation, yet the weaker share price has widened the gap between business scale and market mood. Is that gap a genuine valuation opportunity, or a warning sign on pricing today?
Most Popular Narrative: 21% Undervalued
Tokyu’s most followed valuation storyline pegs fair value at ¥2,004, which sits well above the last close of ¥1,585 and frames the recent share pullback as a potential mismatch between price and underlying business drivers.
Tokyu's expansion into high-demand areas like Shibuya with competitive real estate projects can drive rental income growth, ultimately boosting revenue. Active measures to manage rising construction costs and inflation through strategic portfolio management can protect profit margins and enhance overall earnings.
See why 0 investors see Tokyu as 21% undervalued.
The narrative rests on a discount rate of 9.73%, and assumes long term revenue growth of about 2.6%, with net profit margins modeled at roughly 8%. Analysts in that framework are effectively asking investors to accept a future P/E of around 15.3x on projected earnings. This is compared with Tokyu’s current P/E that sits well below both the JP Transportation industry average of 11.7x and an estimated fair P/E of 14.5x.
That gap between the current earnings multiple and the higher level implied by the fair value model signals a clear disconnect between today’s market mood and the expectations embedded in the most widely tracked thesis. For readers who want to stress test those inputs, the key levers to challenge are the modest revenue growth path, the small squeeze in margins from current levels, and how comfortable they are with a discount rate just under 10% for a diversified transport and real estate group of Tokyu’s scale.
Result: Fair Value of ¥2,004 (UNDERVALUED)
Still, the Tokyu story can break if construction costs continue to climb faster than rents, or if an economic slump hits passenger traffic and tenant demand at the same time.
Find out about the key risks to this Tokyu narrative.
Another View: Tokyu On Cash Flows
There is a very different signal coming from the SWS DCF model, which estimates Tokyu’s future cash flow value at ¥859.51 against a market price of ¥1,585. On this lens the shares screen as overvalued, so the question is whether cash flow assumptions are simply too harsh or the earnings multiple story is too generous.
For readers who want to unpack how that cash flow view is built and which levers matter most, Look into how the SWS DCF model arrives at its fair value.
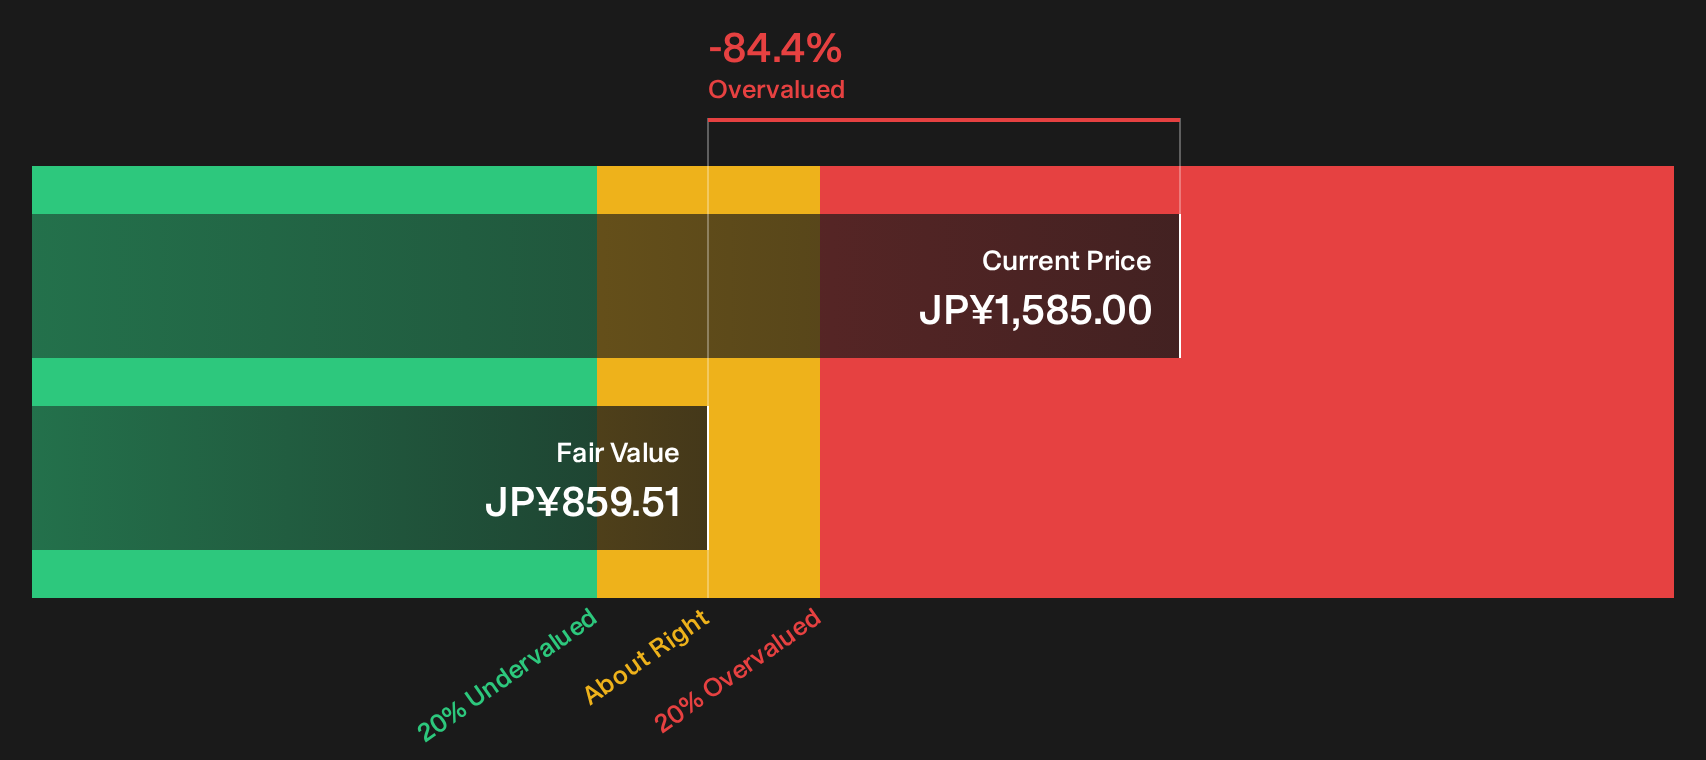
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tokyu for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Tokyu can feel confusing, so move quickly from headline narratives to the underlying numbers and decide where you land on 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Tokyu?
If Tokyu has you rethinking where your next yen should go, broaden your watchlist with a few focused stock ideas built from the Simply Wall St screener.
- Target resilient balance sheets and cash generation by scanning a list of solid balance sheet and fundamentals (23 results) that filters for financial strength and staying power.
- Hunt for potential mispricings by reviewing a 15 high quality undervalued stocks that pairs quality fundamentals with valuations that may look out of sync with business strength.
- Prioritise steady income potential by checking a 22 dividend fortresses designed to surface higher yield payers with the capacity to support distributions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com