
Will Earnings Beat Change RPM International (RPM) Stock Narrative
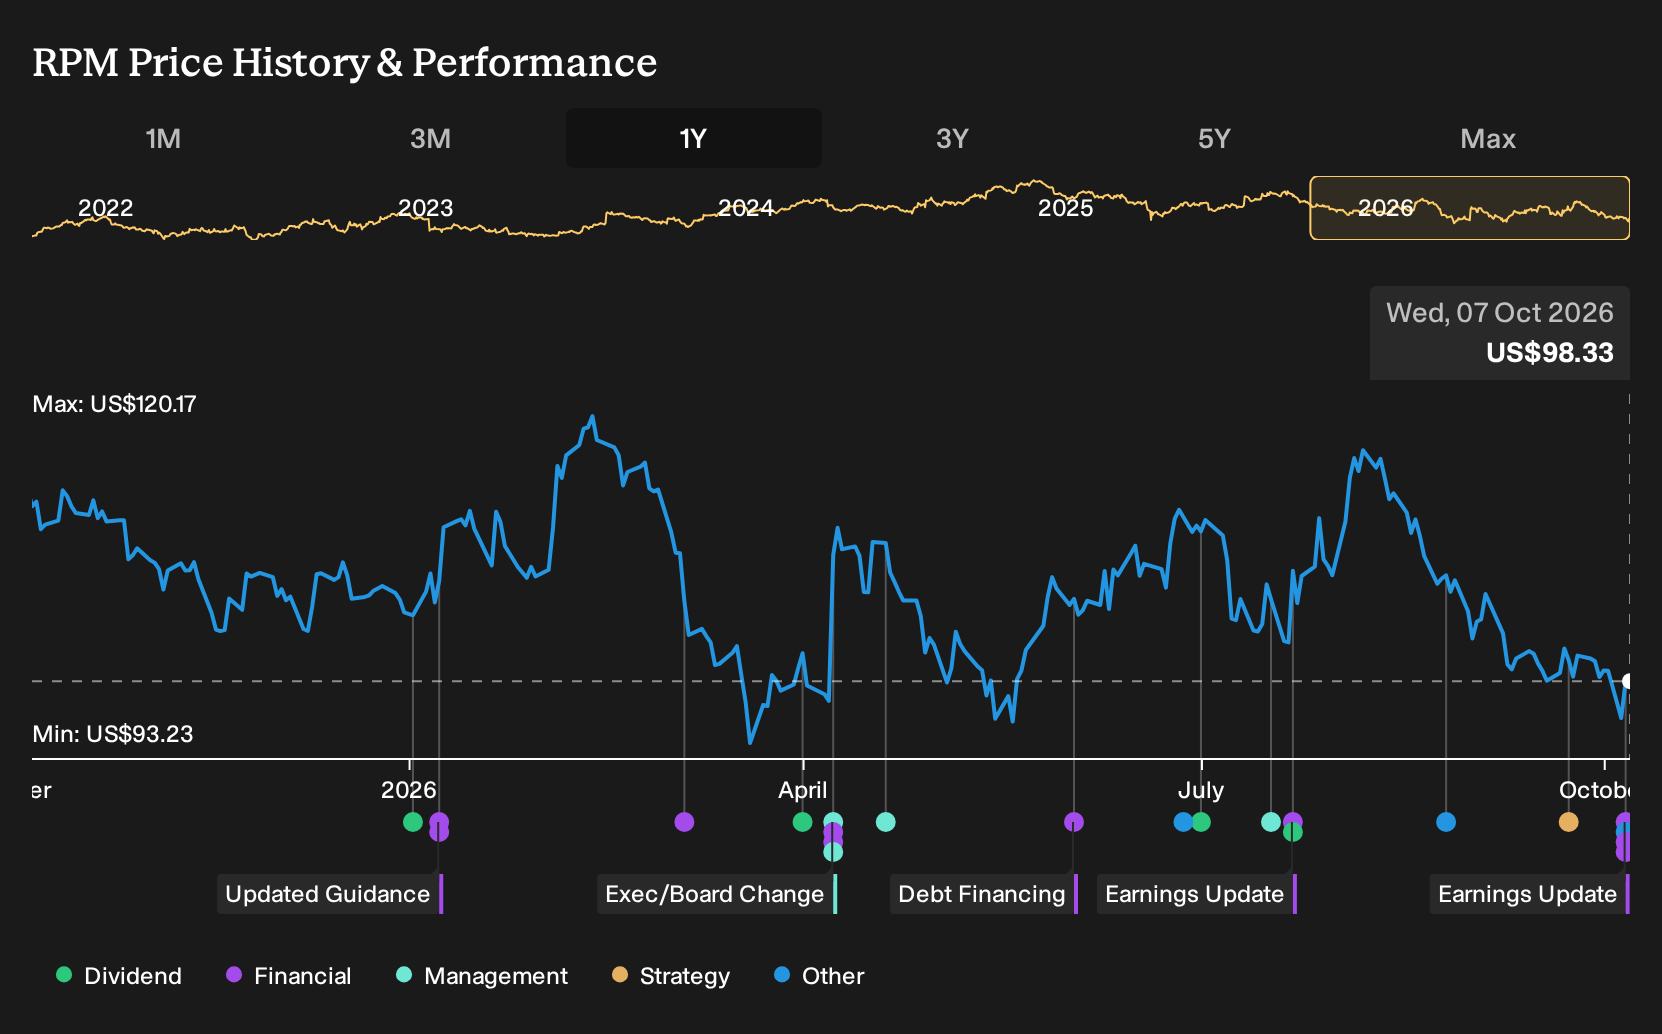
- RPM International reported first quarter 2027 results in early October, with sales of US$2,215.59 million and net income of US$256.36 million, and basic earnings per share from continuing operations of US$2.02.
- The quarter combined record revenue and adjusted EBITDA with contributions from Performance Coatings, acquisitions like Volteco, tighter SG&A control, and ongoing share repurchases that have retired about 13.38 million shares since 2008.
- We will now look at how RPM International's record first quarter earnings performance could shape the broader investment narrative from this point forward.
Scan RPM International's earnings story against a curated set of industrial and materials peers by reviewing the list of solid balance sheet and fundamentals (25 results) that could handle similar cost and pricing pressures.
RPM International Investment Narrative Recap
For RPM International, the core belief is that a steady tilt toward maintenance, repair and restoration work, combined with disciplined cost programs like MAP 2025 and MAP 3.0, can keep earnings power resilient. The latest quarter, with higher sales and net income than a year ago plus record adjusted metrics, supports that execution story without meaningfully changing it.
The key short term swing factor still looks like how quickly Construction Products and Consumer volumes stabilise against raw material and healthcare cost pressure. Input inflation and elevated benefits costs remain the biggest operational risk. Recent results show those pressures are being absorbed but not removed.
The most relevant update is RPM International’s fresh guidance that points to low to mid single digit sales growth for the second quarter and mid single digit growth for fiscal 2027. That outlook tightens previous expectations yet still assumes the cost programs and system selling initiatives keep margins supported while demand in weaker areas gradually improves.
This guidance matters for investors watching near term catalysts. It ties the earnings beat back to ongoing SG&A optimisation, integration of acquisitions such as Volteco into higher value waterproofing systems, and the long running capital return mix that includes share buybacks. Execution against these points, while managing inflation and consumer softness, will likely shape how the story is judged over the next few quarters.
RPM International Earnings Outlook And Valuation Bridge
RPM International's narrative projects US$8.9b revenue and US$976.7 million earnings by 2029. This aligns with analyst assumptions of 4.3% yearly revenue growth and an earnings increase of about US$317.9 million from US$658.8 million today.
Uncover how RPM International's fair value indicates a 32% potential upside to its current price before renewed confidence in RPM International closes that discount.
Exploring Other Perspectives
Some of the most optimistic analysts focus on RPM International’s plant consolidation catalyst. They were already penciling in about US$9.3b of 2029 revenue and US$1.0b of earnings before this record quarter landed. You can see how that more upbeat script might shift, so compare it with your own view of the latest guidance.
Explore 4 other RPM International fair value estimates, including one that suggests potential upside of up to 52% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RPM International research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for RPM International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RPM International's overall financial health at a glance.
Looking For More RPM International Style Ideas?
If RPM International's mix of earnings resilience, cost discipline and capital returns appeals to you, it can help to line it up against other opportunities with similar strengths. Use the Simply Wall St Screener to surface a wider field of stocks that match the type of balance sheet quality, value or income profile you want to focus on next.
- For investors hunting for resilient balance sheets and solid fundamentals, start with this curated list of solid balance sheet and fundamentals (25 results) that can help you separate sturdier businesses from the rest.
- If value is your priority, scan through a hand picked roster of 29 high quality undervalued stocks that combine quality metrics with prices that may sit below their estimated worth.
- Income focused investors can widen their search by reviewing a set of 8 dividend fortresses built around higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com