
Does Back To The Bricks Change The Bull Case For Harley Davidson Stock?
- Harley-Davidson's new CEO Artie Starrs, who took over in October 2025, has rolled out the Back to the Bricks plan that centers on classic motorcycle models, tighter dealer relationships and a renewed push to support rider communities such as the Harley Owners Group.
- The renewed emphasis on dealer profitability, healthier inventory levels and community engagement signals that Harley-Davidson is tying its brand refresh directly to execution on its core retail channel rather than relying mainly on product launches or financial engineering.
- We will now look at how Harley-Davidson's Back to the Bricks focus on classic models could reshape the broader investment narrative.
Harley-Davidson Investment Narrative Recap
To own Harley-Davidson, you need to trust that Back to the Bricks can convert brand loyalty into healthier dealer profits and steadier motorcycle demand while cost savings show up in the income statement. In the short term, the hinge remains execution on classic and affordable models through dealers and Parts & Accessories attachment rather than volume at any cost.
The biggest swing factor today is whether tariffs, raw material costs and a lower priced mix continue to pressure margins after the recent 26% profit decline and 6.2% operating margin in Q2 2026. If those headwinds persist, the risk is that mid single digit adjusted EBITDA margins become the ceiling rather than a temporary setback.
The most relevant piece of the story tied to Artie Starrs and Back to the Bricks is the cost and margin program already outlined. Management is targeting at least US$150 million in fixed cost savings and HDMC EBITDA of US$350 million or more by 2027. That sits alongside the renewed focus on dealers, classic bikes and H.O.G. style communities.
For you, the question is whether those savings and mix changes can offset tariff costs of US$75 million to US$90 million guided for 2026 and support earnings quality over time. The capital light shift at Harley-Davidson Financial Services and the cleaner balance sheet create room to keep funding this reset, but margin pressure and lower forecast revenue growth remain front of mind.
Harley-Davidson's forecast projects US$4.0b in revenue and US$259.6 million in earnings by 2029. This outlook assumes revenue will decrease by 1.9% per year and implies an earnings increase of about US$57 million from US$202.6 million today.
Discover how Harley-Davidson's fair value indicates a 5% potential upside to its current price that may not last much longer.
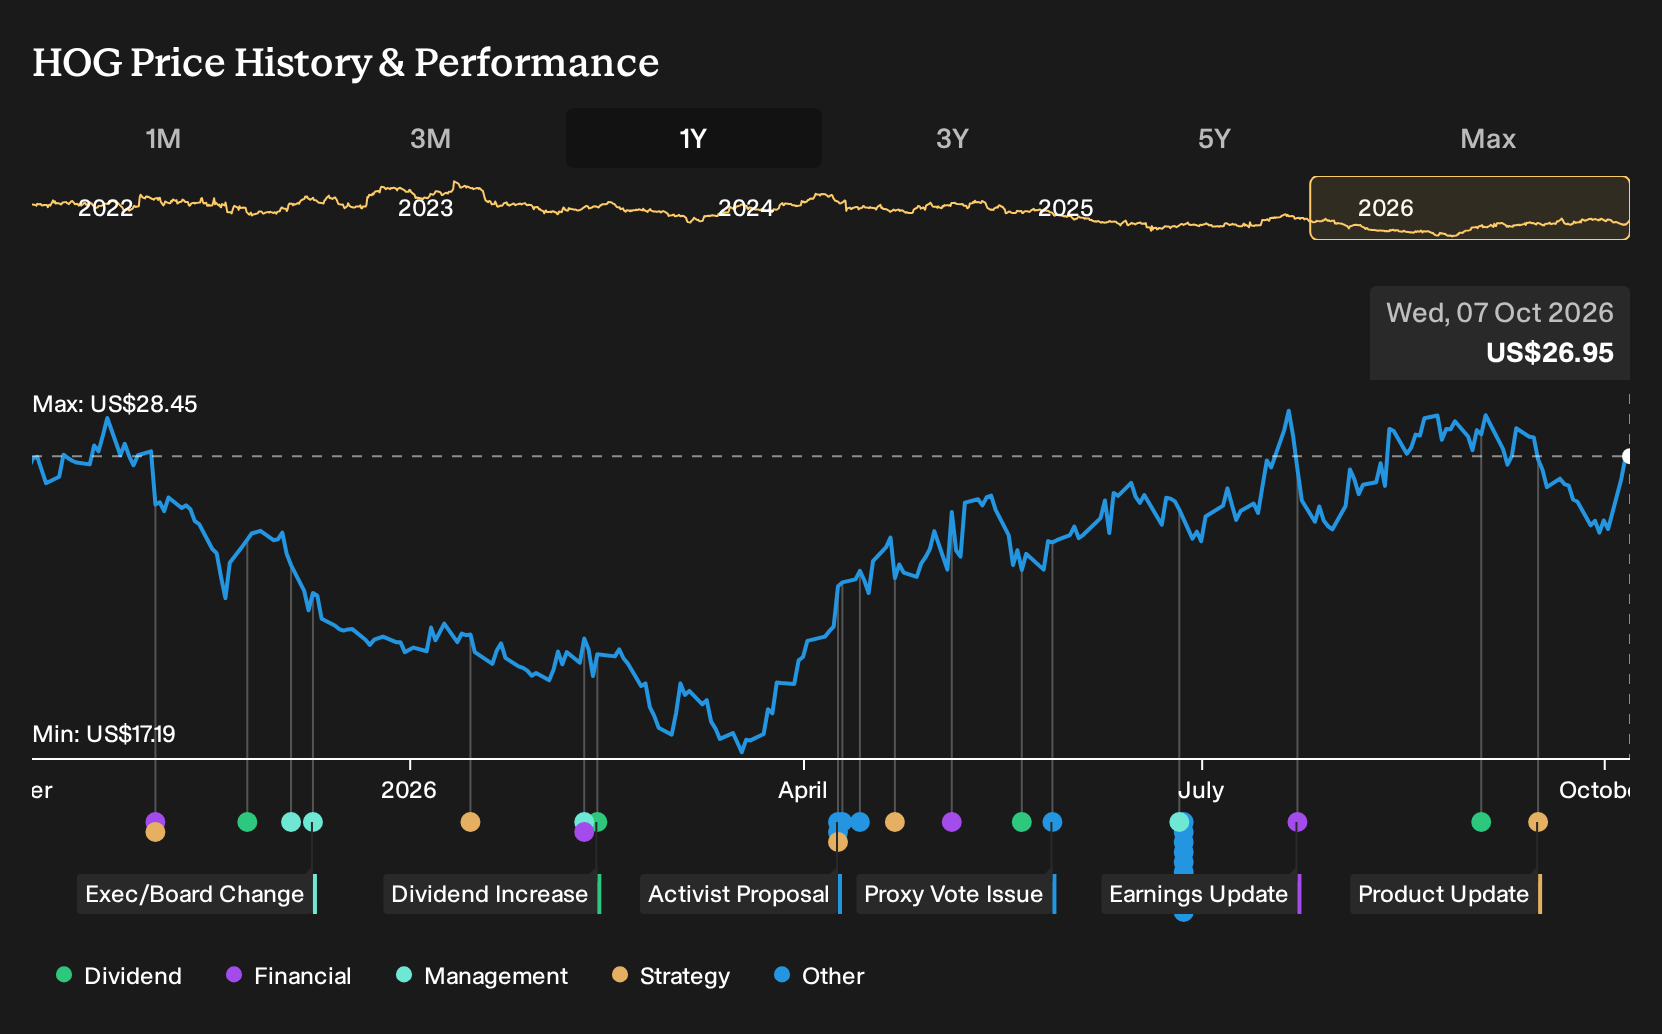
Exploring Other Perspectives
One alternate view says the biggest swing factor is not Back to the Bricks at Harley-Davidson, but how far revenue and earnings could drift if core demand softens. The most bearish analysts were pencilling in roughly US$3.8b of revenue and US$199.7 million of earnings by 2029. That is a much harsher path than the consensus, and those estimates were set before this leadership and community push, so you may see them move if the reset gains traction. Use that spread to stress test your own expectations and explore how different assumptions can lead to very different conclusions.
Explore 3 other Harley-Davidson fair value estimates, including one that suggests as much as 82% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Harley-Davidson research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Harley-Davidson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Harley-Davidson's overall financial health at a glance.
Looking For More Investment Ideas Beyond Harley-Davidson?
If the Harley-Davidson reset has you rethinking where brand strength, balance sheets and income durability intersect, it can help to line it up against a wider watchlist. The Simply Wall St Screener lets you filter for the traits that matter most to you, then compare how different businesses stack up on fundamentals before you commit fresh capital.
- If you prefer to focus on quality at a discount, with solid cash flows and balance sheets as your anchor, start with 29 high quality undervalued stocks and see which other businesses line up with that profile.
- If stability and capital preservation come first for you, filter for resilient companies using the 31 resilient stocks with low risk scores and see which ones best match your risk tolerance.
- If you want to broaden your universe beyond headline tickers and find lesser known operators with robust financials, scan the 20 high quality undiscovered gems to surface ideas you might otherwise miss.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com