
Performance Food Group (PFGC) Following Demand Worries And Margin Pressure Looks Fully Valued
Recent underperformance puts Performance Food Group in focus
Performance Food Group (PFGC) is back on investor watchlists after recent commentary highlighted its weaker share returns versus the broader market, tied to soft sales volumes and pressure on profitability.
The recent share price tells a mixed story for Performance Food Group. The stock trades at US$93.48, with the share price down 16.57% over the past 90 days but still up 6.17% year to date. The 1 year total shareholder return declined 6.84%, compared with a 67.11% total shareholder return over three years and 97.38% over five years. This suggests momentum has cooled as investors reassess growth prospects and risk around softer volumes and profitability pressure.
Scan beyond Performance Food Group and compare its recent slump against hand-picked distributors and retailers in the 29 high quality undervalued stocks that combine financial strength with more appealing entry prices.
Performance Food Group looks like a solid distributor on paper, but the recent share pullback forces a sharper question. Are investors now getting that quality business at a sensible price, or still paying up for it?
Most Popular Narrative: 24% Undervalued
Against the last close of $93.48, the most followed valuation narrative for Performance Food Group points to a fair value of $123.23, implying a sizeable gap that hinges on execution in margins, case growth, and efficiency projects.
Procurement initiatives that are expected to reach or exceed the high end of the US$120m to US$125m synergy target by fiscal 2028, together with the reported US$0.34 per case gross profit uplift in Q4 2026, set up a structural tailwind for net margins and EBITDA.
See why 3 investors see Performance Food Group as 24% undervalued.
Result: Fair Value of $123.23 (UNDERVALUED)
Still, the story around Performance Food Group only holds if fuel costs stop eroding margins and the Convenience segment avoids a prolonged period of softer sales.
Find out about the key risks to this Performance Food Group narrative.
Another View on Performance Food Group’s valuation
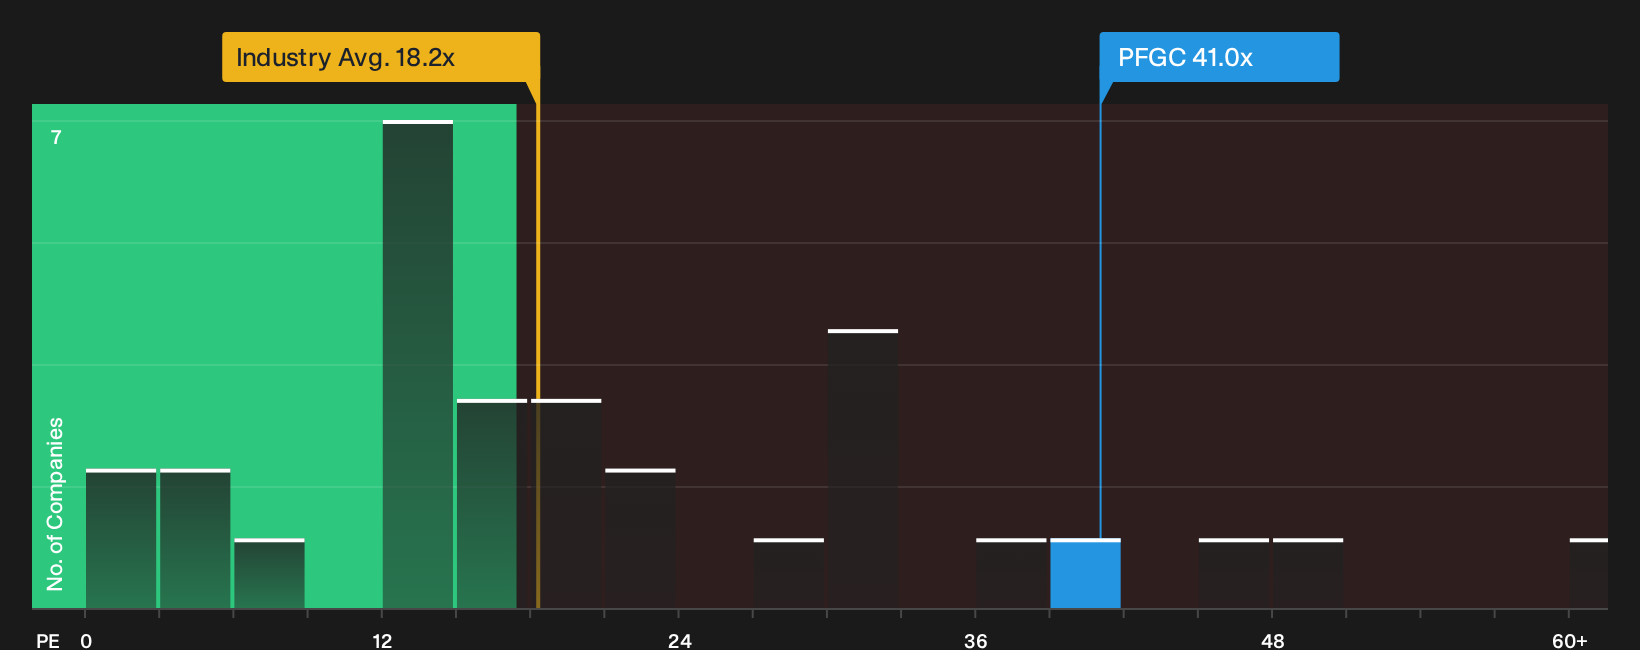
The analyst narrative presents Performance Food Group as undervalued, yet the market multiples send a very different message. The stock trades on a P/E of 41x, compared with 18x for the US Consumer Retailing sector and a fair ratio of 31.1x, which suggests investors are already paying a premium.
That gap can indicate confidence in the long term story or it can leave less margin for error if execution slips. The key question is whether you think earnings can justify that richer multiple over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Performance Food Group will not resolve themselves. Look through the numbers, weigh the concerns and bright spots, and then test your own thesis against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Performance Food Group?
If the Performance Food Group debate sharpened your thinking, do not stop here. Broaden your opportunity set and pressure test your thesis across fresh ideas.
- Target resilient returns by scanning a 31 resilient stocks with low risk scores that prioritises financial strength when conditions get choppy.
- Hunt for quality on sale by reviewing a 29 high quality undervalued stocks that filters for strong businesses trading below their assessed worth.
- Spot tomorrow’s potential leaders early by checking a 20 high quality undiscovered gems before the crowd turns its attention there.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com