
Is Pacira BioSciences (PCRX) Undervalued On Its Molteni EXPAREL Distribution Deal?
What Pacira’s Molteni deal could mean for the stock
Pacira BioSciences (PCRX) just signed an exclusive distribution agreement with Molteni Farmaceutici for EXPAREL across select European markets, creating a new channel for upfront income, supply revenue, and potential future royalties.
Pacira BioSciences is coming off a mixed stretch, with a 1-day share price return of 1.78% and a year-to-date share price return of 3.03%. The 1-year total shareholder return of 7.65% contrasts with a 5-year total shareholder return that declined 51.64%, suggesting the Molteni agreement arrives as momentum is tentatively rebuilding after a longer period of weaker results.
Scan beyond Pacira BioSciences and size up other pain management and healthcare stocks that screen well on cash flows and balance sheets by using this curated list of solid balance sheet and fundamentals (25 results).
Pacira BioSciences just picked up fresh European optionality while the share price recovery is still modest. Has most of the rerating already happened, or do the current numbers still leave room for meaningful upside?
Most Popular Narrative: 16% Undervalued
Pacira BioSciences last closed at $25.20. The most followed narrative framework pegs fair value closer to $30, suggesting the market is still discounting several moving parts around EXPAREL, ZILRETTA, and the pipeline even after the Molteni news.
Expansion of the EXPAREL patent estate to 21 listed patents, together with a volume-limited generic settlement that defers significant competition until at least 2030, provides a longer window to convert current utilization into sustained revenue and cash flow.
See why 11 investors see Pacira BioSciences as 16% undervalued.
Result: Fair Value of $30 (UNDERVALUED)
Still, Pacira BioSciences leans heavily on EXPAREL and current reimbursement support, and any setback in PCRX-201 or PCRX-2002 could quickly weaken this undervalued thesis.
Find out about the key risks to this Pacira BioSciences narrative.
Another View: Pacira BioSciences Through The P/E Lens
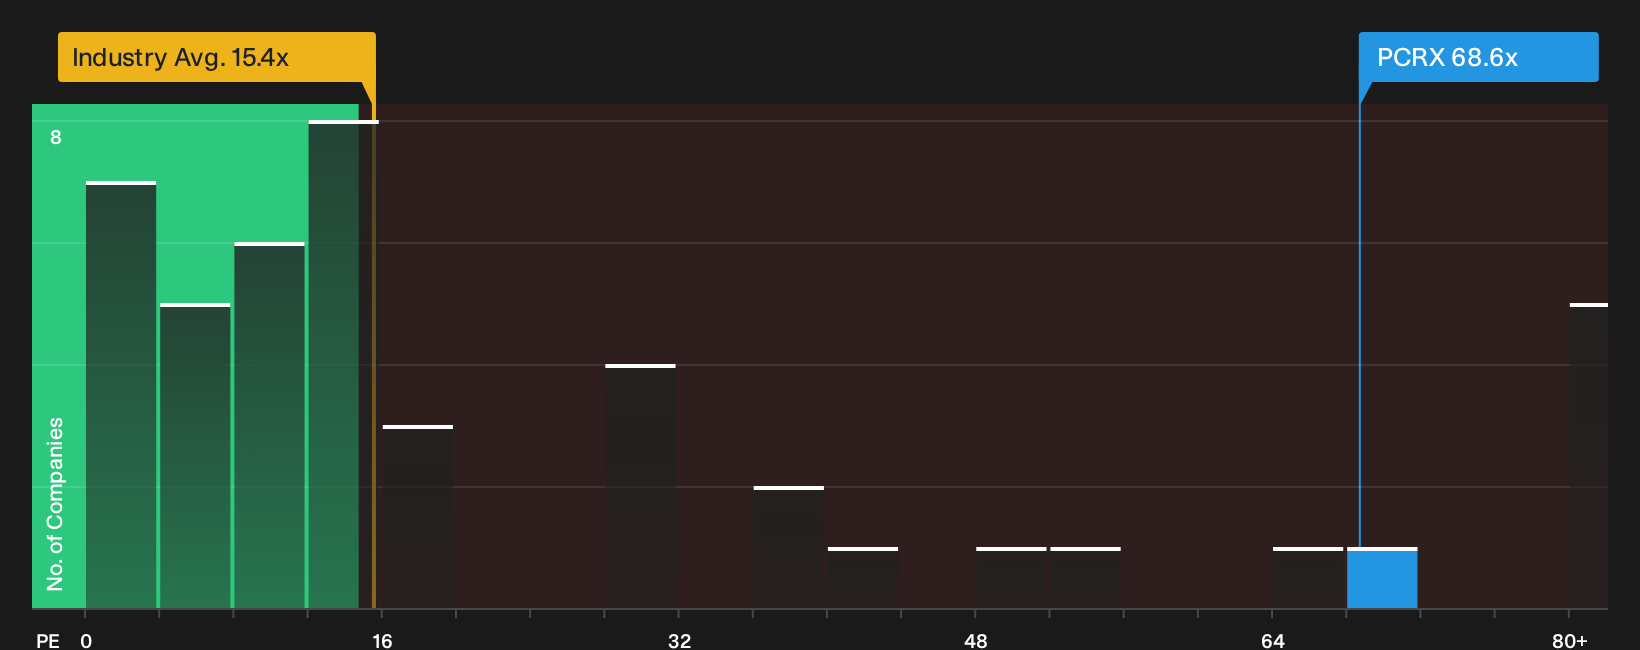
Pacira BioSciences’ earnings multiple conveys a very different message. The stock trades on a P/E of 68.6x, compared with 15.1x for the US Pharmaceuticals group, 9.3x for close peers, and a fair ratio of 20.1x that the market could eventually lean toward.
If the share price moved closer to that fair ratio, the valuation gap would narrow sharply, which illustrates how much sentiment is already reflected in today’s earnings multiple. That raises a straightforward question for investors: is this premium a cushion for potential profit growth, or a source of downside risk if expectations cool?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Pacira BioSciences can feel confusing, especially with both risks and potential bright spots in play. Move quickly, review the underlying data, and decide where you stand after weighing 3 key rewards and 1 important warning sign.
Looking for more Pacira BioSciences sized opportunities?
Do not stop with Pacira BioSciences. A few minutes in the Simply Wall Street Screener can surface fresh ideas before they move beyond reach.
- Target higher potential by reviewing companies that combine strong fundamentals with attractive pricing through the 20 high quality undiscovered gems.
- Secure more resilient positions by focusing on businesses that clear tough quality and valuation filters with the 31 resilient stocks with low risk scores.
- Zero in on quality at a reasonable price by scanning financially sound stocks trading below their estimated worth using the 29 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com