
Is Infleqtion (INFQ) Undervalued Or Is Its Quantum Story Already Priced In?
Infleqtion (INFQ) just teamed up with Honeywell Aerospace and UC Santa Barbara to build a chip scale optical cavity that shrinks quantum sensors toward handheld formats, opening fresh questions about how investors should view this quantum hardware story.
Infleqtion has released several technical announcements over the past few weeks, yet the share price has moved in the opposite direction. The 1 day share price return is down 7.2%, the 7 day move is down 13.6% and the year to date share price return is down 32.1%, contributing to a 1 year total shareholder return of down 39.7% that points to fading momentum as investors reassess both growth potential and execution risk.
Spot emerging quantum hardware stories that still have pricing power by scanning our hand picked list of 24 quantum computing stocks.Infleqtion keeps putting technical milestones on the board while the share price drifts lower. The real work now is figuring out whether that disconnect reflects genuine mispricing or a fair read on risk as valuation comes under the microscope.
Most Popular Narrative: 47% Undervalued
Infleqtion last closed at $11.64, while the most widely followed narrative pegs fair value at about $21.83, so the story hinges on whether the quantum roadmap and contracts can support that gap once the discount rate of 8.58% is applied.
Neutral atom systems operating at room temperature and using a common hardware and software stack across computing and sensing can keep capital needs relatively contained as the product set scales. This may help operating leverage and net margins as volumes build.
See why 53 investors see Infleqtion as 47% undervalued.
On this view, Infleqtion is treated as a pure play on neutral atom hardware and software. Quantum sensing is seen as the base layer, with logical qubits as optional upside. The fair value estimate of $21.83 uses that 8.58% discount rate to pull future revenue, margin and multiple assumptions back into today’s dollars, then compares that to the current share price to frame an implied 46.7% discount.
Supporters of this narrative point to forecast annual revenue growth above 20%, a debt free profile in prior commentary and a focus on secure timing, GPS free navigation and government backed quantum programs that can provide multi year contract exposure. At the same time, the model still assumes Infleqtion remains loss making over the next three years, which keeps execution, cash burn and competitive technology risk front and center for anyone stress testing those long range earnings and valuation inputs.
Result: Fair Value of $21.83 (UNDERVALUED)
Still, the Infleqtion story leans heavily on government programs and a neutral atom roadmap, and setbacks on contracts or modality adoption could quickly challenge that undervaluation pitch.
Find out about the key risks to this Infleqtion narrative.
Another View: Infleqtion Through A P/B Lens
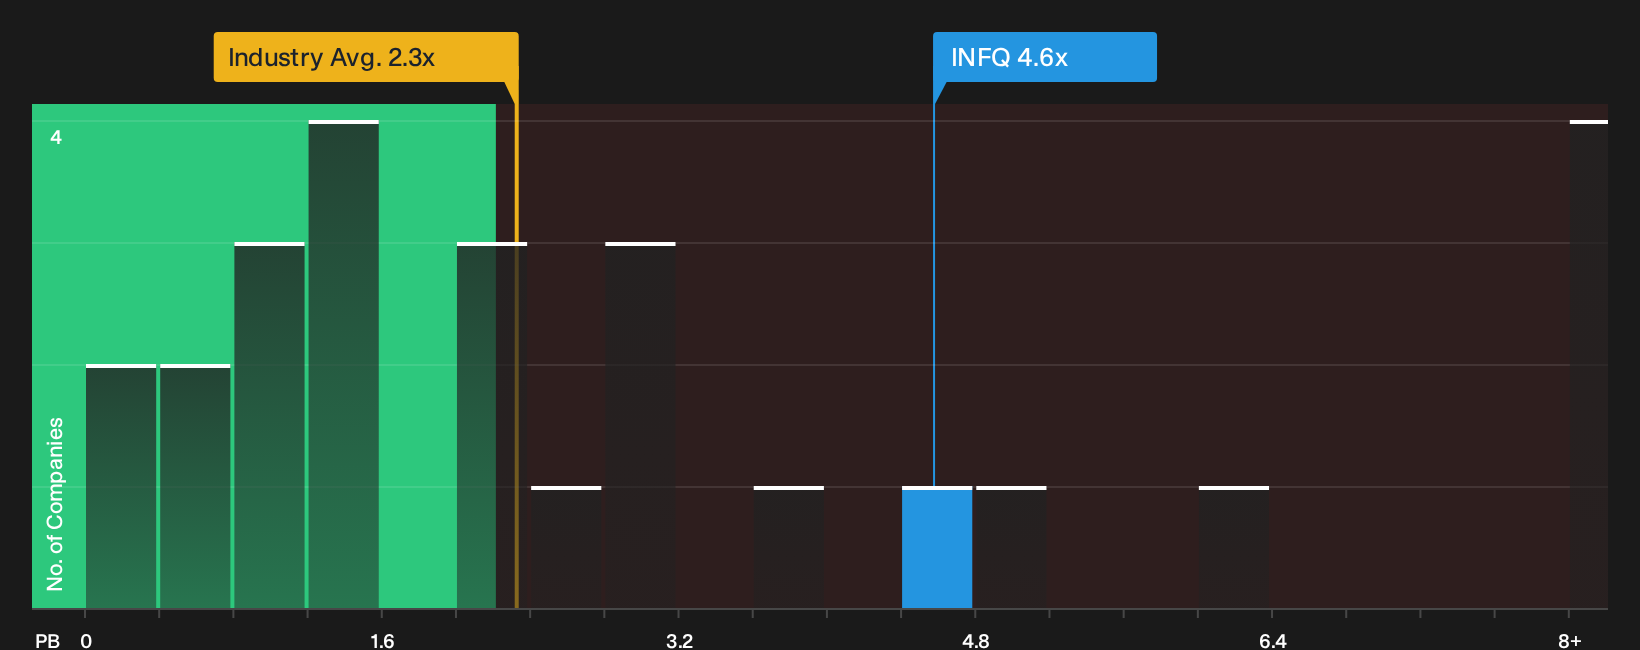
Infleqtion might look cheap on a story driven fair value of $21.83, yet the P/B ratio tells a different story. At 4.6x book value versus 2.3x for the wider US Tech group and 1.7x for direct peers, the stock already trades at a steep premium that could limit upside if sentiment cools.
Investors weighing that premium against the growth narrative may want to see what the numbers imply at different valuation levels through our detailed breakdown, then decide which side of the argument feels more realistic for their own time horizon. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If you are unsure whether Infleqtion’s recent news flow aligns with the current valuation reset, or if sentiment has moved too far in either direction, you can weigh the mix of concerns and upside potential for yourself by checking the 3 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Infleqtion?
If Infleqtion has sharpened your focus on valuation, do not stop here. The screener can surface fresh opportunities that fit your own risk and income goals.
- Target potential mispricing opportunities by reviewing companies filtered for quality and value through the 29 high quality undervalued stocks.
- Secure more predictable income streams by scanning for resilient payers using the 8 dividend fortresses.
- Dial back portfolio risk while still staying invested by assessing companies that pass our resilience checks with the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com