
Global's Top 3 Stocks Trading Below Estimated Value In October 2026
In October 2026, global markets are navigating a complex landscape marked by mixed signals from major U.S. stock indexes, persistent inflation concerns, and fluctuating oil prices. As investors assess these conditions, identifying stocks trading below their estimated value can offer opportunities for those looking to capitalize on potential market inefficiencies. In such an environment, a good stock is often characterized by strong fundamentals and resilience in the face of economic uncertainties.
Top 10 Undervalued Stocks Based On Cash Flows
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Woori Financial Group (KOSE:A316140) | ₩32500.00 | ₩64551.94 | 49.7% |
| TOKAI (TSE:9729) | ¥2532.00 | ¥5037.09 | 49.7% |
| PORR (WBAG:POS) | €30.05 | €59.76 | 49.7% |
| Nanya Technology (TWSE:2408) | NT$533.00 | NT$1065.55 | 50% |
| Mitsubishi Research Institute (TSE:3636) | ¥4820.00 | ¥9628.69 | 49.9% |
| Lindab International (OM:LIAB) | SEK125.30 | SEK250.27 | 49.9% |
| Kumagai GumiLtd (TSE:1861) | ¥1196.00 | ¥2368.66 | 49.5% |
| Innocean Worldwide (KOSE:A214320) | ₩17830.00 | ₩35592.12 | 49.9% |
| Erste Group Bank (WBAG:EBS) | €110.60 | €219.96 | 49.7% |
| APAC Realty (SGX:CLN) | SGD0.52 | SGD1.03 | 49.7% |
Let's review some notable picks from our screened stocks.
Türkiye Sigorta (IBSE:TURSG)
Overview: Türkiye Sigorta A.S. is a non-life insurance company operating in Turkey with a market cap of TRY110.40 billion.
Operations: The company's revenue segments include Fire at TRY10.39 billion, Motor Vehicles at TRY16.88 billion, General Damages at TRY12.97 billion, and Motor Vehicles Liability at TRY14.04 billion.
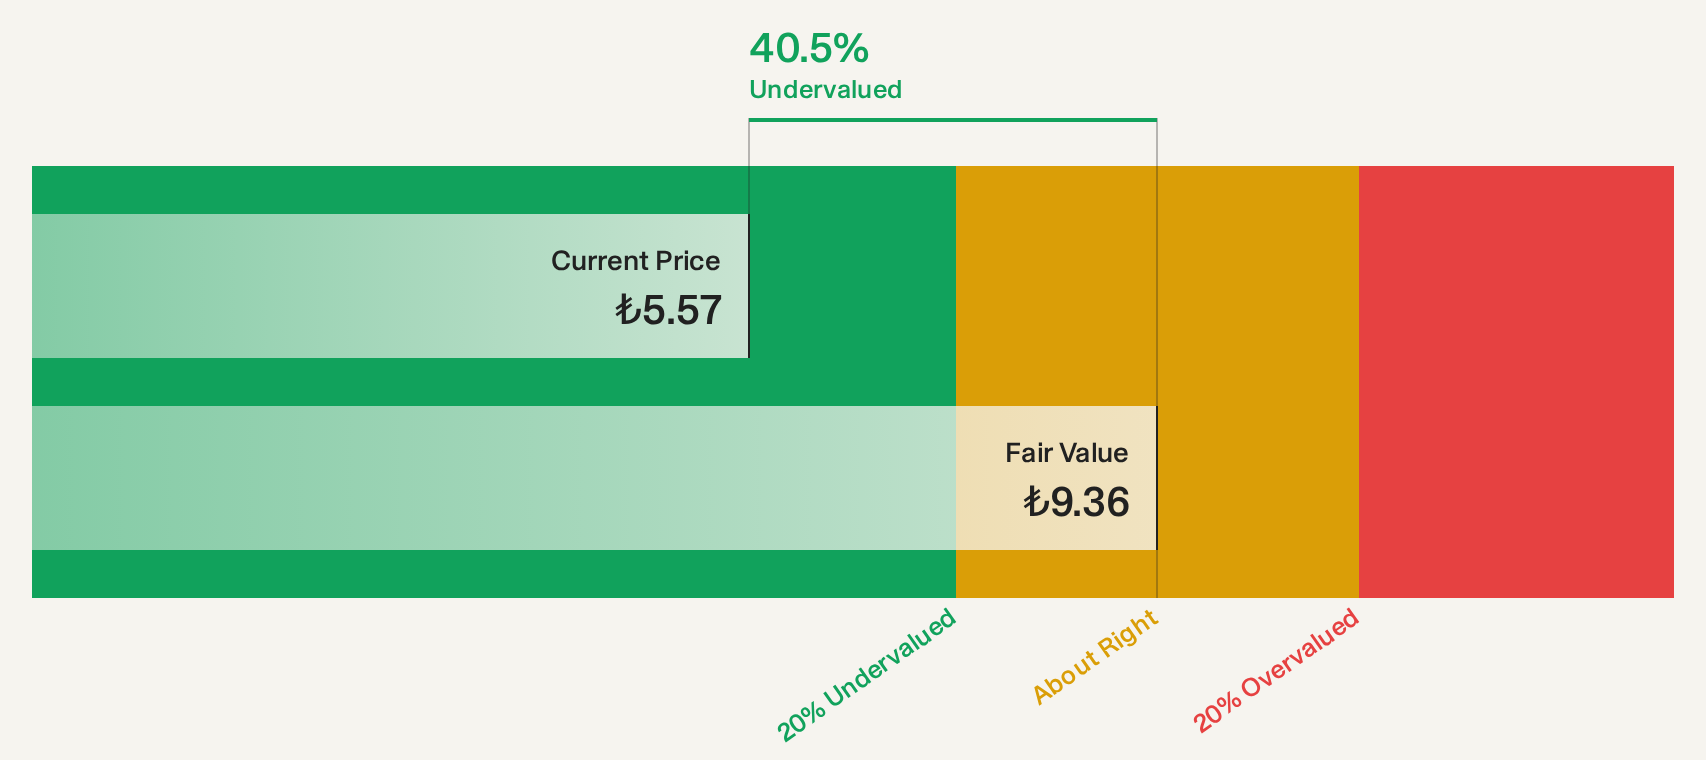
Estimated Discount To Fair Value: 41%
Türkiye Sigorta appears undervalued based on discounted cash flow analysis, trading at TRY 5.52 compared to an estimated future cash flow value of TRY 9.36. The stock is priced 41% below its fair value estimate, with analysts projecting a potential price increase of 76.4%. Despite recent earnings growth, the dividend yield of 2.72% is not well covered by free cash flows, and revenue growth forecasts lag behind the Turkish market average.
- Our comprehensive growth report raises the possibility that Türkiye Sigorta is poised for substantial financial growth.
- Click here to discover the nuances of Türkiye Sigorta with our detailed financial health report.
China Automotive Engineering Research Institute (SHSE:601965)
Overview: China Automotive Engineering Research Institute Co., Ltd. operates in the automotive engineering sector, focusing on research and development services, with a market cap of CN¥13.61 billion.
Operations: I'm sorry, but the revenue segments information for China Automotive Engineering Research Institute Co., Ltd. is missing from the provided text. Please provide the relevant details so I can assist you further.
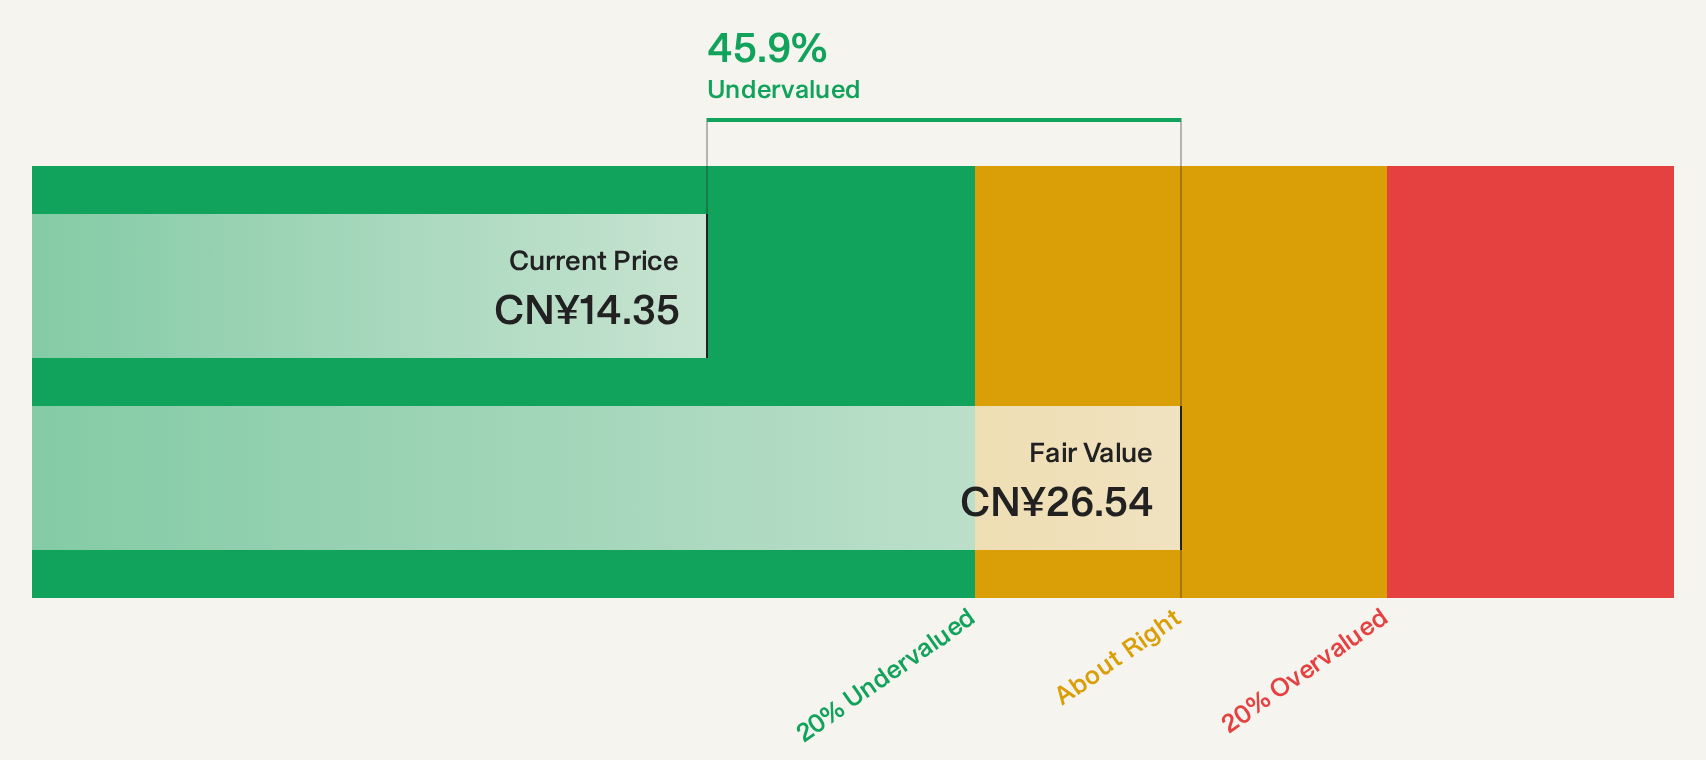
Estimated Discount To Fair Value: 46.5%
China Automotive Engineering Research Institute is trading at CN¥14.11, significantly below its estimated future cash flow value of CN¥26.39, suggesting undervaluation. The company's earnings are expected to grow at 17.07% annually, though slower than the broader Chinese market's pace of 27.3%. Recent financials show sales increased to CN¥2.04 billion for H1 2026 from CN¥1.91 billion a year prior, with net income rising modestly to CN¥429.05 million from CN¥408.6 million.
- Our expertly prepared growth report on China Automotive Engineering Research Institute implies its future financial outlook may be stronger than recent results.
- Take a closer look at China Automotive Engineering Research Institute's balance sheet health here in our report.
Isuzu Motors (TSE:7202)
Overview: Isuzu Motors Limited manufactures and sells trucks, buses, light trucks, and powertrains globally, with a market cap of ¥1.45 trillion.
Operations: The company's revenue is primarily derived from its Automobile segment, generating ¥3.49 billion, followed by the Financial Services segment with ¥215.98 million.
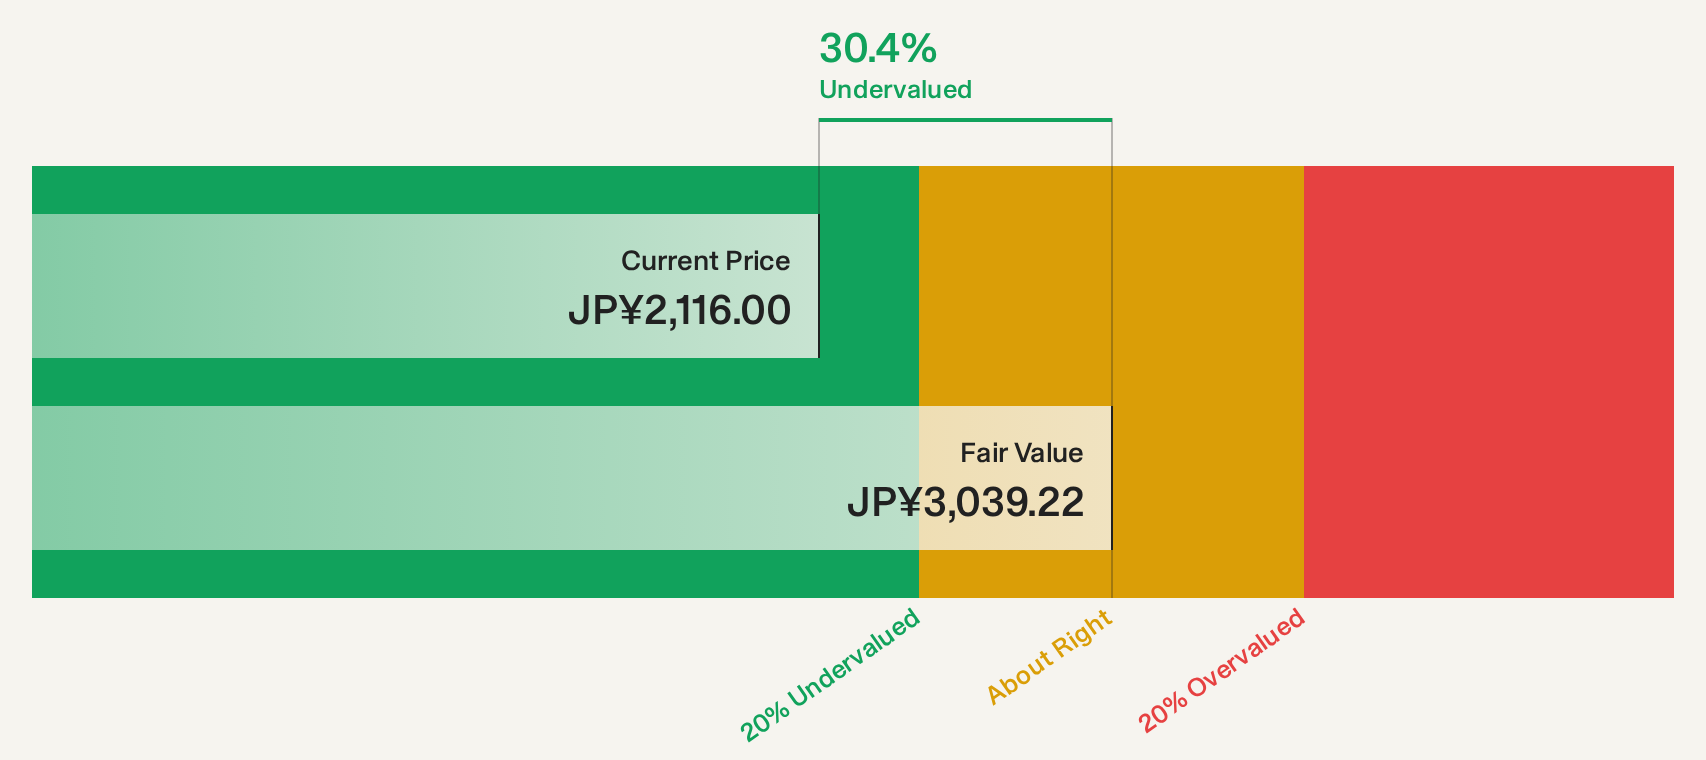
Estimated Discount To Fair Value: 30.1%
Isuzu Motors is trading at ¥2,125, well below its estimated future cash flow value of ¥3,039.22, indicating potential undervaluation. Earnings have grown 3.4% annually over five years and are forecast to rise 10.5% per year, outpacing the JP market's growth rate. Recent earnings showed a net income increase to ¥50.94 billion from ¥41.42 billion year-over-year. However, its dividend yield of 4.42% isn't fully covered by free cash flows and revenue growth lags behind market expectations.
- Insights from our recent growth report point to a promising forecast for Isuzu Motors' business outlook.
- Dive into the specifics of Isuzu Motors here with our thorough financial health report.
Summing It All Up
- Navigate through the entire inventory of 248 Undervalued Global Stocks Based On Cash Flows here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com