
Is MPLX (MPLX) A Bargain Following Its Midstream Growth Narrative?
Zacks recently reiterated MPLX (MPLX) at a Rank #3 Hold while assigning Transportadora De Gas Sa Ord B a Rank #2 Buy, highlighting the partnership’s relative valuation and earnings outlook compared with a close industry peer.
MPLX units currently trade at about $57.05, with the share price slipping over 1 day and over the past month but still showing a positive year-to-date share price return of roughly 6% alongside a 1-year total shareholder return above 26%. This points to longer-term momentum even as near-term enthusiasm cools slightly.
Scan beyond MPLX and TGS to compare valuations, momentum, and financial strength across a curated 29 high quality undervalued stocks that share similar quality but trade at more compressed multiples.
Bulls see MPLX as a steady midstream operator that has simply paused after a strong run, while bears argue the recent wobble flags a stretched valuation. The key question is which case the current pricing actually supports once you line up the numbers.
Most Popular Narrative: 9% Undervalued
MPLX last closed at $57.05, while the most followed narrative estimates fair value at $62.85 using a 7.24% discount rate. That gap puts the focus squarely on whether its gas and NGL buildout can keep earning its current pricing.
The recent acquisition of Northwind Midstream and full ownership of the BANGL NGL pipeline remain central to MPLX. New evidence shows that gathering volumes excluding divested Rockies assets rose 10% year over year in Q1 2026 and 15% in Q2 2026, supporting higher throughput that can feed future revenue and EBITDA contribution from these assets.
See why 82 investors see MPLX as 9% undervalued.
Result: Fair Value of $62.85 (UNDERVALUED)
However, the MPLX story can shift quickly if heavy 2026 capital spending fails to earn its keep, or Permian and Delaware basin activity softens.
Find out about the key risks to this MPLX narrative.
Another View: MPLX Through The P/E Lens
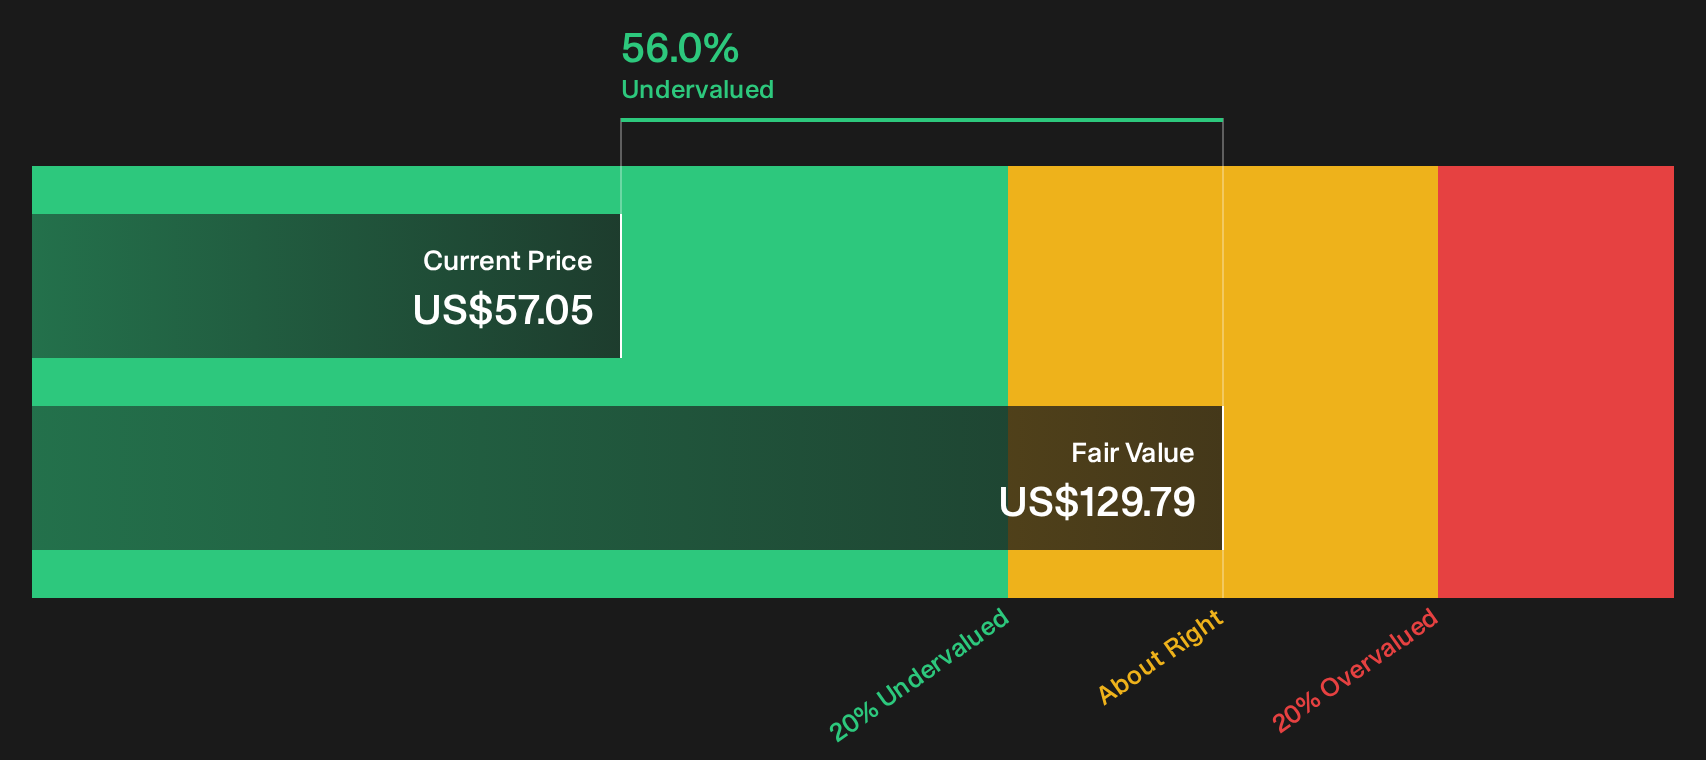
On the first pass, MPLX looks cheap on future cash flows, with the SWS DCF model flagging the units as trading well below an estimated $129.79 per unit value. Step away from that framework and the picture shifts. The current P/E of 12.2x matches the broader US Oil and Gas group but sits well below a 20.3x peer average and an estimated fair ratio of 20.8x, which hints at room for rerating but also raises the question of whether the richer peer and fair ratios are really sustainable anchors for this partnership.
For a closer look at how the cash flow work stacks up against the earnings multiples, run your eye over the full SWS DCF model output next: Look into how the SWS DCF model arrives at its fair value.
Next Steps
With MPLX pulling mixed reactions, you have enough information to stress test the story against your own expectations and risk tolerance. To balance the cautious signals with the upside case, weigh the 3 key rewards and 2 important warning signs.
Looking for more MPLX investment ideas beyond this story?
Do not stop with MPLX alone, because a few minutes in the Simply Wall Street Screener can surface opportunities you might otherwise never even consider.
- Pinpoint resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that filters for companies pairing financial strength with more disciplined fundamentals.
- Hunt for potential mispricings by reviewing a focused 29 high quality undervalued stocks that screens for quality businesses trading at compressed valuations.
- Spot overlooked prospects by checking a curated 20 high quality undiscovered gems that highlights financially sound companies still flying under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com