
Builders FirstSource (BLDR) Slides On Softer Housing Narrative, Is It 34% Below Fair Value?
Builders FirstSource (BLDR) has been under pressure, with the share price down 5% over the past week and about 19% over the past month, extending a broader multiyear decline.
At a share price of US$53.55, Builders FirstSource has seen momentum fade, with the 90 day share price return down 28.2% and the 1 year total shareholder return declining 58.7%. This signals a sharp reset in expectations and perceived risk around the business.
Scan beyond Builders FirstSource and compare this slump with hand picked construction related plays screened for stronger fundamentals and momentum using our list of solid balance sheet and fundamentals (25 results).
For Builders FirstSource, this slide can read two ways. Either sentiment has swung too far, or the share price is finally catching up with the underlying business. The valuation work starts there.
Most Popular Narrative: 34% Undervalued
Against the last close at $53.55, the most followed narrative for Builders FirstSource points to a fair value of $80.62. This frames the recent share price slide as potentially too harsh compared to that estimate.
Previously, housing undersupply and a rebound in starts were expected to drive outsized revenue growth and margin expansion. Now the emphasis is on cost reductions and mix shift helping Builders FirstSource support revenue, EBITDA and free cash flow during softer housing activity.
See why 26 investors see Builders FirstSource as 34% undervalued.
Result: Fair Value of $80.62 (UNDERVALUED)
Still, this hinges on housing activity not weakening further and on Builders FirstSource actually delivering the targeted cost savings and facility consolidation benefits.
Find out about the key risks to this Builders FirstSource narrative.
Another View on Builders FirstSource Valuation
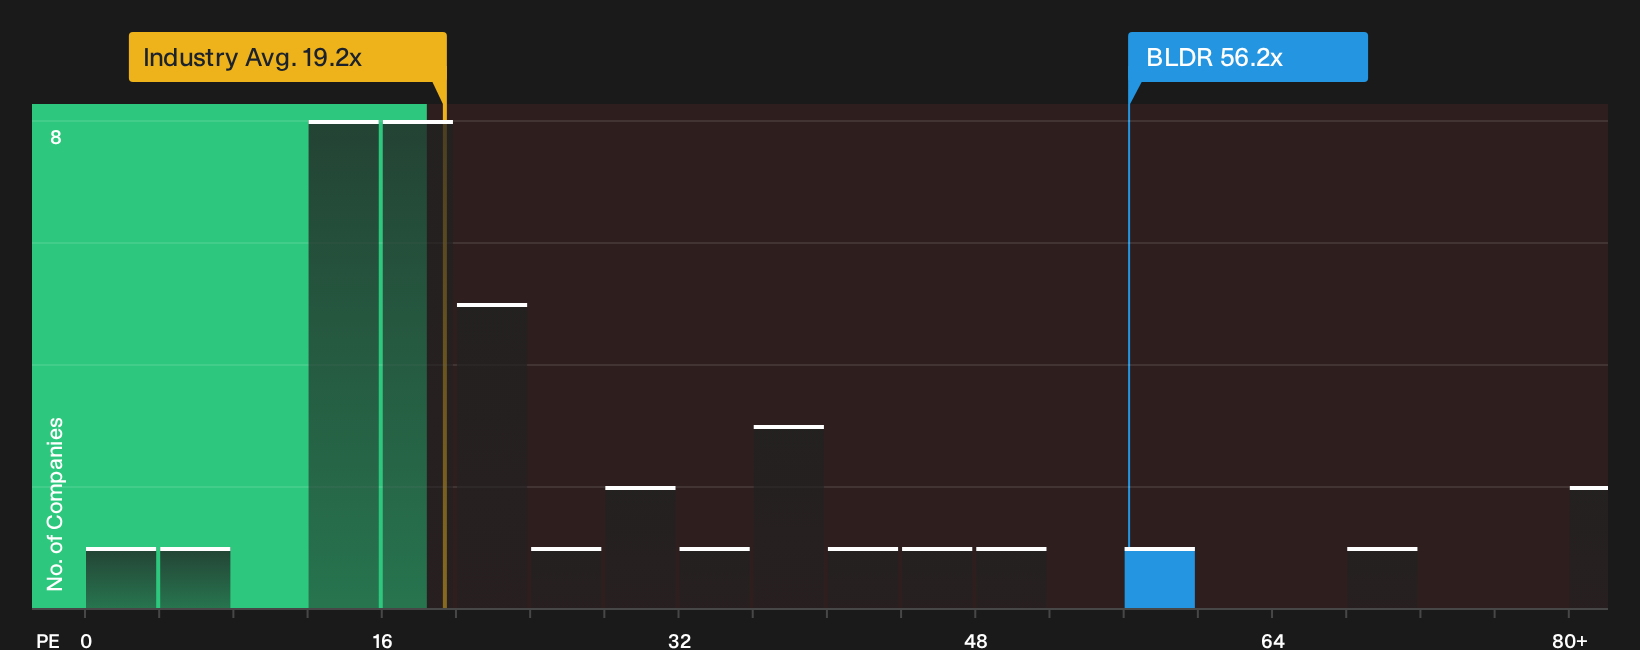
The first narrative leans on future earnings and a fair value of $80.62. A simple P/E check tells a less comfortable story. Builders FirstSource trades on a P/E of 56.2x, while the US Building industry sits at 20.1x and close peers average 20.5x. The fair ratio for BLDR is 64.1x. This still points to a rich multiple and raises a simple question: Is an investor being paid enough for the gap between today’s pricing and those earnings forecasts?
For readers who prefer to work off earnings multiples, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Questions about whether sentiment on Builders FirstSource has swung too negative or not negative enough only get answered by data, not headlines. Act quickly, review the full risk and reward profile, and ground your own view in the underlying numbers by starting with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Builders FirstSource?
If Builders FirstSource has you reassessing your watchlist, do not stop there. Use fresh data and solid filters to help you spot opportunities before the crowd does.
- Target potential mispricings by scanning our 29 high quality undervalued stocks that combine quality fundamentals with prices that may appear out of sync with underlying performance.
- Strengthen your income stream by reviewing a curated set of 8 dividend fortresses that aim to balance higher yields with business resilience.
- Reduce portfolio stress by focusing on resilience first and returns second through a hand picked group of 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com