
MercadoLibre (MELI) Could Be 42% Below Fair Value After Fresh Investor Backing
MercadoLibre (MELI) is back in focus after renewed interest from high profile investors, linked to its record of steady revenue, logistics and fintech build out, and a recent jump following a cooling US jobs report.
Recent interest in MercadoLibre has arrived alongside a sharp swing in sentiment, with the 7 day share price return of 8.35% and a 1 day move of 0.80% helping the stock recover some ground after a 30 day share price decline of 5.34% and a year to date share price return of 5.11% lower. Total shareholder return over 1 year is 14.09% lower but remains ahead over 3 and 5 years, with gains of 50.55% and 23.34%. This points to long term holders still sitting on sizeable profits even as short term momentum rebuilds following the cooling US jobs report and renewed backing from high profile investors.
Spot opportunities riding similar momentum to MercadoLibre by scanning our hand-picked 20 high quality undiscovered gems that pair solid fundamentals with under-the-radar potential.After that sharp rebound and with MercadoLibre changing hands at about a 21% discount to the average analyst target, as well as a much wider gap to some intrinsic value estimates, the key question is where fair value really sits now as momentum returns.
Most Popular Narrative: 42% Undervalued
Based on the most followed narrative, MercadoLibre is priced well below an estimated fair value of $3,219, compared with the last close near $1,872. The gap rests on how investors treat the cash consumed by its fast growing credit book.
The newer map recognized three creatures living inside one business: the merchant, the money mover, and the lender. Separating them made the economics easier to interrogate. It also exposed a complication behind MercadoLibre’s magnificent growth.
See why 149 investors see MercadoLibre as 42% undervalued.
Result: Fair Value of $3,219 (UNDERVALUED)
Still, the whole MercadoLibre pitch wobbles if credit losses spike or if the fintech funding needs keep swallowing cash flow for longer than the models assume.
Find out about the key risks to this MercadoLibre narrative.
Another View: MercadoLibre Through The P/E Lens
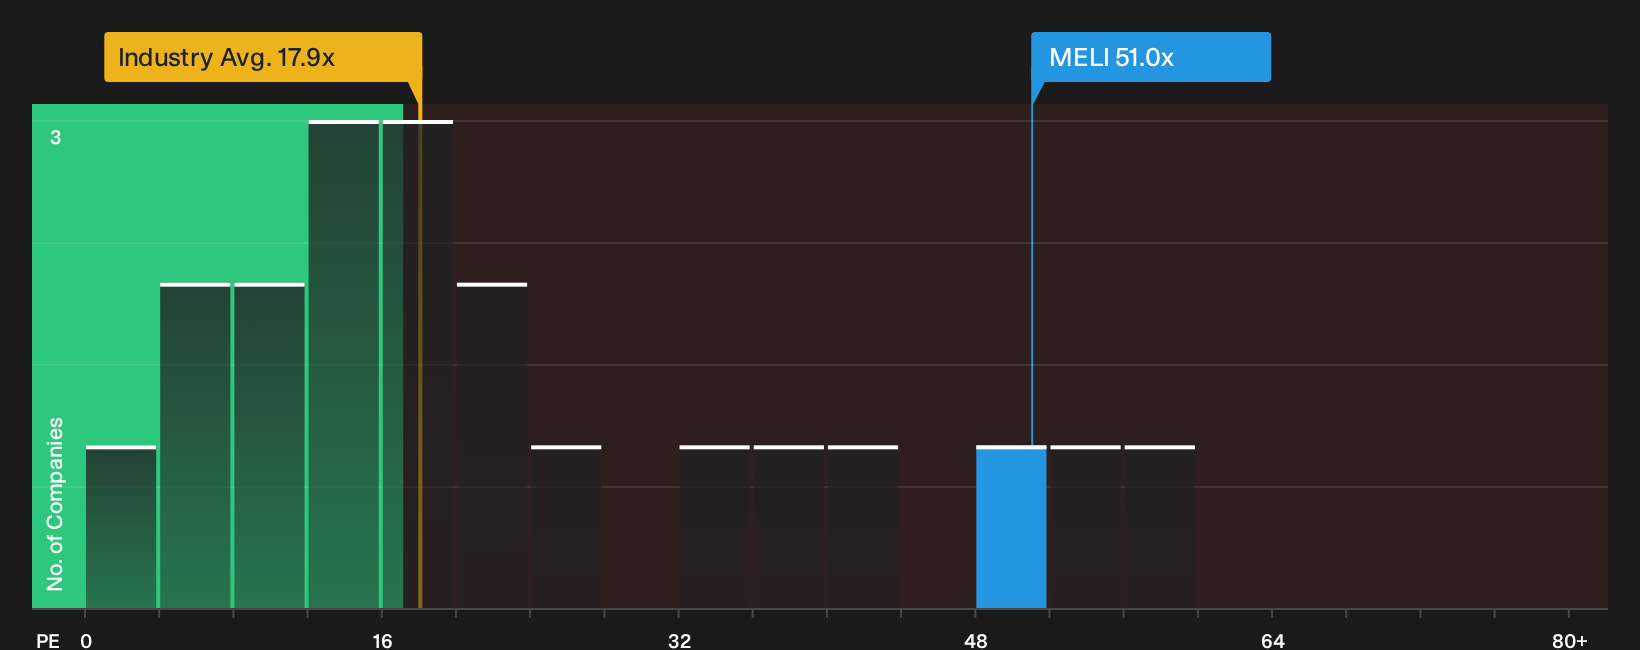
There is a catch. While the SWS fair value work and the most followed narrative frame MercadoLibre as undervalued, the P/E ratio tells a tougher story. The stock trades around 51x earnings, which is far above the global multiline retail average of 17.9x and the peer group near 20.5x, and even exceeds an estimated fair ratio of 32.7x that the market could move toward.
On this yardstick, investors are paying a steep premium that could compress if expectations ease. The question becomes whether you are comfortable owning a business where the growth and profitability narrative needs to keep justifying a much richer multiple than both sector and peers.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mix of optimism and worry around MercadoLibre today. Use the full set of risk and reward flags to pressure test your own thesis with 3 key rewards and 2 important warning signs.
Ready For More Ideas Beyond MercadoLibre?
Do not stop with a single ticker when there are tools that can surface new opportunities tailored to the kind of risk and return profile you actually want.
- Target resilient potential by checking companies that combine quality fundamentals with attractive pricing through the 29 high quality undervalued stocks.
- Strengthen your focus on capital preservation by scanning the 31 resilient stocks with low risk scores for businesses with sturdier profiles and fewer red flags.
- Pursue financial robustness by reviewing a list of solid balance sheet and fundamentals (25 results) that highlights firms with healthier debt and liquidity positions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com