
Is Franklin Electric (FELE) Fully Valued Or Can Its Margin Plan Support More Upside?
Franklin Electric: Business Mix And Scale
Franklin Electric (FELE) generates US$2,211.9m in annual revenue across water systems, energy systems, and distribution, giving investors a mid cap industrial focused on pumps, motors, controls, and related infrastructure equipment.
The water systems operation is the largest contributor, with US$1,304.9m in sales from groundwater, water transfer, wastewater products, and electronic drives that protect equipment from issues such as surges, over-heating, and dry wells.
Energy systems add US$306.6m through pumps, motors, piping, vapor recovery components, monitoring devices, and power reliability equipment used across utilities, rail, hydroelectric, telecom, and data center infrastructure.
The distribution arm records US$730.8m in revenue and focuses on selling to wholesale and specialty distributors, providing presale support and specifications for installing contractors across residential, agricultural, municipal, industrial, and petroleum markets.
Franklin Electric’s share price closed at US$97.59 after a small daily pullback of 1.67%, while the 7 day share price return of 1.77% contrasts with a softer 90 day share price return that is down 4.03%.
Total shareholder return has been steadier, with a 1 year gain of 4.17%, building to 11.54% over 3 years and 26.39% across 5 years, which indicates gradual value creation rather than fast momentum.
Scan beyond Franklin Electric and compare it with a hand picked 43 power grid technology and infrastructure stocks that are also tied to critical water, energy, and infrastructure spending.
Franklin Electric’s mix of steady shareholder returns and a modest pullback in the share price sets up a clear tension. The key question is whether the current valuation still leaves enough upside to compensate for the risks from here.
Most Popular Narrative: 18% Undervalued
Franklin Electric’s most followed narrative pegs fair value at $118.50, comfortably above the last close at $97.59, which puts the focus squarely on whether execution can close that gap.
The Value Acceleration Office and broader supply chain and restructuring efforts, which target more than $15 million of productivity in 2026 and over 100 basis points of annual margin uplift when fully ramped, are designed to support higher operating margins and earnings even if top line growth is moderate.
See why 2 investors see Franklin Electric as 18% undervalued.
Result: Fair Value of $118.50 (UNDERVALUED)
Still, the Franklin Electric story can be knocked off course if weakness in regions like Latin America persists or if higher tariffs squeeze already tight margins.
Find out about the key risks to this Franklin Electric narrative.
Another View On Franklin Electric’s Valuation
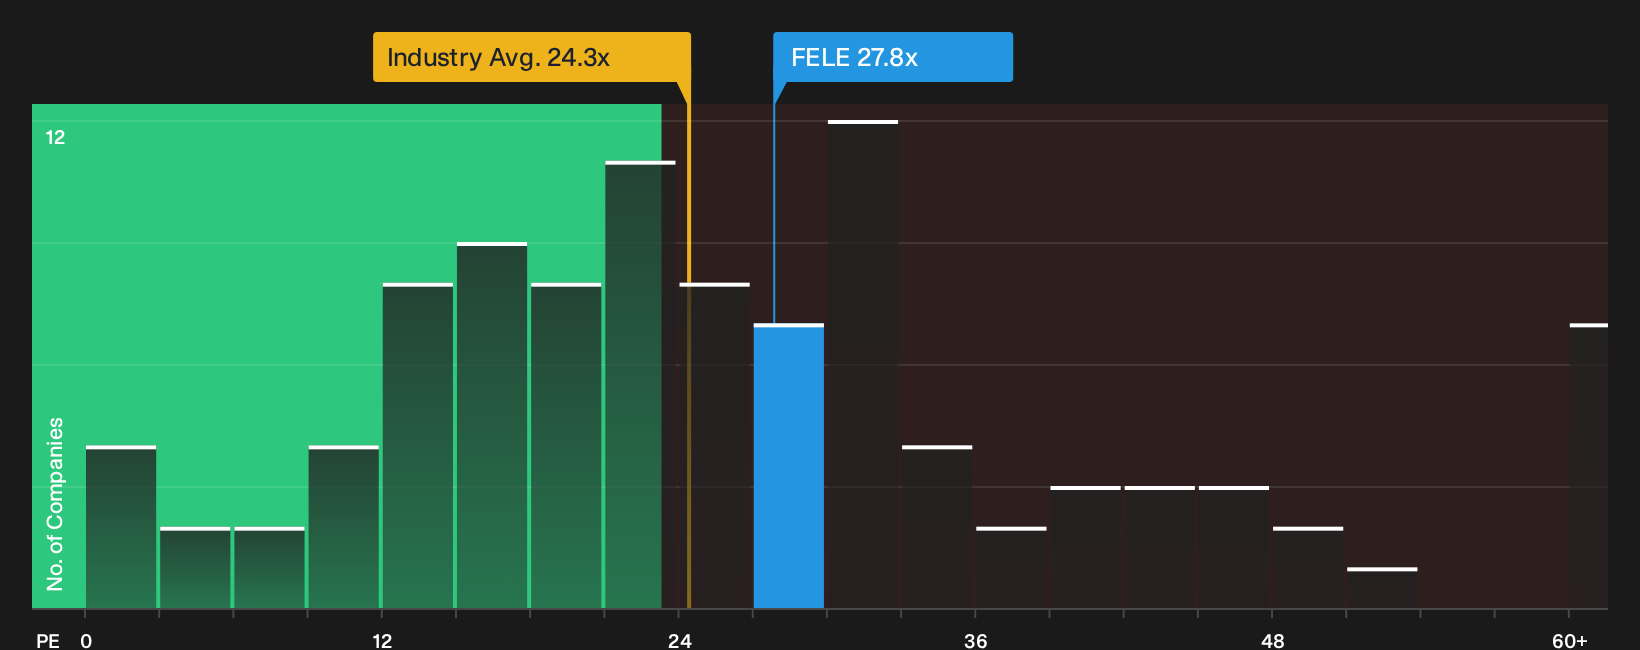
The bullish story around Franklin Electric leans heavily on fair value estimates, yet the market is currently charging a premium P/E of 27.8x. That compares with 25x for the US Machinery group and a fair ratio of 26.2x, which points to a richer entry point and raises the question of how much good news is already priced in.
For a closer look at how this pricing gap stacks up against peers and the fair ratio the market could move toward, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Franklin Electric’s value story are obvious, so move quickly, study the numbers and sentiment yourself, then weigh the 3 key rewards and 1 important warning sign.
Looking for more Franklin Electric style investment ideas?
If Franklin Electric has sharpened your focus on quality, do not stop here. Put a shortlist of fresh opportunities on your radar before other investors move first.
- Target strong value potential by scanning a curated set of companies on the 29 high quality undervalued stocks.
- Prioritise resilience and sleep-better-at-night positions by reviewing the 31 resilient stocks with low risk scores.
- Hunt for future leaders hiding in plain sight by checking the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com