
Proto Labs (PRLB) Could Be 2% Undervalued As Momentum Tests Fair Value
Proto Labs (PRLB), a digital manufacturing specialist for custom parts, has drawn fresh attention after recent share performance data highlighted double digit returns over the past month and over the past three months.
At a latest share price of US$93.27, Proto Labs has pulled back over the past week but still carries strong momentum. The 30 day share price return of 14.53% builds on a 90 day gain of 24.06%, and a 1 year total shareholder return of 85.50% that dwarfs its 5 year total shareholder return of 39.21%.
Scan other manufacturing and industrial tech stocks showing similar momentum to Proto Labs by checking the hand picked list of solid balance sheet and fundamentals (25 results) that combine resilience with recent strength.
Proto Labs now combines a strong digital manufacturing franchise with a share price that has already run hard. The real tension is whether that recent surge still leaves enough value on the table.
Most Popular Narrative: 2% Undervalued
Proto Labs is trading at $93.27 against a widely followed fair value estimate of $95.50. The current quote sits slightly below that narrative anchor while still reflecting a lot of optimism.
The main thing that has to go right is execution on the shift from prototyping toward higher margin production programs and turning the European restructuring from a profitability drag into a consistent contributor, while also investing in physical AI capabilities.
The current valuation and high P/E ratio indicate that the share price already reflects expectations for sustained revenue growth, margin improvement, and successful delivery on the transformation under way.
See why 4 investors see Proto Labs as 2% undervalued.
Result: Fair Value of $95.50 (UNDERVALUED)
Still, the Proto Labs narrative weakens quickly if European restructuring stalls again or if ongoing softness in 3D printing continues to weigh on overall profitability.
Find out about the key risks to this Proto Labs narrative.
Another View On Proto Labs Valuation
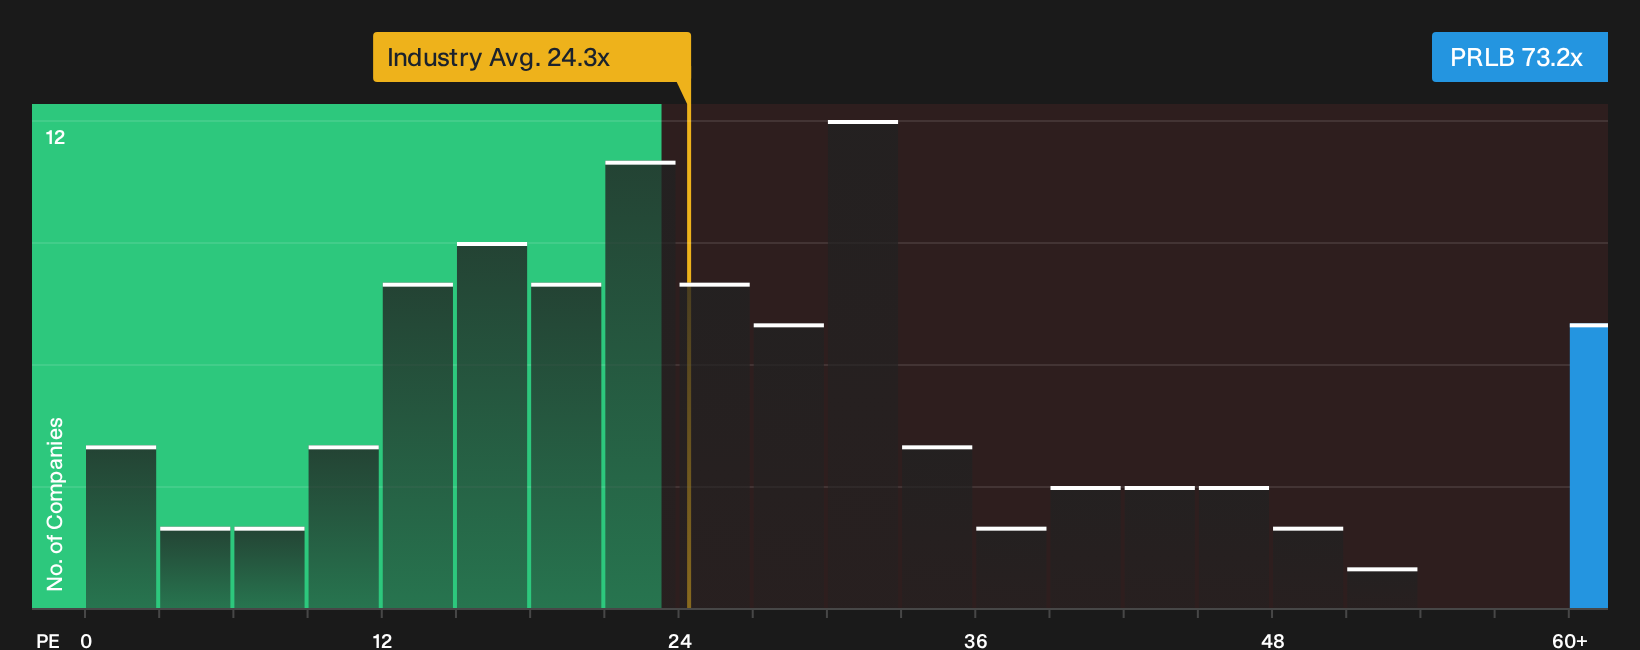
The analyst narrative pegs Proto Labs near fair value around $95.50. The simple P/E check tells a very different story. At 73.2x earnings against a US Machinery peer average of 25x and a fair ratio of 26.9x, the stock trades on a much richer multiple than both sector and model suggest.
That kind of gap tends to compress at some point, either through earnings catching up or the share price cooling. The question for investors is whether Proto Labs can grow into that valuation quickly enough to keep the risk reward balance attractive.
For a closer look at how this earnings multiple stacks up against peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Momentum and valuation signals around Proto Labs are mixed, so do not let this article be the only input into your decision. Move quickly to inspect the underlying drivers yourself and weigh that optimism against the risks highlighted in the 2 key rewards.
Looking for more investment ideas beyond Proto Labs?
If Proto Labs has your attention, do not stop with a single ticker. Cast the net wider and let data rich screeners surface opportunities you might otherwise miss.
- Hunt for quality at a discount by scanning the 29 high quality undervalued stocks that line up strong fundamentals with appealing pricing.
- Secure your future income stream by reviewing the 8 dividend fortresses that focus on firms offering higher yields with robust payout support.
- Reduce portfolio stress by filtering candidates through the 31 resilient stocks with low risk scores that highlight businesses with lower risk scores and steadier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com