
Is AI Platform Upgrade Altering The Investment Case For S&P Global Stock?
- S&P Global recently updated its Capital IQ Pro platform, expanding ChatIQ conversational AI across research, modeling, presentation workflows and multi asset data coverage for financial professionals.
- The deeper AI integration brings modeling, screening, charting and portfolio insights into a single workflow, which can materially cut manual data work and reshape how clients use S&P Global for daily decision making.
- This article examines how S&P Global's investment narrative is influenced by Capital IQ Pro's expanded ChatIQ AI workflow integration.
S&P Global Investment Narrative Recap
To own S&P Global, you need to believe this is more than a ratings franchise. The thesis leans on steady fee based businesses across data, indices, energy and credit that can compound through new products and AI led workflows. The biggest near term swing factor still sits in Ratings activity around the multi trillion dollar maturity wall and how refinancing appetite holds up.
That is where the latest Capital IQ Pro and ChatIQ rollout matters operationally but does not rewrite the near term risk. It mainly targets productivity and data stickiness rather than issuance volume. The short term upside catalyst is better issuance trends. The main threat remains any reset in expectations for organic growth and margins.
The Capital IQ Pro upgrade with deeper ChatIQ is the most relevant recent announcement here. It ties directly to the catalyst around new product contribution and AI driven distribution, where management tracks metrics like the Vitality Index and usage of APIs and LLM access. The goal is a platform that keeps analysts inside the S&P Global ecosystem for research, modeling and presentation work.
For you as a shareholder, the question is whether this build out can offset volatility in Ratings driven revenue and support the mid to high single digit organic growth narrative. Execution risk sits in uptake and pricing, especially in areas like private markets, fixed income and portfolio tools. Dividend affirmations provide capital return, but operational delivery on AI workflows remains central to the story.
What The Current S&P Global Forecasts Assume
Analyst models around S&P Global do not just lean on AI hype. They are built on a fairly specific set of revenue and earnings projections tied to those workflow upgrades. Consensus currently factors in revenue growth of about 2.3% per year over the next three years, alongside a move in profit margins from 30.5% today to 34.8% in that same timeframe. That backdrop frames how much financial impact the broader Capital IQ Pro and ChatIQ rollout is expected to carry.
Earnings assumptions are equally clear. Forecasts today point to profit of US$4.9b rising to US$6.0b by 2029, with the analyst group broadly aligned on that endpoint. The shift from US$4.9b to US$6.0b implies an increase of roughly US$1.1b in earnings, which helps underpin the current narrative that S&P Global can keep funding AI heavy product development while also supporting capital returns. The step up in margins in those models effectively assumes that AI driven workflows and data products can be monetised in a way that more than covers their cost.
The valuation overlay then connects those operating forecasts back to the share price. On the current consensus view, S&P Global would be trading on a P/E of 29.8x in 2029, compared with about 24.2x today and below the 39.6x multiple quoted for the wider US Capital Markets industry. That gap gives you a reference point for how much AI linked execution, steady fee income and Ratings resilience would need to be reflected in the multiple for the analyst case to hold together.
All of this is filtered through a discount rate of roughly 8.1% to 8.13%, which is what the Simply Wall St report uses to translate those 2029 cash flows back to today. That rate acts as a hurdle the future earnings stream needs to clear to justify the current targets. It also gives you a single lever to flex in your own model if you see the risk in S&P Global's AI heavy roadmap, or its Ratings cyclicality, as higher or lower than the analyst group does.
S&P Global's narrative projects US$17.3b revenue and US$6.0b earnings by 2029. This rests on 2.3% yearly revenue growth and an earnings increase of about US$1.1b from US$4.9b today.
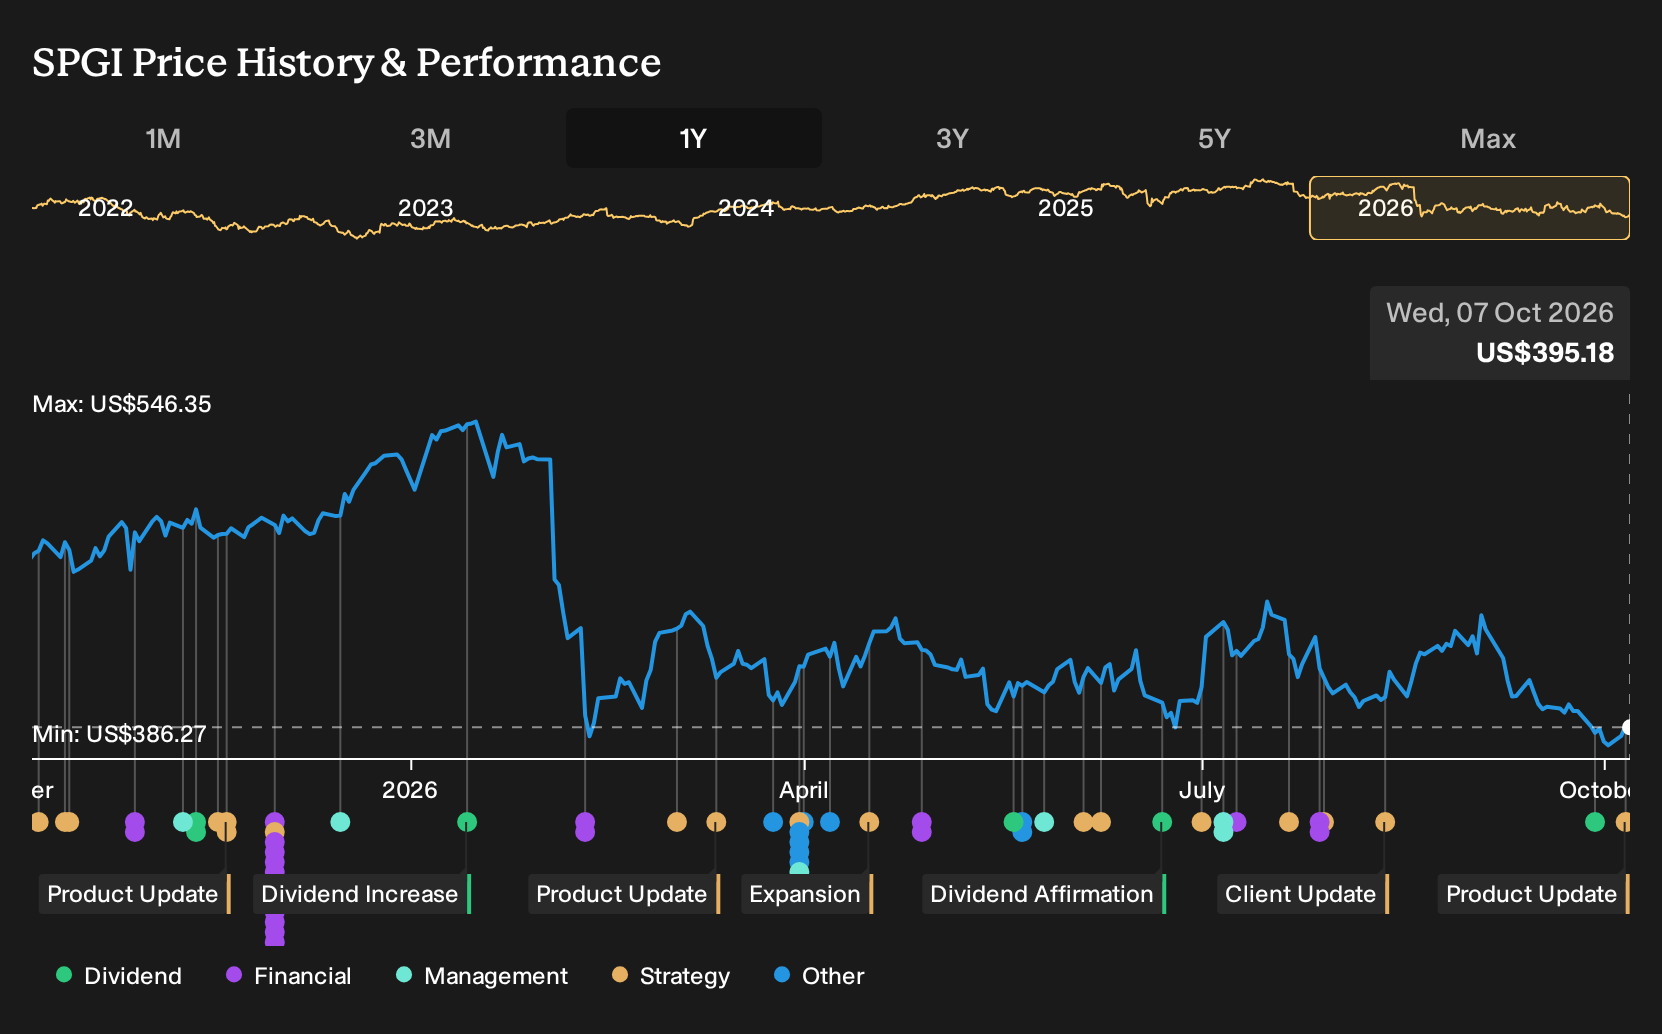
Uncover how S&P Global's fair value indicates a 32% potential upside to its current price, which could narrow quickly if S&P Global executes on its AI workflow plans.
Exploring Other Perspectives
Twelve fair value estimates from the Simply Wall St Community span roughly US$377 to US$520 per share, with opinions clustering in several buckets rather than around a single midpoint. That spread meets a fresh catalyst in S&P Global's expanded Capital IQ Pro and ChatIQ rollout, plus the recent dividend affirmation, giving you multiple angles to test and compare. Investor opinions can differ widely, so it makes sense to review these community views alongside your own read on Ratings cyclicality and the AI workflow opportunity.
Explore 11 other S&P Global fair value estimates, including one that suggests it could be worth just $376.93.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your S&P Global research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for S&P Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate S&P Global's overall financial health at a glance.
Looking For More Investment Ideas Beyond S&P Global?
If you want to test your thesis on S&P Global against other opportunities, the Simply Wall St Screener lets you quickly line up peers with similar qualities or very different risk profiles. That helps you see whether the trade offs you are accepting here also apply elsewhere, or if there are cleaner ways to express the same investment theme.
- For investors hunting for mispriced quality, compare S&P Global with a broader field of potentially underappreciated businesses through the 29 high quality undervalued stocks.
- If resilience and balance sheet strength matter most to you, you can stress test your portfolio ideas against the list of solid balance sheet and fundamentals (25 results) that screens for sturdier finances.
- Income focused readers can round out their watchlist by checking the 8 dividend fortresses that concentrates on higher yielding payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com