
Pigeon (TSE:7956) Could Be 37% Below Fair Value Despite Its Pricey P/E
Pigeon (TSE:7956) has drawn fresh attention after its recent share move, with the stock closing at ¥2,066.5 and showing mixed short term returns over the past week, month, and past 3 months.
Recent moves sit on top of a much stronger run, with Pigeon’s share price showing a 28.51% year to date return. The 1 year total shareholder return of 22.04% and 3 year total shareholder return of 44.70% suggest momentum has been building rather than fading.
Scan beyond Pigeon’s recent momentum and shortlist other consumer-focused stocks showing strong price action and solid fundamentals using the curated 75 high quality undiscovered gems.
Pigeon now trades well above its recent lows, with solid shareholder returns already on the board. The real issue is whether that recent repricing still leaves enough upside to justify the risk from here.
Preferred P/E Multiple of 26.9x: Is it justified?
Pigeon now trades at a P/E of 26.9x, which means the market is paying a higher price for each unit of current earnings compared with several reference points.
The P/E ratio compares the share price with earnings per share and is a common way investors gauge how much optimism is baked into a consumer-focused stock. For a business like Pigeon, which sells baby care and related products globally, a richer P/E often reflects expectations for steady demand and resilience in cash generation rather than rapid expansion.
Analysts currently expect Pigeon's earnings to grow around 10% per year, which is slightly ahead of the 9.5% forecast for the broader JP market. That outlook sits alongside an internal assessment that Pigeon is trading at a 37.4% discount to an estimated fair value and at ¥2,066.5 compared with a DCF fair value estimate of ¥3,301.5 from the SWS DCF model. This implies the market is cautious on the pace or sustainability of those projected cash flows.
Relative to peers, the gap is clear. Pigeon's 26.9x P/E is well above the Asian Household Products industry average of 16.6x and higher than a peer average of 19.8x. It is also above an estimated fair P/E of 22.8x that the market could move toward if sentiment cools.
Explore the SWS fair ratio for Pigeon.
Result: Price-to-earnings of 26.9x (OVERVALUED)
Still, the narrative can quickly shift if Pigeon underdelivers on earnings growth expectations or if consumer demand for its baby care products softens.
Find out about the key risks to this Pigeon narrative.
Another View on Pigeon’s Valuation
The P/E looks stretched, yet the SWS DCF model points the other way. On that framework, Pigeon at ¥2,066.5 is trading at a 37.4% discount to an estimated future cash flow value of ¥3,301.5. That split raises a simple question: Which signal should matter more to you right now?
Look into how the SWS DCF model arrives at its fair value.
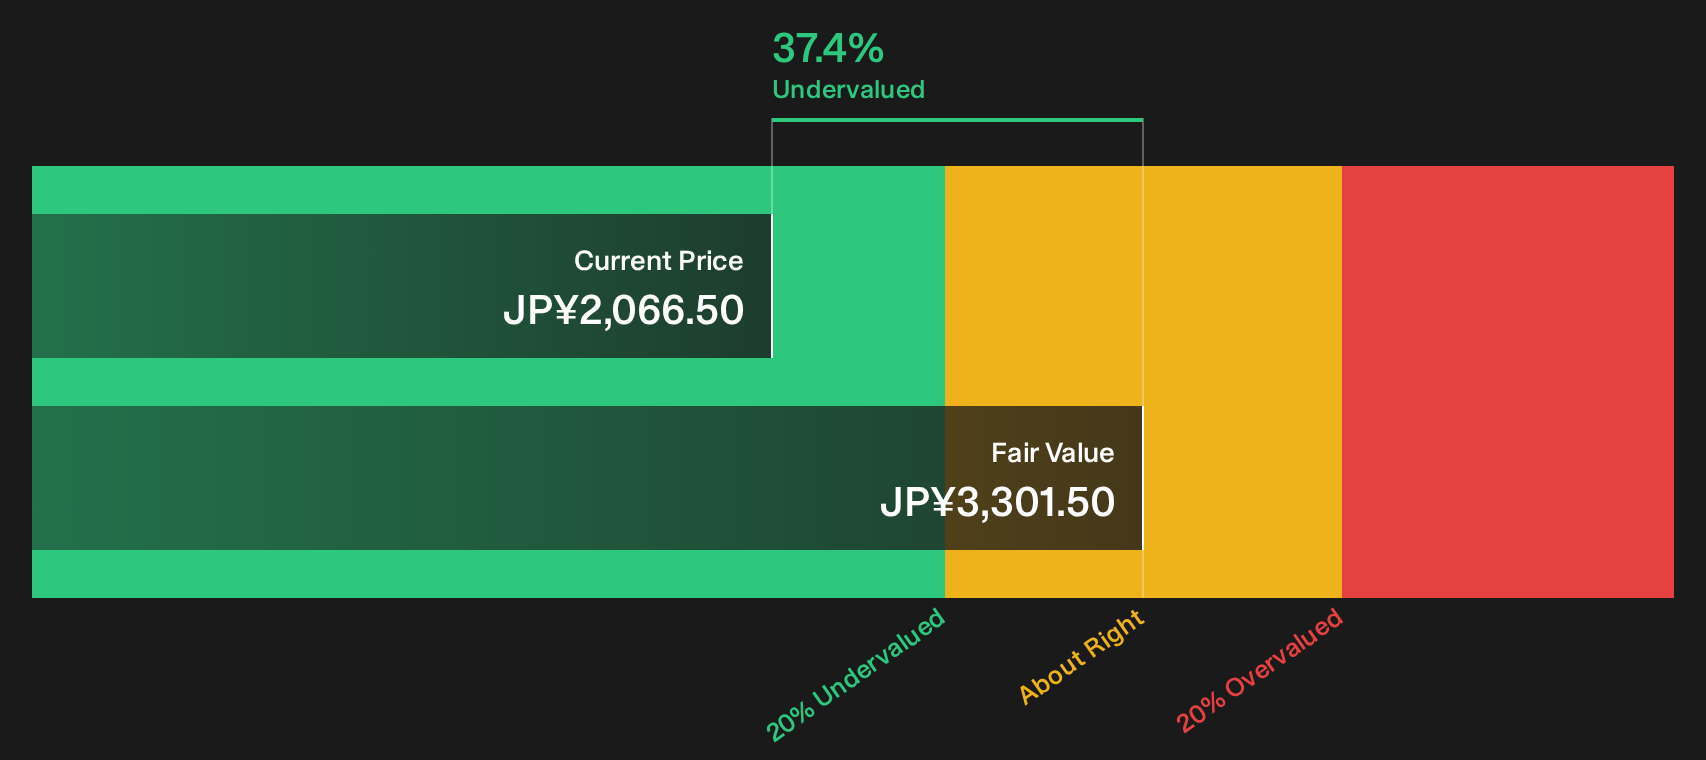
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pigeon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Pigeon’s valuation and risk-reward profile can feel uncomfortable, so move quickly, review the full picture, and weigh the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Pigeon?
Do not stop with Pigeon. The real edge comes from lining it up against other opportunities and seeing which ones truly earn a place in your portfolio.
- Target dependable cash generators by scanning companies with strong income potential and resilient payouts through the 32 dividend fortresses.
- Hunt for mispriced quality by working through the curated 14 high quality undervalued stocks that blend solid balance sheets with healthy cash flows.
- Prioritise resilience by tracking companies with steadier risk profiles using the focused 22 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com