
Doximity (DOCS) Faces Lawsuits As Fair Value Stays In Focus
Multiple law firms have launched securities class actions against Doximity (DOCS), accusing the healthcare platform of misleading investors about its Newsfeed product, broader business health, and growth prospects during the defined class period.
Doximity’s share price has slipped over the past week, with a 7 day share price return showing a 2.29% decline. The 90 day share price return of 25.81% indicates that momentum had been building before the lawsuits, while the 1 year total shareholder return of 62.34% decline highlights how sentiment has shifted over a longer horizon.
Spot fresh opportunities beyond Doximity by scanning our hand picked 20 high quality undiscovered gems with strong fundamentals that have not yet attracted broad market attention.Doximity now trades only a little below the average analyst target and at a larger discount to some intrinsic value estimates. After the lawsuits and recent swings, where does a fair price really land within that range?
Most Popular Narrative: 18% Undervalued
Doximity’s most followed narrative pegs fair value at $33.70, above the recent $27.69 close, which puts the lawsuits against a backdrop of perceived undervaluation.
What I like about Doximity is that there really is a very high viewership / user base of active practicing Physicians in the US and that is not invaluable and definitely could be monetized perhaps more efficiently. I also think that Doximity offers a lot of interesting tools for Physicians a lot of which you’re free and really marketed towards I think Physicians who are more in private practice. It’s a little bit unclear how much value that provides given that most Physicians and practitioners these days are employed and not a private practice.
See why 10 investors see Doximity as 18% undervalued.
According to Dc12, the strength of Doximity’s network among practicing physicians, along with growing engagement with its clinical AI tools, is central to the view that the current share price does not fully reflect its platform. That perspective leans heavily on the reach of the user base and the perceived quality of new products rather than short term share price moves.
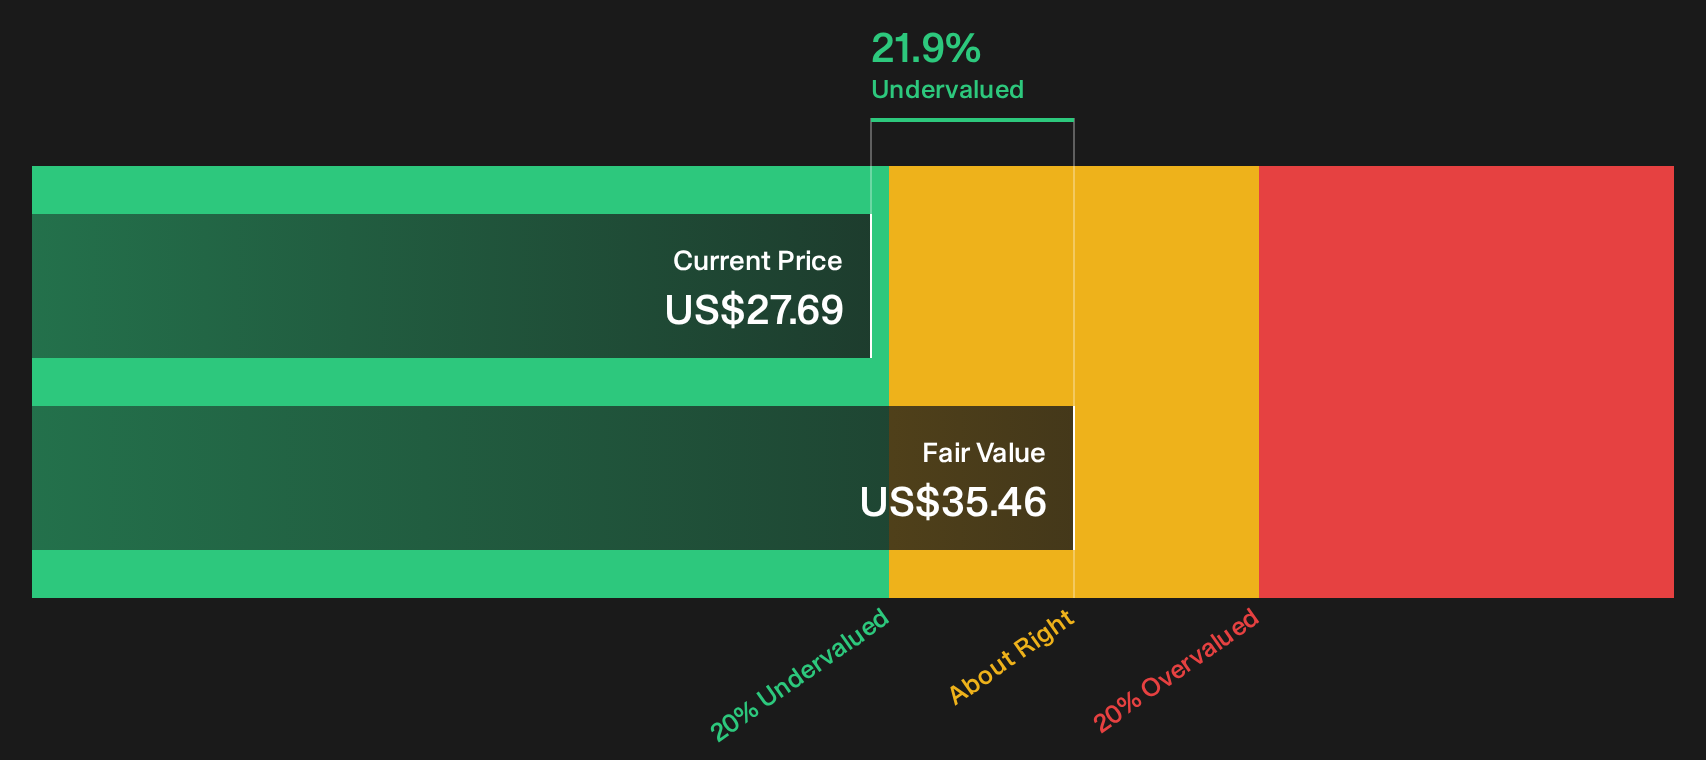
That narrative implies a discount of about 18% to the $33.70 fair value, relative to the recent close. It sits alongside Simply Wall St’s own future cash flow estimate of $35.46 per share, which is higher than both the user view and the market price.
Result: Fair Value of $33.70 (UNDERVALUED)
Still, the lawsuits over Doximity’s disclosures and any shift in physician engagement with its tools could pressure both sentiment and the current valuation narrative.
Find out about the key risks to this Doximity narrative.
Another View On Doximity’s Valuation
The first narrative leans on user engagement and a fair value of $33.70 for Doximity. Our DCF model paints a similar picture, with a future cash flow estimate of $35.46 per share, which also points to the stock trading at a discount. Could both be leaning on assumptions that prove too generous?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed on Doximity after all this. If you want to move quickly and ground your own view in the numbers and narratives, start by weighing the balance of 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Doximity?
Do not stop with Doximity. Use the screener to hunt for fresh opportunities, compare business quality, and build a watchlist that reflects how you want to invest.
- Target resilient balance sheets and steady fundamentals by running a focused search through our list of solid balance sheet and fundamentals (25 results).
- Spot potential value opportunities before they hit everyone’s radar by scanning the 29 high quality undervalued stocks.
- Prioritise stability and smaller drawdowns by filtering for companies in the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com