
Capital Southwest (CSWC) Trades Below Fair Value, Is It Still A Bargain?
Capital Southwest (CSWC) is drawing attention after its shares closed at US$23.49, with recent performance mixing short term declines and longer term gains that have investors reassessing how this business development company fits into portfolios.
Recent trading has been choppy, with Capital Southwest’s 1-day share price return declining 0.76% and its 30-day share price return down 4.43%, while the year-to-date share price return of 5.38% and 1-year total shareholder return of 27.27% point to momentum that has softened recently rather than fully reversed.
Scan how Capital Southwest compares with a hand picked group of income focused lenders and other business development companies using the 8 dividend fortresses as a starting list.
Capital Southwest now trades at a discount to both analyst targets and an estimated fair value, yet recent share price softness hints at lingering market caution. Is that hesitation supported by the numbers investors are paying for today?
Most Popular Narrative: 7% Undervalued
The most followed narrative on Capital Southwest pegs fair value at $25.30, modestly above the recent $23.49 close. This frames today’s discount as relatively narrow rather than distressed.
Robust private equity sponsor relationships and rising lower middle market deal screens, with management reviewing roughly 1,300 opportunities over the last 12 months and committing US$762 million in FY26 plus US$222 million in Q1 FY27, support the view that Capital Southwest can keep adding income producing assets that underpin revenue and earnings.
See why 37 investors see Capital Southwest as 7% undervalued.
Result: Fair Value of $25.30 (UNDERVALUED)
Still, the Capital Southwest story can unravel if spread compression from rival lenders continues to squeeze net interest margins, or if ongoing share issuance dilutes per share earnings power.
Find out about the key risks to this Capital Southwest narrative.
Another View: Valuing Capital Southwest By Earnings
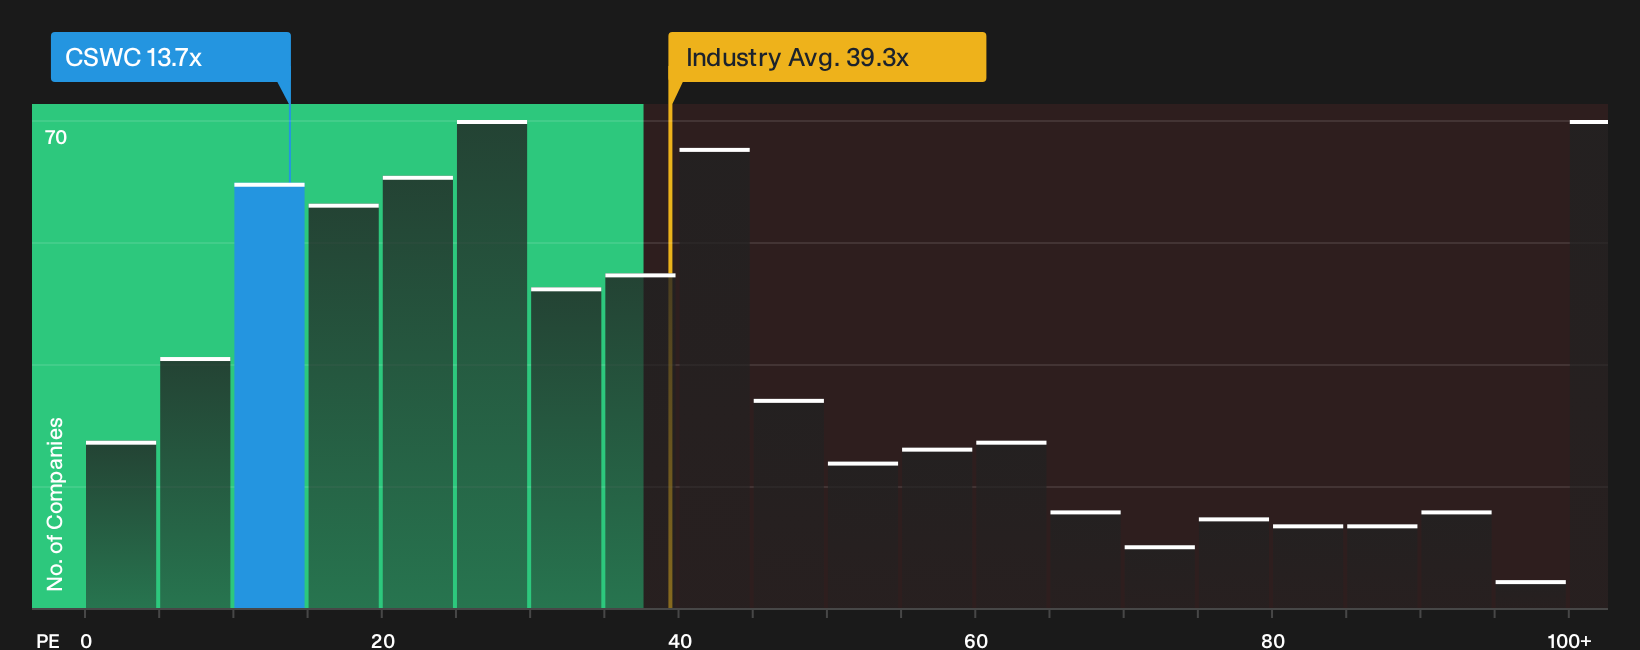
The SWS fair ratio highlights a different angle on Capital Southwest. The shares trade on a P/E of 13.7x, compared with a fair ratio of 11.7x, a peer average of 12.2x and a much higher 39.7x for the broader US Capital Markets group. That mix points to clear valuation risk if sentiment cools, even with an attractive sector discount in play, so which reference point do you treat as your anchor?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There can be mixed signals around Capital Southwest, which may create plenty of noise. It can be useful to move quickly to test the valuation, dividend profile, and risk balance for yourself, then weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Capital Southwest?
If Capital Southwest has you rethinking income and valuation, do not stop there. Broader opportunity often sits just outside the stocks already on your radar.
- Target potential mispricing by scanning companies that combine strong fundamentals with discounted valuations using the 29 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with cleaner finances through the list of solid balance sheet and fundamentals (25 results).
- Spot tomorrow’s potential winners early by filtering for financially sound smaller players via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com