
Is Société BIC (ENXTPA:BB) Fairly Valued On Its Premium Growth Narrative?
Société BIC (ENXTPA:BB) has drawn fresh attention after recent price moves left the shares down about 3% over the past month, while the past 3 months show a gain of nearly 9%.
For context, Société BIC’s recent softness comes after a strong run, with the share price still showing a year to date return of 25.58% and a 1 year total shareholder return of 26.55% at a current price of €64.8. The 5 year total shareholder return of 70.15% points to longer term holders having been rewarded even as near term momentum has cooled.
Compare Société BIC’s recent swing with other companies showing a similar mix of momentum and longer term resilience by scanning our hand picked 182 high quality undervalued stocks today.
Société BIC now trades only slightly below analyst targets, yet well under some intrinsic value estimates. After that recent pullback, how far does the current €64.8 price actually sit from fair value?
Most Popular Narrative: 5% Undervalued
The most followed storyline on Société BIC values the shares at about €68.47, a touch above the latest €64.8 close, which leaves the stock framed as modestly undervalued while still close to analyst targets.
Geographic expansion and distribution gains in high-growth regions (Africa, Latin America, Middle East) are beginning to contribute positively, with commercial execution and market share wins in markets like Nigeria, Morocco, and Brazil, positioning BIC to benefit from population growth and rising literacy rates as drivers of future revenue growth.
The successful integration and double-digit growth of newly acquired or premium brands such as Tangle Teezer (including ongoing product and category extensions) shows BIC's ability to diversify its product mix and capture value-focused and premium-driven consumer segments, supporting both top-line growth and incremental margin improvement over time.
See why 18 investors see Société BIC as 5% undervalued.
The fair value in this narrative is built using a 6.59% discount rate and assumes annual revenue growth of about 2.24%, a profit margin near 9.96%, and a future P/E of roughly 15.24x. That combination produces an estimated fair value of €68.47, compared with both the current market price of €64.8 and the same level used as the analyst consensus target.
Analysts in this framework also see earnings rising to €218.4m by around 2029, with earnings per share of €5.43 and a slightly lower share count as buybacks reduce outstanding stock by an assumed 0.32% each year in the near term. The required P/E multiple of 15.2x on those earnings is in line with the current 15.2x figure cited for the wider GB Commercial Services group, which keeps the valuation logic anchored to an established sector reference rather than an unusually high premium.
These narrative assumptions sit alongside Simply Wall St's own DCF output, which points to a future cash flow value of €141.24 per share at the same €64.8 spot price. That gap is much wider than the 5.4% discount implied by the narrative fair value, so readers may want to weigh how confident they feel about the long term cash generation profile behind Société BIC before leaning on either framework.
Result: Fair Value of €68.47 (UNDERVALUED)
Still, parts of the Société BIC story can break the thesis if they worsen, particularly shrinking demand for traditional stationery and pressure from low cost and private label competitors.
Find out about the key risks to this Société BIC narrative.
Another View On Société BIC’s Valuation
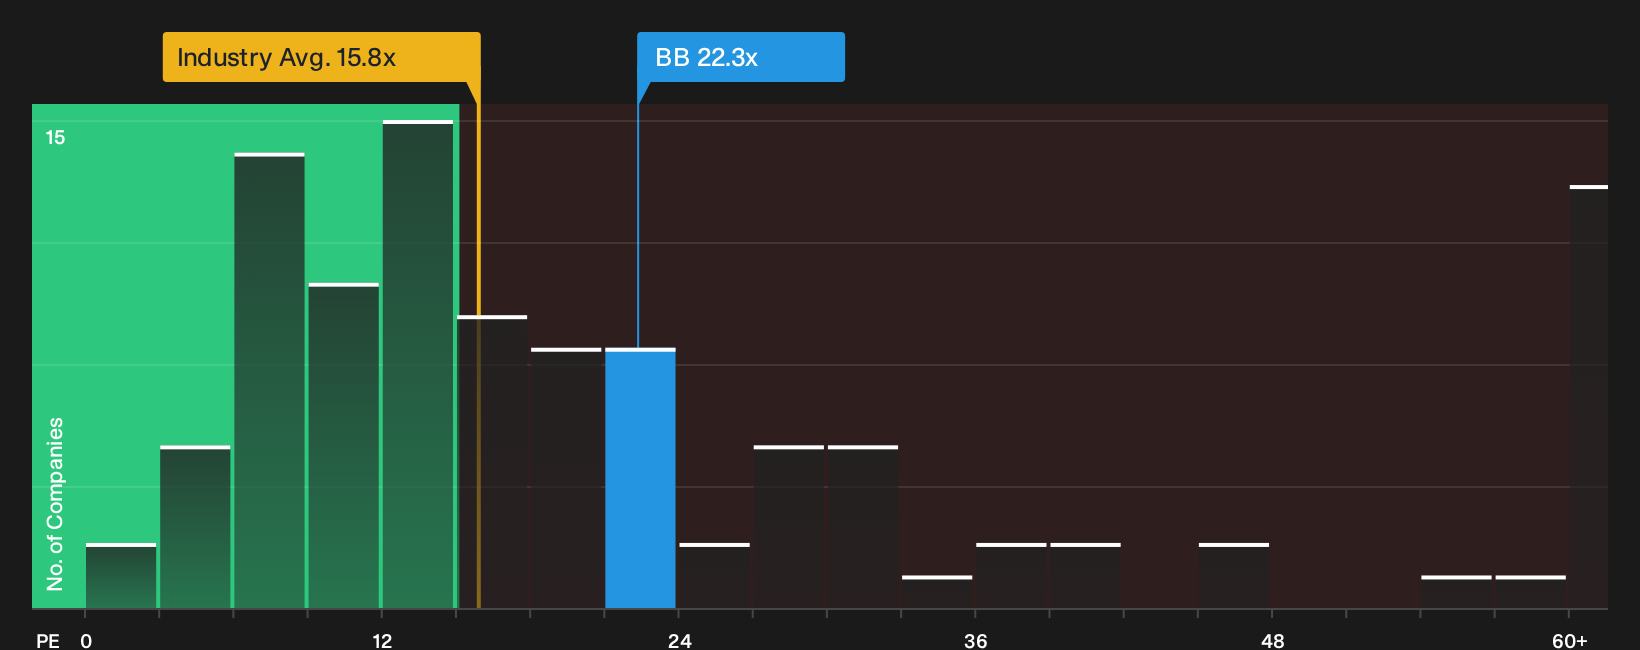
While the fair value narrative and SWS DCF model both point to Société BIC looking cheap around €64.8, earnings multiples paint a different picture. The current P/E of 22.3x is higher than peers at 12.8x, and above a fair ratio of 17.3x, which suggests investors are already paying up. Which signal matters more for you?
To see how this richer earnings multiple fits with cash flow based pricing, and where the market could shift next, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Société BIC’s valuation and future profile can feel confusing, so move quickly, review the data yourself, and consider both sides of the story using our breakdown of 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Société BIC?
If Société BIC has sharpened your interest, do not stop here. Broader research across quality watchlists can reveal opportunities that fit your exact style.
- Target resilient balance sheets and steady fundamentals by checking the list of solid balance sheet and fundamentals (206 results) that filters for financial strength across markets.
- Hunt for pricing gaps where quality and value meet by scanning the 182 high quality undervalued stocks that highlights stocks with supportive cash flow and fundamentals.
- Zero in on reliable income ideas by reviewing the 224 dividend fortresses that focuses on higher yielding companies with robust payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com