
Entegris (ENTG) Could Be 4% Undervalued On Flat Sales And Rich P E
Mixed Signals Around Recent Quarterly Results
Entegris (ENTG) has drawn fresh attention after recent quarterly results tied to advanced nodes, high bandwidth memory, and advanced packaging, while flat sales and softer expected demand sharpen investor focus on valuation and cash generation.
Recent trading in Entegris has leaned positive, with a 7-day share price return of 7.96% and a 30-day share price gain of 19.88% helping push the stock to US$166.32. At the same time, the 1-year total shareholder return of 76.50% and 3-year total shareholder return of 72.32% point to momentum that investors are now weighing against concerns about flat sales, limited free cash flow, and a high forward P/E multiple.
Compare Entegris with other advanced manufacturing plays showing strong price momentum and solid fundamentals using our hand picked 92 AI infrastructure stocks.
Bulls point to Entegris riding key semiconductor trends, while bears focus on flat sales, limited free cash flow, and a rich forward P/E. Which side does the current valuation really lean toward?
Most Popular Narrative: 4% Undervalued
Entegris is trading at $166.32 against a narrative fair value of $173.36. This frames the recent rally as only slightly ahead of that widely followed view.
Operational optimization, including the ramp of the KSP Taiwan filtration facility toward breakeven, closures of dilutive sites and a more than 20% increase in factory direct labor to tap existing capacity, is already lifting gross margin and can further support net margin and free cash flow as fixed costs are spread over higher volumes.
See why 13 investors see Entegris as 4% undervalued.
Result: Fair Value of $173.36 (UNDERVALUED)
Still, the Entegris story can crack if high expectations collide with renewed sector volatility, or if flat revenue trends and moderate free cash flow persist longer than analysts model.
Find out about the key risks to this Entegris narrative.
Another View On Entegris Valuation
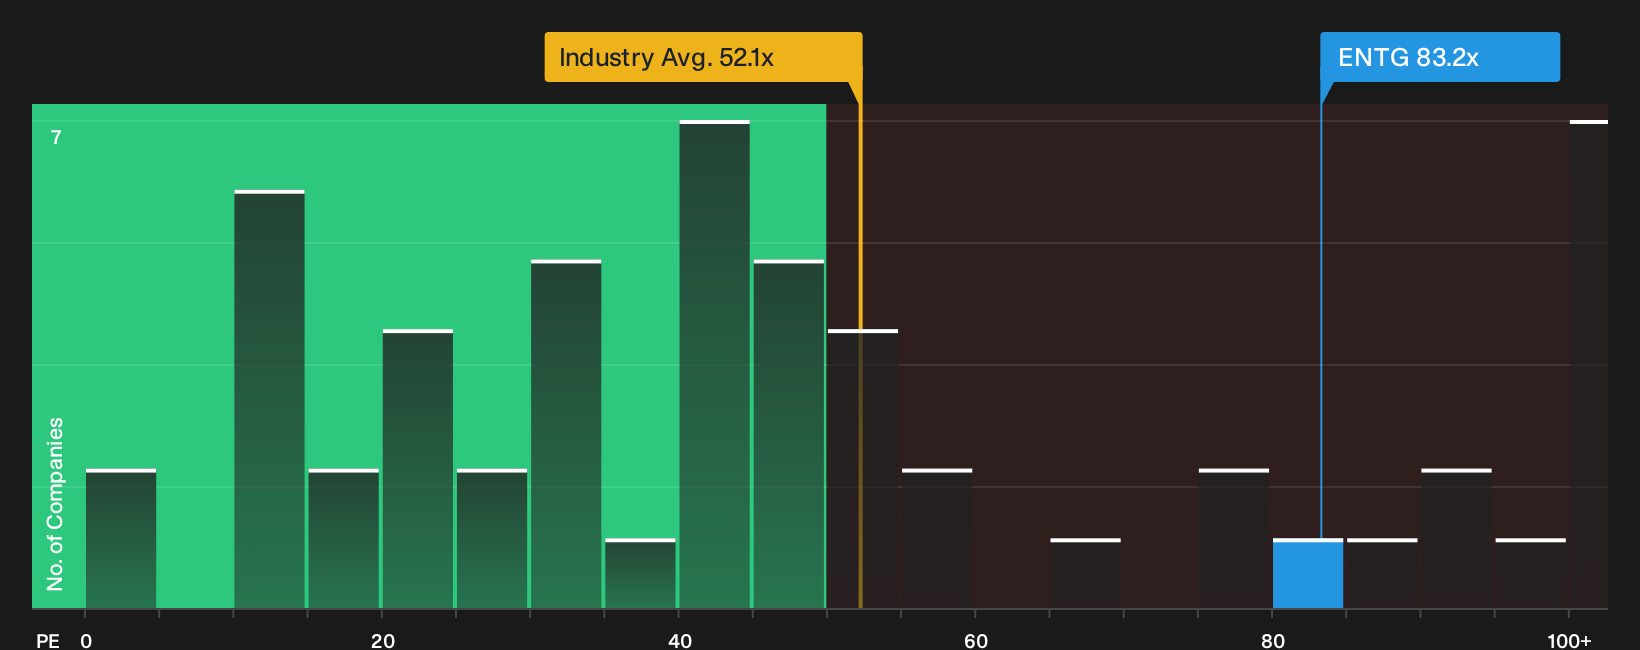
The narrative fair value of $173.36 points to Entegris as modestly undervalued, yet the P/E ratio of 83.2x tells a tougher story. That multiple is well above the estimated fair ratio of 35.1x, the US Semiconductor industry at 53.3x, and the peer average of 56.1x. Such a gap leaves less room if sentiment cools and earnings expectations are reset. How comfortable are you paying this kind of premium?
For a closer look at how these valuation gaps line up with current assumptions, run the numbers in our detailed multiples breakdown, then compare Entegris with other high expectation stocks using the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Entegris valuation and expectations can feel hard to reconcile. Move quickly, review the underlying data, and decide where you land with 1 key reward and 1 important warning sign
Looking For More Investment Ideas Beyond Entegris?
If you only stop at Entegris, you risk missing other opportunities that might fit your goals even better, so use the screener to broaden your field.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results), which keeps financial strength front and center.
- Hunt for potential mispricings by reviewing the 29 high quality undervalued stocks, which could align with stricter value criteria.
- Prioritize income and staying power by comparing payouts and balance sheets through the 8 dividend fortresses, which focuses on higher yielding candidates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com