
How Headquarters Advisory Win At Parsons (PSN) Has Changed Its Investment Story
- Parsons Corporation was selected by Army Contracting Command Rock Island, in coordination with Air Force Civil Engineering Center, to provide Owner’s Advisor support for the progressive design build development of U.S. Space Command’s new headquarters at Redstone Arsenal under an initial US$85 million, 75 month agreement.
- The award places Parsons at the center of one of the Department of War's largest progressive design build efforts. This gives the business a long runway of program and construction management work across planning, design, construction, and operationalization of a 950,000 square foot national security campus.
- We will now look at how Parsons’ investment narrative could be influenced by its long duration Owner’s Advisor role on USSPACECOM headquarters.
Compare Parsons’ long-term federal infrastructure exposure with a curated list of peers by scanning 43 power grid technology and infrastructure stocks, which is tied to major grid, defense, and mission-critical projects.
Parsons Investment Narrative Recap
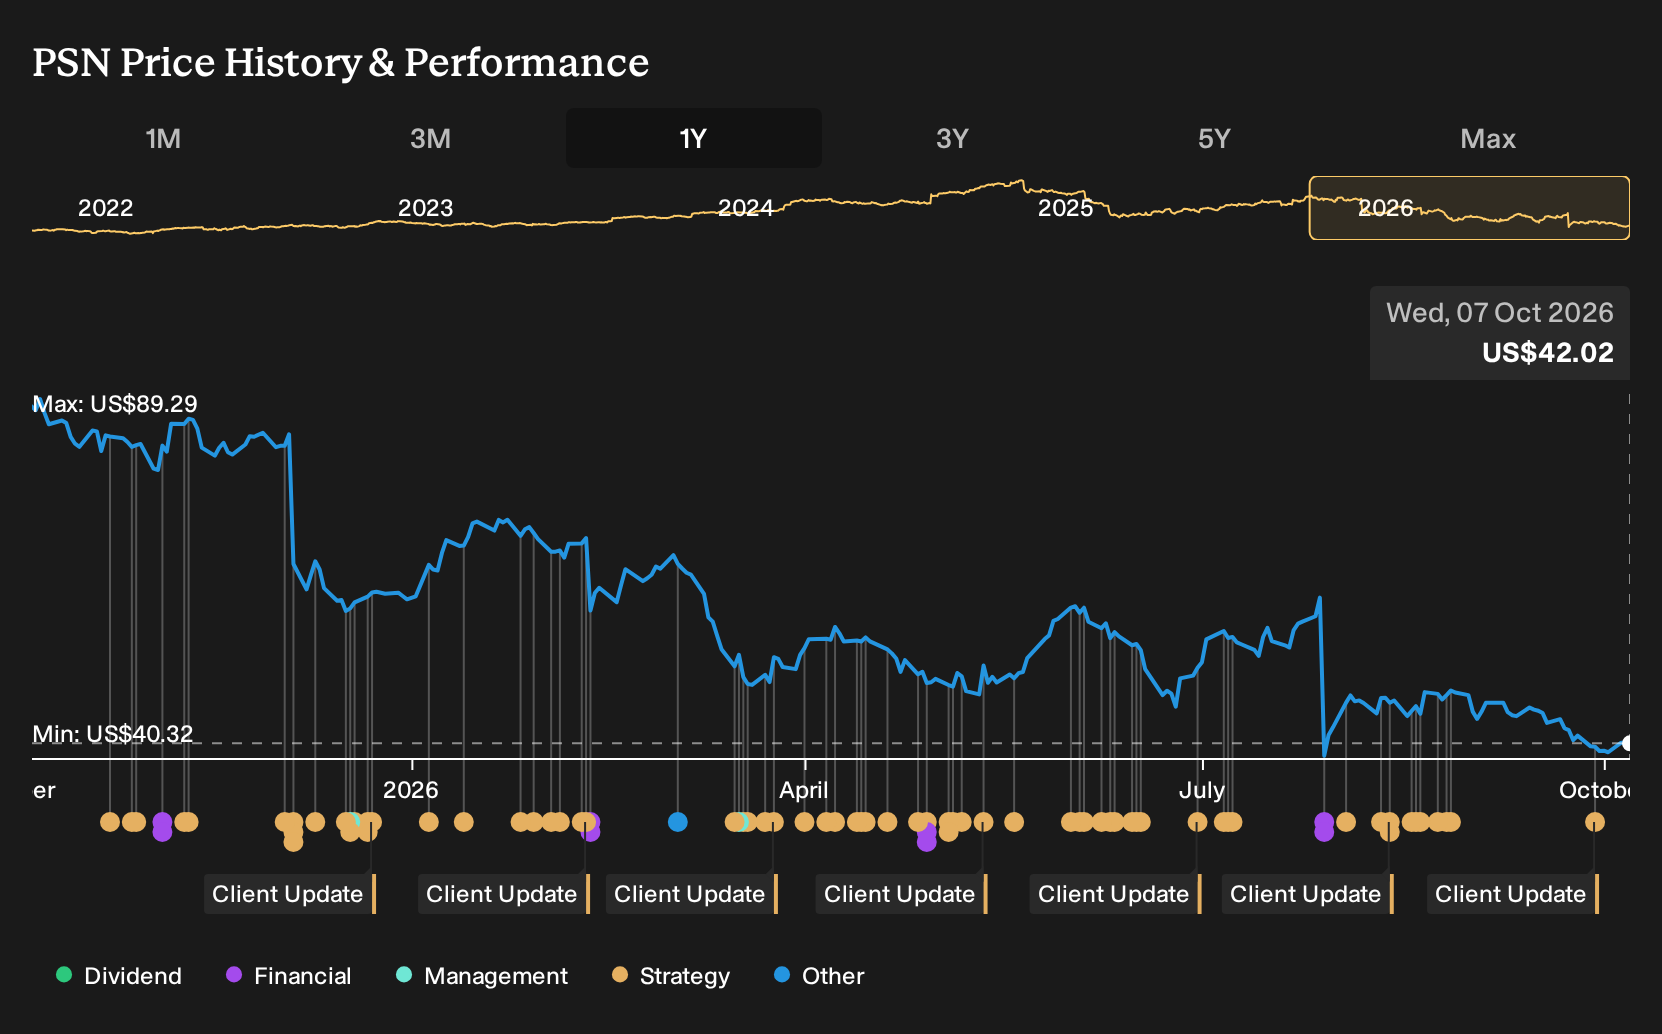
To own Parsons, you need to believe the mix shift toward higher margin federal tech work and critical infrastructure programs can matter more than short term noise in contracts and guidance. The USSPACECOM Owner’s Advisor win supports that story but does not fully change the near term focus on execution after the 2026 revenue guidance cut and Q2 charges.
The key near term catalyst is clean, predictable delivery on existing awards and any signs that legacy joint venture and low return contract issues are fading. The biggest risk is more project specific write downs or U.S. federal timing hiccups that again pressure reported margins, cash conversion and investor confidence.
The upcoming Q3 2026 earnings release on 28 October is the announcement that ties most directly into this. Investors will likely watch how Parsons frames the USSPACECOM agreement inside its broader Federal Solutions pipeline, and whether bookings and backlog data support the idea of a long duration, higher quality project mix.
That call also gives management a platform to address the recent guidance cut, the Q2 2026 nonrecurring charges and any remaining exposure to legacy joint ventures or remote federal contracts. Clear commentary on cash flow, debt and contract risk management would feed into how you weigh the new win against the existing risks and catalysts.
Parsons' outlook suggests revenue of US$7.2b and earnings of US$407.1 million by 2029. This aligns with analysts assuming 4.6% yearly revenue growth and an earnings increase of about US$249.7 million from US$157.4 million today.
Uncover why Parsons' fair value indicates a 42% potential upside to its current price, a discount that could close faster than you might expect.
Exploring Other Perspectives
For Parsons, the most optimistic analysts were already treating AI led products as the real swing factor, with projections for earnings of about US$480.8 million and revenue near US$7.6b by 2029 before this USSPACECOM news. You might see this new long term headquarters role and wonder whether those upbeat views now look conservative. Opinions differ a lot, so explore both the bullish and more cautious narratives before deciding how this contract fits your own thesis.
Explore 3 other Parsons fair value estimates, including one that suggests as much as 169% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Parsons research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Parsons. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Parsons' overall financial health at a glance.
Looking for more ideas beyond Parsons?
Once you have a view on Parsons, it can help to cross check that thesis against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- For investors who prioritise resilient companies with limited downside risk, consider scanning a curated 31 resilient stocks with low risk scores that might better match your comfort level.
- If dependable income matters more to you than short term price moves, review a focused set of 8 dividend fortresses that offer higher yields with detailed fundamentals alongside.
- When you want growth potential with solid foundations, browse a curated pool of 20 high quality undiscovered gems that combine quality metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com