
T&D Holdings (TSE:8795) Screens As Undervalued, Is The Fair Value Case Strong Enough?
T&D Holdings (TSE:8795) has drawn attention after its share price closed at ¥4,735, with the move coming against a backdrop of mixed shorter term returns and strong longer term performance.
Recent trading has cooled slightly, with the share price down over the past week and quarter. Yet T&D Holdings still shows strong momentum when you compare the softer near term share price returns with the much higher multi year total shareholder returns.
Compare T&D Holdings' recent cooling share price with other insurers by scanning a hand picked set of list of solid balance sheet and fundamentals (23 results) that may offer similar resilience with different return profiles.
With T&D Holdings easing back in recent weeks despite strong multi year returns and an indicated discount to some valuation estimates, does the current risk reward still justify new money going in at ¥4,735?
Most Popular Narrative: 10% Undervalued
On Simply Wall St's most followed narrative, T&D Holdings screens as undervalued, with a fair value of ¥5,261 against the latest close at ¥4,735. This puts the focus firmly on how durable its life and health insurance engine really is.
Growing demand for life insurance and annuity products, fueled by an aging population and rising awareness of the need for retirement planning, is driving increased new policy sales and higher policies in force across all three life insurance companies, directly supporting revenue and earnings growth.
Product diversification, through launches like advanced cancer coverage and expansion in health-related or corporate insurance, continues to broaden T&D Holdings' addressable market and customer base, supporting topline revenue growth and more resilient, stable earnings.
See why 1 investors see T&D Holdings as 10% undervalued.
Result: Fair Value of ¥5,261 (UNDERVALUED)
Still, the bullish T&D Holdings story can crack if rising domestic interest rates trigger heavier policy surrenders, or if weaker alternative assets drag on earnings and capital.
Find out about the key risks to this T&D Holdings narrative.
Another View On T&D Holdings Valuation
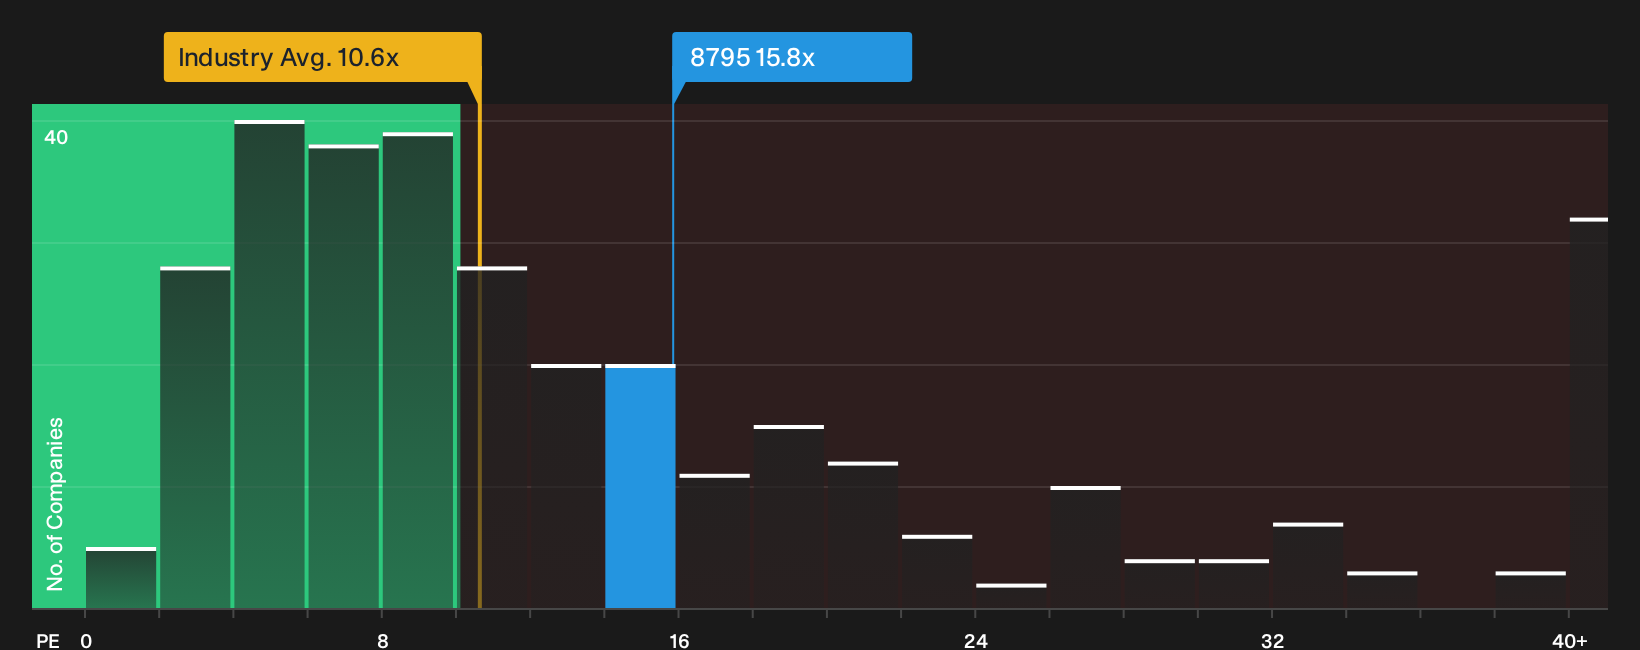
The earlier fair value story for T&D Holdings leaned on analyst targets and earnings expectations. A different lens comes from the current P/E of 15.7x, which sits above the Asian insurance average of 10.6x and also above a fair ratio of 15.5x. That slight premium suggests less margin for error if growth or profitability soften. So is this really a mispricing, or simply a full price for a solid insurer?
For a closer look at how this P/E premium stacks up against peers and where the fair ratio might pull the valuation over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on T&D Holdings leaves you unsure, move quickly to review the full picture for yourself, starting with 4 key rewards and 1 important warning sign
Looking For More Ideas Beyond T&D Holdings?
Do not stop your research at T&D Holdings. Use the Simply Wall St screener to compare new opportunities, pressure test your thesis, and sharpen your next move.
- Target steadier compounding potential by reviewing a curated 22 resilient stocks with low risk scores that can help you avoid fragile balance sheets and surprise setbacks.
- Hunt for value with a focused 14 high quality undervalued stocks that spotlights financially sound businesses trading at what may be discounted prices.
- Prioritise income potential through a yield focused 32 dividend fortresses that highlights companies offering higher payouts with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com