
Advantage Energy (TSX:AAV) Could Be 24% Undervalued Following Wembley Sale And Capital Return Shift
Why Advantage Energy Moved After Its Latest Corporate Moves
Advantage Energy (TSX:AAV) attracted fresh attention after the stock gained 2.56% on 5 October 2026, following its Wembley asset sale, an updated return-of-capital approach, and operational updates tied to recent leadership changes.
Set against a CA$10.51 share price, Advantage Energy’s recent 1-day share price return of 1.94% and 7-day gain of 6.70% mark a short burst of momentum, while the year-to-date share price return is down 10.40% and the 1-year total shareholder return has declined 13.43%. This contrasts with positive total shareholder returns of 11.45% over three years and 59.73% over five years, which indicate a stronger longer-run outcome for patient holders.
Scan how other energy producers are handling asset sales, capital returns, and balance sheets by reviewing the curated list of solid balance sheet and fundamentals (7 results) that share similar themes to Advantage Energy.
The share price just jumped, yet analyst targets and intrinsic value estimates still sit meaningfully higher. For Advantage Energy, is that gap signalling upside potential or a market that remains unconvinced by the recent plan?
Most Popular Narrative: 24% Undervalued
Advantage Energy’s most followed narrative points to a fair value of about CA$13.80 against the recent CA$10.51 share price. This places the latest price move inside a wider debate about earnings power and risk over the next few years.
The international transition from coal to cleaner-burning natural gas, particularly across developing markets, is described as a potential source of sustained demand growth and pricing support, which could influence long-term revenue and free cash flow prospects. Ongoing cost structure improvements following integration of acquired assets, including reductions in operating costs and enhanced well productivity, are cited as factors that may support higher EBITDA margins and net income.
See why 9 investors see Advantage Energy as 24% undervalued.
Result: Fair Value of CA$13.80 (UNDERVALUED)
Still, the bearish side of the Advantage Energy narrative leans on two pressure points: pipeline bottlenecks that cap realized pricing and tighter emissions rules that lift long term costs.
Find out about the key risks to this Advantage Energy narrative.
Another View: What Multiples Say About Advantage Energy
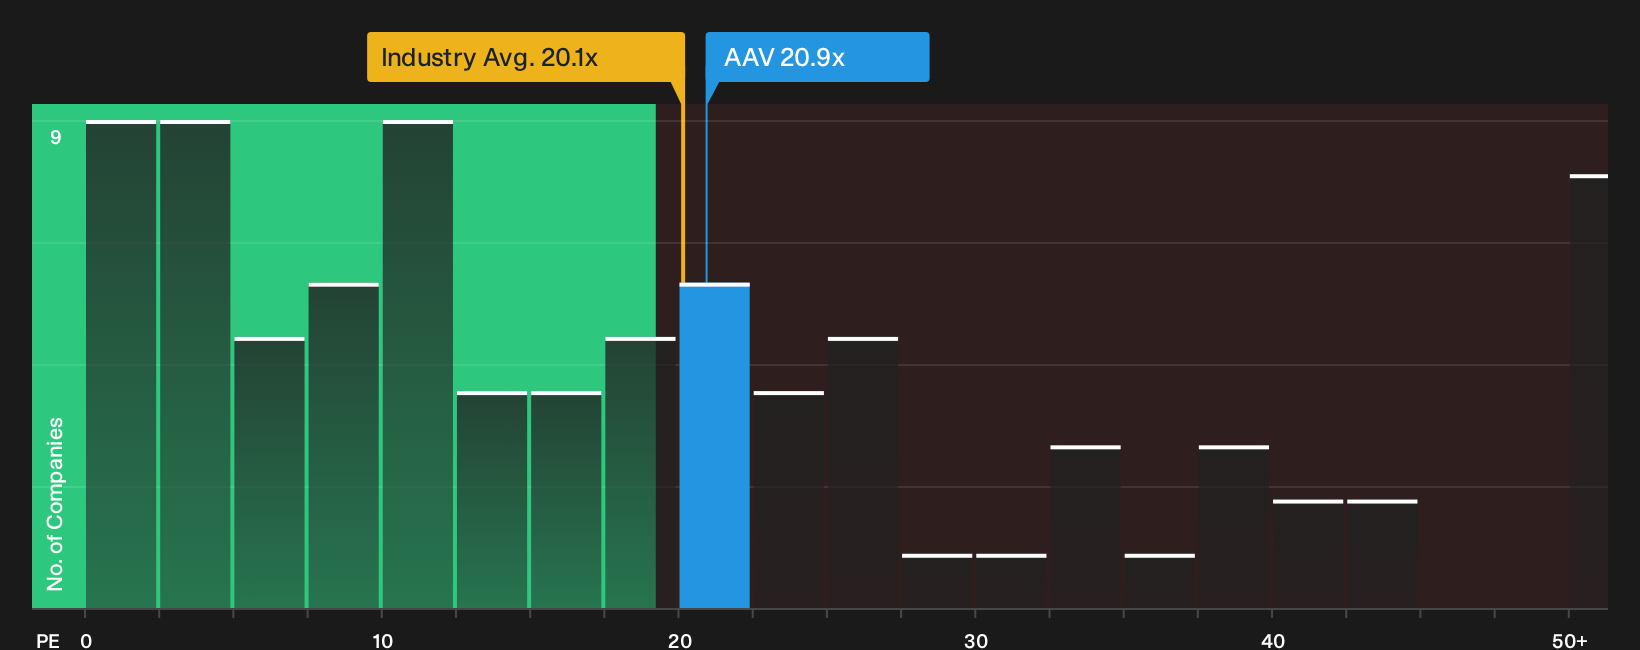
The first story around Advantage Energy leans heavily on discounted cash flows and a fair value near CA$13.80. Yet on simple P/E math of about 20.9x, the stock trades richer than the Canadian oil and gas industry at 20.1x and above a fair ratio of 15.2x. Is the market already baking in a lot of the good news?
That gap between the current P/E and the lower fair ratio hints at valuation risk if sentiment cools or earnings progress stalls. This is the case even though the peer average of 28.4x shows investors have paid up more elsewhere. The question is whether you see that premium as justified resilience or a margin of safety that is thinner than it looks on headline discounts.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Advantage Energy story so far? Act while the details are fresh, review the data from both angles, then weigh the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Advantage Energy?
Step back from a single ticker and build a watchlist that really works for you, by lining up fresh ideas against the Advantage Energy story.
- Target stronger value opportunities by scanning companies with solid fundamentals and pricing support through the 7 high quality undervalued stocks.
- Prioritise resilience first by reviewing the 8 resilient stocks with low risk scores that aim to limit unwanted surprises when conditions change.
- Hunt for future leaders early by checking the 9 high quality undiscovered gems before the wider market starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com