
Will French Agriculture Contract Change CGI's (TSX:GIB.A) Narrative
- CGI Inc. previously announced that France's Ministry of Agriculture, Agri-Food and Food Sovereignty selected the firm to lead a large program to modernize more than 70 business applications, using its CGI MAP solution and support from its Digital Innovation Centre in France.
- The contract underlines CGI's role as a long-term partner for public sector digital modernization, with a focus on accessibility, resilience, sustainability, and compliance with government standards across a broad application portfolio.
- We will now look at how CGI's multi year French agriculture ministry modernization mandate could influence the broader investment narrative.
CGI Investment Narrative Recap
To own CGI, you need to believe that large, complex IT modernization projects in government and regulated industries will keep filling its pipeline and supporting its CA$16.4b revenue base. The French agriculture mandate fits that view, but on its own it does not look like a game changing shift for near term growth or margins.
The more immediate swing factor remains how quickly clients sign bigger digital transformation deals while CGI manages integration of recent acquisitions and keeps regulatory costs in check. The biggest risk still looks tied to contract concentration in large public sector and enterprise accounts and any delay, rebid, or volume softness there.
The French ministry win directly links to CGI's broader push in digital transformation, cloud, automation and application modernization. Using CGI MAP and its Digital Innovation Centre in France aligns with the existing thesis that more work will lean on the firm's own IP and managed services rather than purely time and materials consulting.
That same theme shows up in the quantum computing partnership activity around D Wave Quantum referenced in recent commentary. If CGI can keep landing complex modernization and advanced tech mandates like these and then execute cleanly on delivery, it supports the idea of a deeper backlog and more resilient earnings, while any stumble would quickly highlight execution and competitive risks.
Analysts currently expect CGI's revenues to reach CA$18.0b and earnings to come in at CA$2.1b by 2029. This implies forecast revenue growth of 3.2% per year and an earnings increase of about CA$0.4b from current earnings of CA$1.7b.
Uncover why CGI's fair value indicates a 21% potential upside to its current price that could narrow quickly.
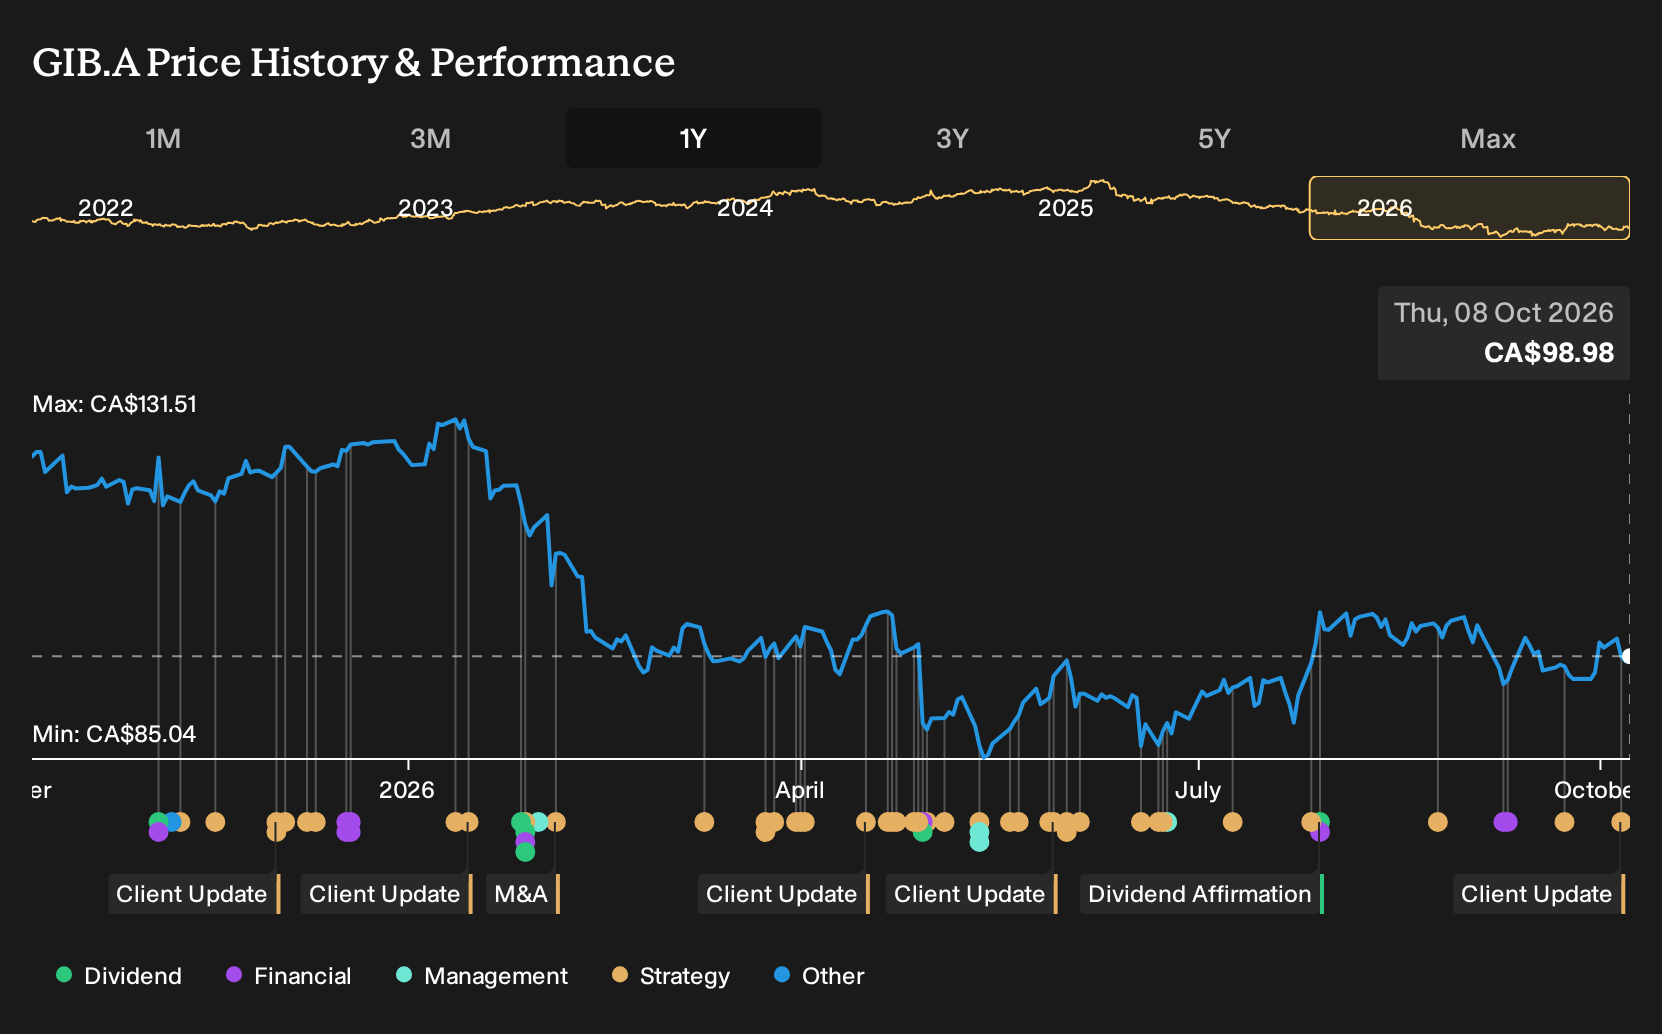
Exploring Other Perspectives
One alternate view around CGI focuses less on contract wins and more on slower conversion of its AI pipeline into booked revenue. The most cautious analysts were pencilling in revenue of about CA$17.2b and earnings of CA$2.1b by 2029 before this French agriculture deal, so their more muted expectations might shift if this program reshapes booking trends.
Explore 4 other CGI fair value estimates, including one that suggests it could be worth just CA$119.85!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CGI research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for CGI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CGI's overall financial health at a glance.
Looking For More Ideas Beyond CGI?
If the CGI story has sharpened your thinking about what you want in a long term holding, use that clarity to scout for other candidates that better match your risk tolerance, income needs, or preference for financial strength.
- If you want potential upside with strict balance sheet discipline, scan our curated list of solid balance sheet and fundamentals (7 results) and focus on companies that pair resilience with sensible fundamentals.
- For investors hunting for mispriced opportunities, weigh CGI against a broader pool by checking out our hand picked 7 high quality undervalued stocks that already clear quality and valuation filters.
- If steady cash payouts matter more to you than headline growth, compare CGI with our collection of income heavyweights through the 3 dividend fortresses and see which yields and payout profiles fit your plan.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com