
3 Japanese Growth Stocks With Earnings Growth Over 24%
AI hardware spending is roaring ahead, with Samsung and TSMC each reporting record sales tied to chip demand. That kind of capital wave often rewards Japanese growth companies that already have clear expansion plans and upbeat guidance. If you want exposure to fast growing Japanese stocks where both analysts and management express confidence in the road ahead, this article walks through three of the strongest candidates on that theme.
The three growth stocks in this article are only a starter pack. The full screen surfaced 26 more Japanese high-conviction companies with equally compelling narratives that are not covered here. If you want to identify and analyze the wider opportunity set right now, head straight to the High Growth High Conviction screener.
Sansan (TSE:4443)
Overview: Sansan provides cloud software that helps companies manage business contacts, invoices, contracts and related data to support sales execution.
Operations: Sansan generates about ¥46,847 million from its Sansan and Bill One segment, with total revenue of ¥53,761 million almost entirely from Japan.
Market Cap: ¥267.5 billion
Sansan plugs directly into the High Growth High Conviction theme, with its core Sansan platform aimed at lifting client sales efficiency and backed by upbeat management guidance. Earnings recently moved from ¥424 million to ¥6,778 million, with net margins at 12.6%. Investor returns now hinge on how one pressure on profitability evolves.
That pressure point is exactly why it helps to read the 3 key rewards and 1 important warning sign before deciding how Sansan fits into your portfolio.

Meiko Electronics (TSE:6787)
Overview: Meiko Electronics designs and manufactures advanced printed circuit boards and related electronics that power automotive systems, communications hardware and industrial equipment worldwide.
Operations: Meiko Electronics generates about ¥260,597 million from its electronics related business, with only a small segment adjustment of ¥127 million.
Market Cap: ¥665.0 billion
Meiko Electronics provides exposure to high specification automotive PCBs that support EV power units and ADAS radar systems, which aligns closely with the High Growth High Conviction theme. Growth expectations and management guidance both point toward the automotive PCB and embedded device line as a key driver, depending on how one unseen pressure around funding that expansion ultimately plays out.
That funding question is exactly where curiosity should kick in, so head to the Meiko Electronics financial health report to see how Meiko Electronics finances expansion without stretching its resources.
Micronics Japan (TSE:6871)
Overview: Micronics Japan develops and sells semiconductor probe cards and related test equipment that check wafers and displays before chips ship at scale.
Operations: Micronics Japan earns about ¥84,868 million from its Probe Card Business and ¥1,391 million from TE Business, serving chipmakers across Asia, Europe and America.
Market Cap: ¥632.7 billion
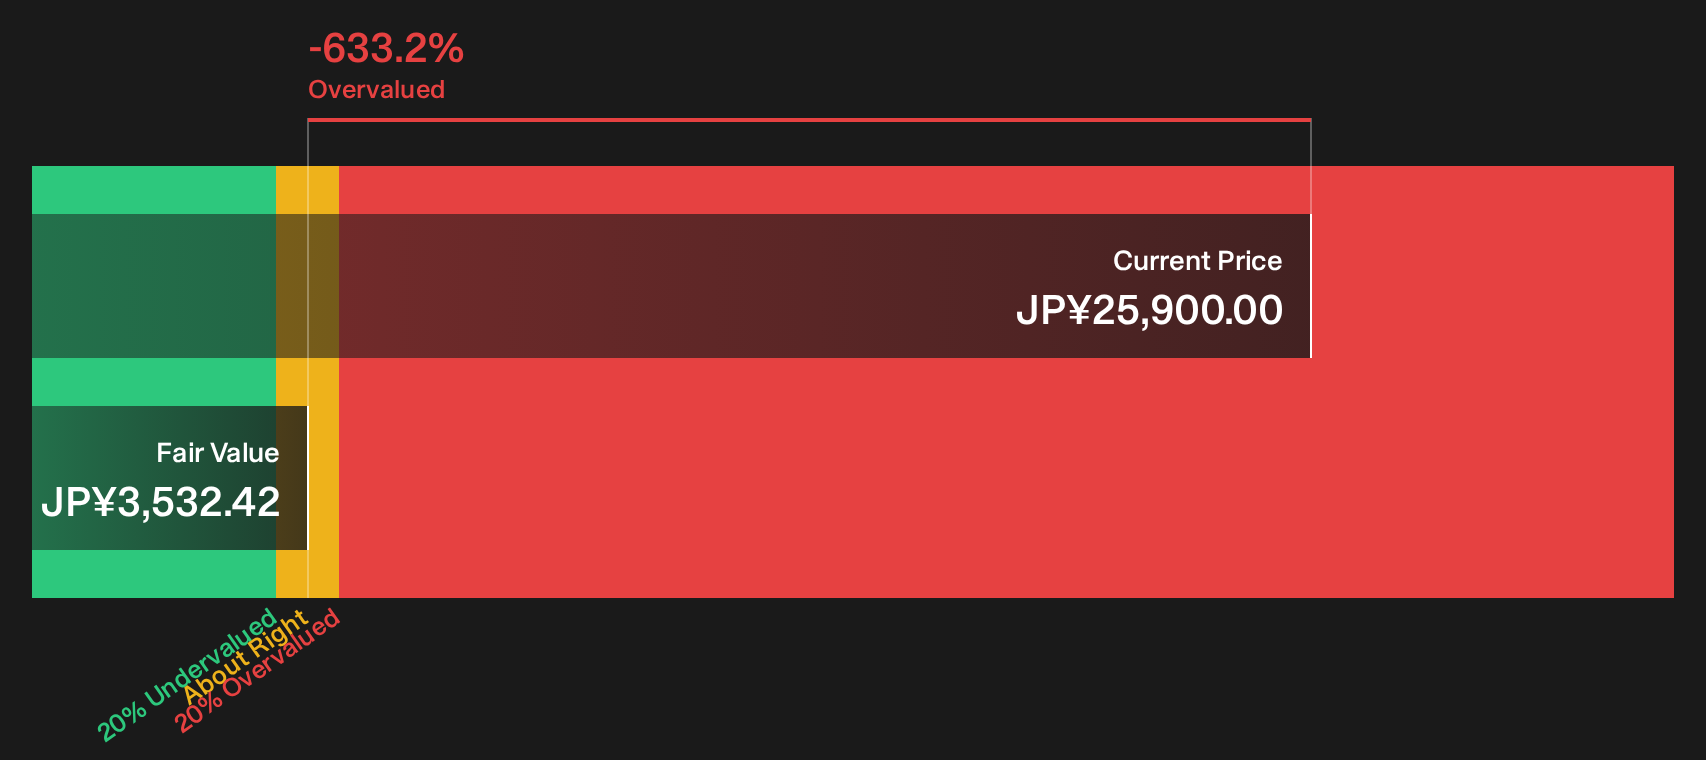
Micronics Japan is closely aligned with the High Growth High Conviction theme, with probe cards and test gear tied to AI and memory chip demand. Its results are supported by 89.4% earnings growth, a 21.7% net margin and 2026 guidance, while future returns depend in part on how one significant swing factor in semiconductor capex affects its order book.
That capex swing factor makes Micronics Japan a true conviction test. Tap into the analysis report for Micronics Japan to see what might be hiding in plain sight.

Seeking Fresh Alternatives Before They Fly
Fresh ideas tend to move first. Breakout stories often gain momentum while they are still under the radar. Consider acting early rather than dropping in late.
- Look for steady income ideas early by scanning a curated pool of potential yield workhorses with the 32 dividend fortresses before they attract wider attention.
- Track accelerating AI demand and follow fast-moving enablers using the 91 AI infrastructure stocks while the story is still developing away from the crowd.
- Monitor the shift toward electrification by checking a hand picked 16 top copper producer stocks that could be positioned to respond to changing demand conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com