
3 Indian Growth Stocks With Up To 79% Earnings Growth
Samsung’s projection of a very large profit jump on the back of AI chip demand shows how quickly capital can flow toward growth when a clear story catches investors’ attention. Indian high growth opportunities with strong conviction from both analysts and management can benefit from that same hunger for future upside. This article highlights three such Indian stocks and explains why they feature in this growth focused shortlist.
The three Indian ideas covered below are only a sample, and the full screen surfaces 36 more companies with equally compelling growth stories and management-backed narratives that are not included here.
To identify and analyze the highest conviction setups that match your own risk profile and time horizon, head straight to the High Growth High Conviction screener.
Rubicon Research (NSEI:RUBICON)
Rubicon Research develops specialty pharmaceutical products using proprietary drug delivery platforms that align closely with the High Growth High Conviction focus on differentiated therapies backed by confident execution from management.
Rubicon Research generates ₹19.4b in revenue from pharmaceutical products and related services, anchored by specialty formulations built on its RubiReten and RubiSRL platforms, and the company carries a market value of about ₹254.2b.
For this screener, Rubicon Research matters because it is not just selling generics. It is using proprietary drug delivery technology to build higher value chronic therapies that can support earnings momentum if execution stays on track.
"Expansion of US manufacturing capacity through the New Jersey facility and preparation of the Pithampur site in India is expected to support a higher own manufacturing share and can support gross margin resilience and operating EBITDA over time."
The key driver of the long term story is whether one quiet assumption about the balance between capital intensity and future margins continues to hold.
If that trade off on capital and margins is what you are really weighing, the full narrative for Rubicon Research lays out how the thesis could accelerate or stall.

Meesho (NSEI:MEESHO)
Meesho runs a social commerce marketplace that anchors this High Growth High Conviction theme. The core platform does the heavy lifting on scale, while a broader services stack aims to turn activity and engagement into something more durable.
"Rising adoption of value focused e commerce across smaller cities and rural areas, where Meesho already has deep reach and a product tailored to mass market users, can support continued growth in annual transacting users and order volumes, which feeds directly into revenue."
What really matters from here is how a single pressure point in Meesho’s business model shapes future profitability and cash generation.
That pressure point sits at the center of Meesho’s story, and the full narrative for Meesho shows how execution could turn today’s scale into accelerating, cash backed growth.

Bajel Projects (NSEI:BAJEL)
Bajel Projects focuses on EPC work for high voltage transmission and distribution infrastructure, which fits cleanly with the High Growth High Conviction theme around power grid build out. It currently earns about ₹27,508 million from power transmission and distribution projects and carries a market value of roughly ₹18.1 billion.
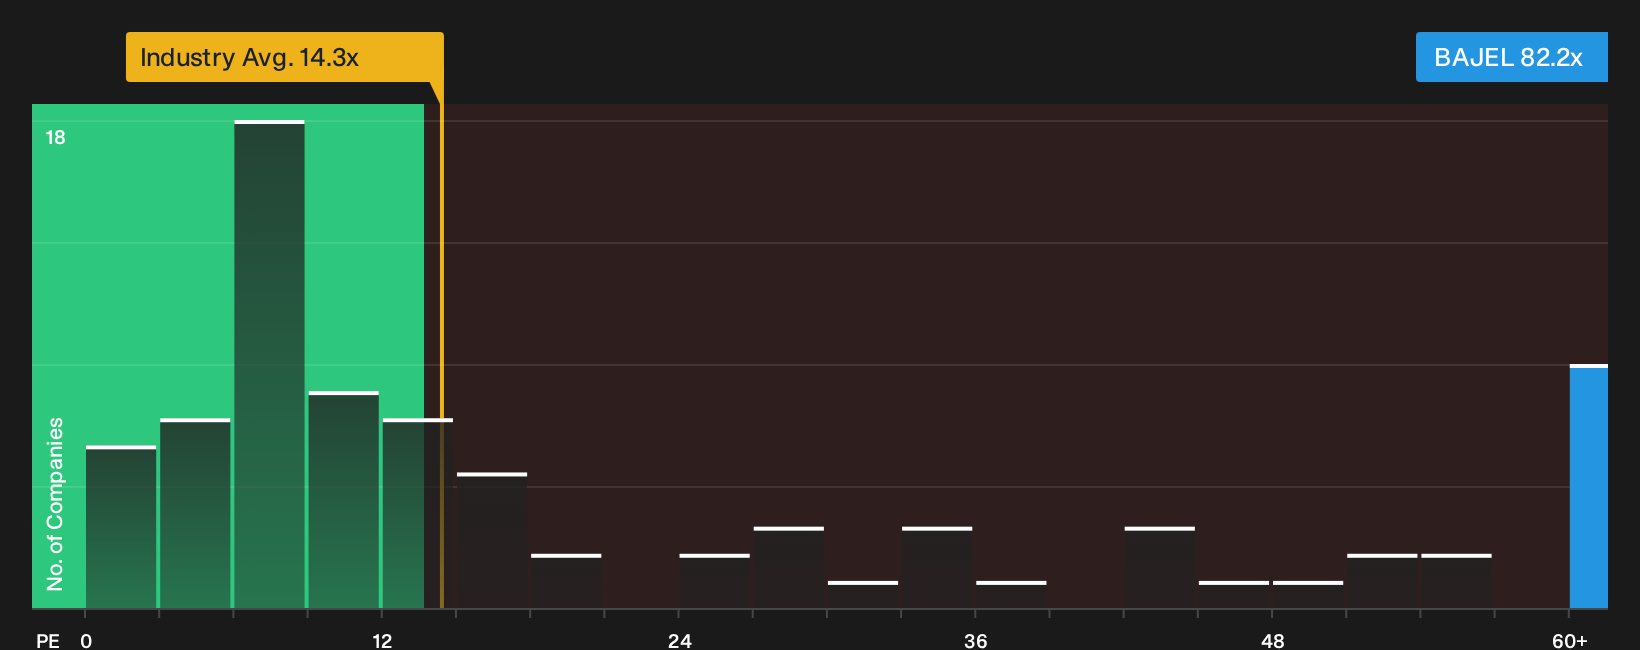
Bajel Projects taps directly into India’s push to upgrade power transmission, with reported earnings growth of 71% last year and a growing book of ultra mega EPC orders in 765 kV lines. The story is firmly about high growth. However, the very high 82.2x P/E and debt heavy funding mean a lot rests on how one pressure point in future cash generation resolves.
With so much hinging on that cash flow twist, scan the 2 key rewards and 1 important warning sign before Bajel Projects’ rich multiple stops tracking its project momentum.
Seeking Fresh Alternatives Beyond Today
Fresh breakouts and early momentum often get caught by data before stories reach the crowd. Scan these ideas while they stay under the radar for now and consider them before they become widely followed.
- Spot income workhorses built for staying power by running through the 227 dividend fortresses before yields reflect increased demand from additional investors.
- Hunt for resilient operators that keep risk in check using the curated 225 resilient stocks with low risk scores list while prices still reflect hesitation, not confidence.
- Track infrastructure players related to tomorrow’s grids through the targeted 43 power grid technology and infrastructure stocks before capital shifts to the next cycle and available entry points change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com