
Plant Upgrades Might Change The Case For Investing In Eagle Materials Stock (EXP)
- Eagle Materials is moving ahead with modernization at its Mountain Cement and Duke Wallboard plants. These projects are aimed at lowering production costs and adding capacity in an industry facing freight and demand pressure.
- The same upgrades that could reshape Eagle Materials cost base are arriving at a time when public infrastructure and nonresidential construction are helping support cement and aggregates volumes.
- This article examines how Eagle Materials investment narrative is influenced by these modernization projects and cost focused execution plans.
Scan how Eagle Materials stacks up against other cost focused construction materials players by checking a curated set of 27 high quality undervalued stocks that may be positioned for the next leg of demand.
Eagle Materials Investment Narrative Recap
For an investor to own Eagle Materials, the core belief is that its exposure to public infrastructure, data centers and other nonresidential work keeps heavy materials volumes reasonably supported while housing stays soft. The modernization at Mountain Cement and Duke Wallboard is the near term swing factor because it targets lower unit costs and extra capacity in markets that remain freight constrained.
The biggest short term catalyst is clear execution on those two upgrades within the US$490m to US$525m fiscal 2027 capex window. The main risk is that residential construction and wallboard demand remain weak while freight and operating costs stay elevated, which would squeeze margins and delay the earnings benefit from the new plants.
The most relevant development for this story is Eagle Materials pushing ahead with the Mountain Cement and Duke Wallboard modernization. Mountain is around 60% complete and Duke is roughly 30% complete, which provides tangible progress against the cost reduction and capacity goals that are central to the current thesis on the business.
If those facilities deliver the targeted 20% to 25% operating cost savings and additional volumes, they may help offset pressure from higher freight costs, a softer Light Materials segment and the drag from heavy capital spending. If execution slips or the savings do not materialize at scale, free cash flow and earnings may stay under pressure longer than the market expects.
Eagle Materials' narrative projects US$2.5b revenue and US$436.8m earnings by 2029, which implies 3.1% yearly revenue growth and an earnings increase of about 8% from US$402.6m today.
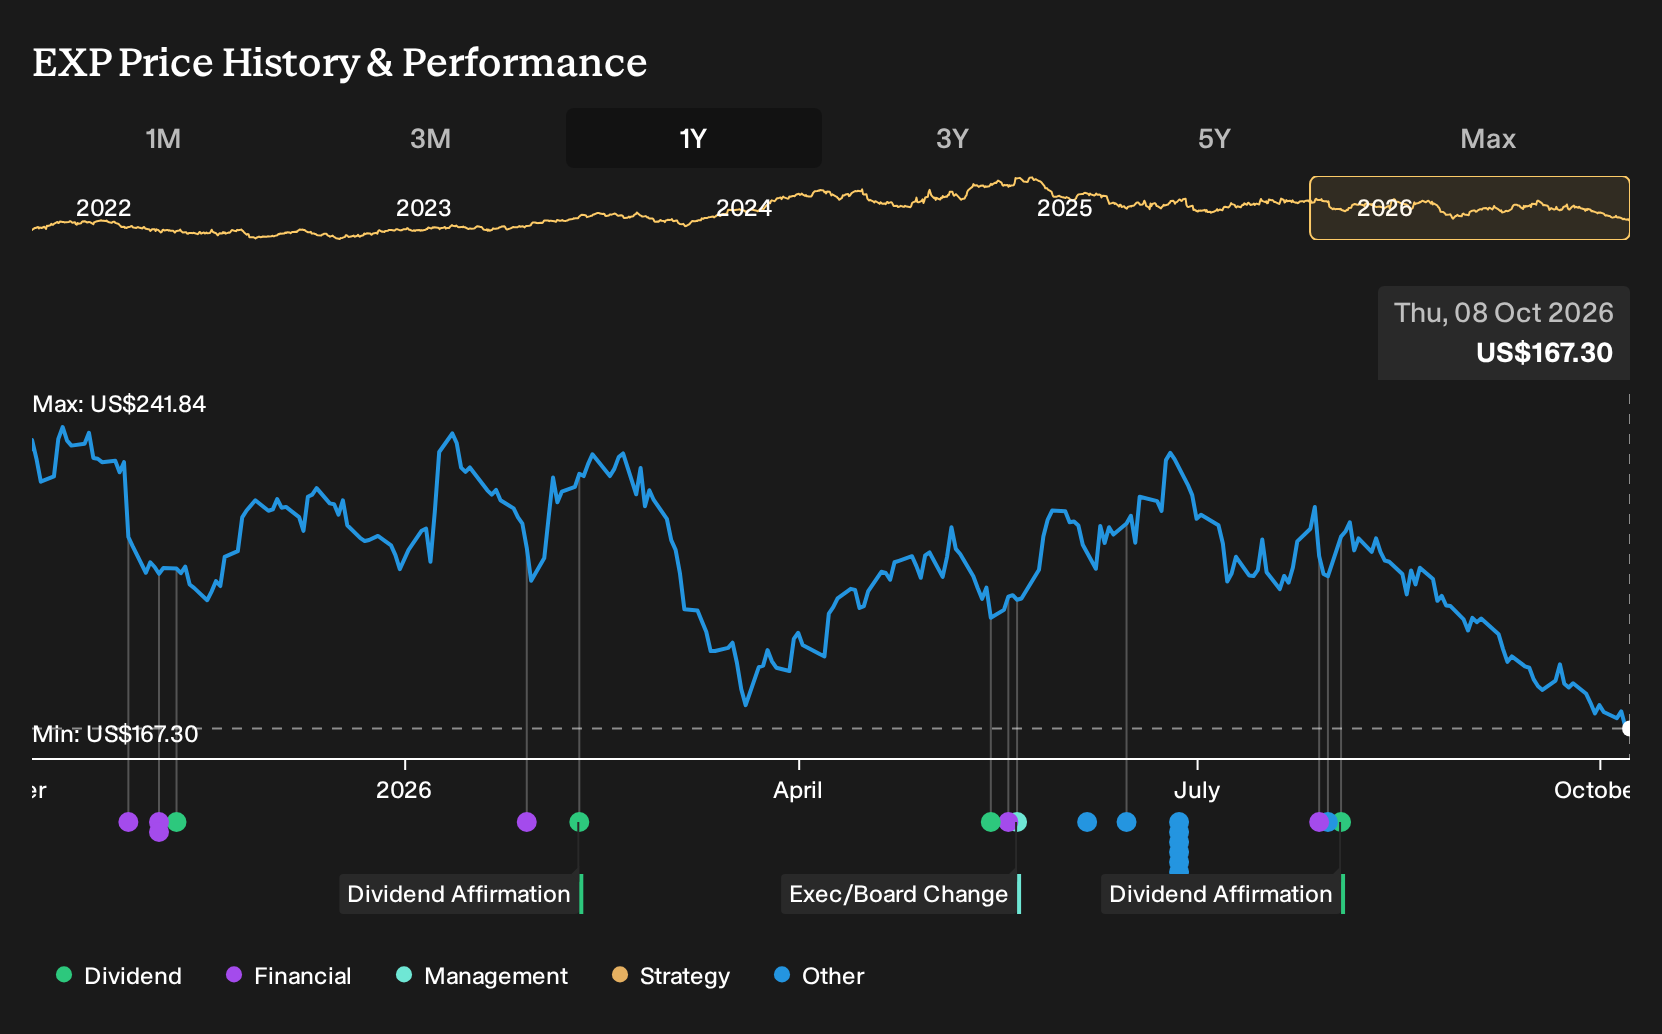
Uncover why Eagle Materials' fair value indicates a 26% potential upside to its current price, which could materialize more quickly than slow moving investors expect.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community range from US$100.36 to about US$306.49, which shows how far opinions on Eagle Materials can spread. Those views do not yet reflect recent plant upgrades or ongoing freight and housing pressures. Use that gap to explore several contrasting angles before forming your own stance.
Explore 3 other Eagle Materials fair value estimates, including one that suggests there could be as much as 40% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Eagle Materials research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eagle Materials. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eagle Materials' overall financial health at a glance.
Looking For More Investment Ideas Beyond Eagle Materials?
After forming a view on Eagle Materials, it can help to compare it with other businesses that share similar financial traits or risk profiles. The Simply Wall St Screener offers several ways to do that without getting lost in thousands of tickers.
- If you want sturdier portfolios during rough patches, start by reviewing 31 resilient stocks with low risk scores, which score well on resilience and volatility measures.
- If balance sheet strength is your priority, scan the list of solid balance sheet and fundamentals (25 results) and focus on companies that pair low leverage with consistent fundamentals.
- If you prefer hunting for lesser known opportunities, sift through the 20 high quality undiscovered gems and see which businesses line up with your own return and risk criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com