
Emerging Asian Gems and Two Promising Small Cap Picks
In recent months, Asian markets have experienced both volatility and opportunity, with key indices reflecting mixed sentiments as investors navigate economic indicators such as inflation pressures and fluctuating bond yields. Amidst this backdrop, small-cap stocks in Asia present intriguing possibilities for investors seeking growth potential, particularly those that can demonstrate resilience and adaptability to current market dynamics.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Eurocharm Holdings | 2.66% | 3.48% | 7.39% | ★★★★★★ |
| Kyosan Electric Manufacturing | 46.17% | 7.20% | 17.51% | ★★★★★★ |
| Yahagi ConstructionLtd | 19.18% | 12.68% | 22.27% | ★★★★★★ |
| SPRIX | 13.12% | 6.95% | -5.71% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Chengtun Mining Group | 99.24% | -6.93% | 33.44% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
SOLiD (KOSDAQ:A050890)
Simply Wall St Value Rating: ★★★★★☆
Overview: SOLiD, Inc. is engaged in the development, manufacturing, and sale of components and equipment for mobile and digital communication networks with a market cap of ₩590.84 billion.
Operations: SOLiD generates revenue primarily from the sale of components and equipment for mobile and digital communication networks. The company's financial performance is highlighted by a net profit margin trend, which reflects its ability to convert sales into actual profit after covering all expenses.
SOLiD, a promising player in the communications sector, has shown impressive earnings growth of 107.5% over the past year, outpacing the industry average of 66.2%. The company is trading at 23.8% below its estimated fair value, suggesting potential upside for investors. With a debt-to-equity ratio reduced from 58.1% to 33.2% over five years and interest payments well-covered by EBIT at a multiple of 30x, SOLiD appears financially robust. Its high-quality earnings and forecasted annual growth rate of 16.54% further underline its strong position within the market landscape.
- Take a closer look at SOLiD's potential here in our health report.
Explore historical data to track SOLiD's performance over time in our Past section.

Kyosan Electric Manufacturing (TSE:6742)
Simply Wall St Value Rating: ★★★★★★
Overview: Kyosan Electric Manufacturing Co., Ltd. specializes in railway signaling and traffic management solutions across Japan, Asia, and other international markets, with a market capitalization of approximately ¥70.98 billion.
Operations: Kyosan Electric Manufacturing generates revenue primarily from railway signaling and traffic management solutions. The company has a market capitalization of approximately ¥70.98 billion.
Kyosan Electric Manufacturing, a smaller player in the electronics industry, has shown promising signs with its recent performance. The company reported a significant turnaround from a net loss of ¥815 million to a net income of ¥398 million for the first quarter ending June 2026. Its debt-to-equity ratio improved notably from 95.9% to 46.2% over five years, indicating better financial health. Despite earnings growth of 23% not outpacing the electronic sector's average, Kyosan is trading at an attractive value, around 87.9% below estimated fair value. Moreover, interest payments are well covered by EBIT at 25 times coverage.

Sunonwealth Electric Machine Industry (TWSE:2421)
Simply Wall St Value Rating: ★★★★★★
Overview: Sunonwealth Electric Machine Industry Co., Ltd. and its subsidiaries focus on the research, manufacturing, and sale of precision motors and cooling fans globally, with a market capitalization of NT$48.05 billion.
Operations: Sunonwealth Electric Machine Industry generates revenue primarily from Greater China, contributing NT$32.90 billion, followed by Europe and North America at NT$656.19 million.
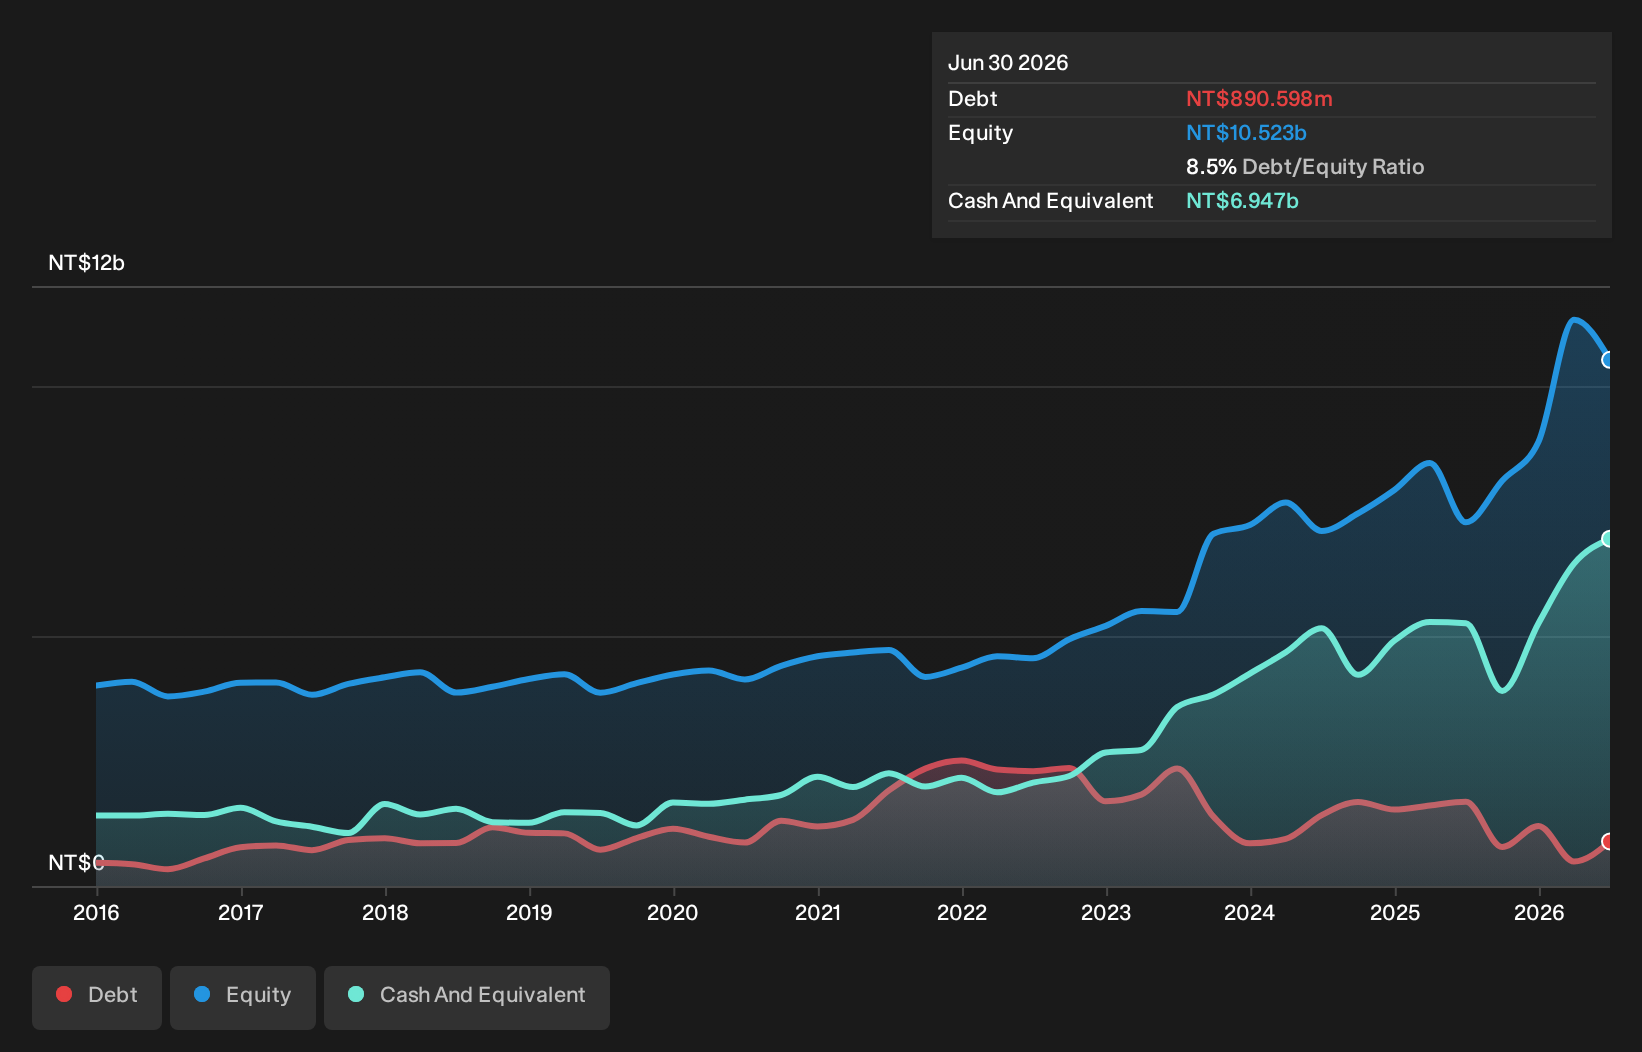
Sunonwealth Electric Machine Industry, a dynamic player in the machinery sector, has seen its earnings surge by 62.8% over the past year, outpacing industry growth. Trading at 40.4% below estimated fair value suggests potential upside for investors. The company’s debt-to-equity ratio improved significantly from 40.5 to 8.5 over five years, reflecting robust financial health and strategic management of liabilities. Recent product innovations like liquid cooling solutions for AI computing highlight Sunon's commitment to addressing cutting-edge technological needs while maintaining high-quality earnings with substantial non-cash components and positive free cash flow trends bolstering its financial standing further.
- Click here and access our complete health analysis report to understand the dynamics of Sunonwealth Electric Machine Industry.
Understand Sunonwealth Electric Machine Industry's track record by examining our Past report.
Summing It All Up
- Gain an insight into the universe of 115 Asian Undiscovered Gems With Strong Fundamentals by clicking here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com