
Progyny (PGNY) Stock Stays Reasonable On Record 2027 Selling Season Pace
Progyny has climbed back into focus after its share price closed at US$27.83, with a sharp mix of gains over the past year and weaker long term returns that leaves a simple question for you as an investor: Is the current market value of this fertility benefits specialist actually supported by the earnings the business is generating today?
- The stock has declined 52.3% over 5 years, which puts a lot of weight on whether the current earnings profile can carry the valuation from here.
- Management recently flagged a record pacing for the 2027 selling season, which can influence how investors think about future profitability and the sustainability of Progyny's earnings power.
- Your read on Progyny is one view; the desks covering it have another. See what analysts think Progyny's shares could be worth.
The stock's next move may depend on whether Progyny's present earnings justify the price investors are now asked to pay.
If you are weighing Progyny's earnings driven story against other opportunities, it can help to compare it with companies filtered through 27 high quality undervalued stocks.
Does Progyny Look Fairly Valued on Earnings?
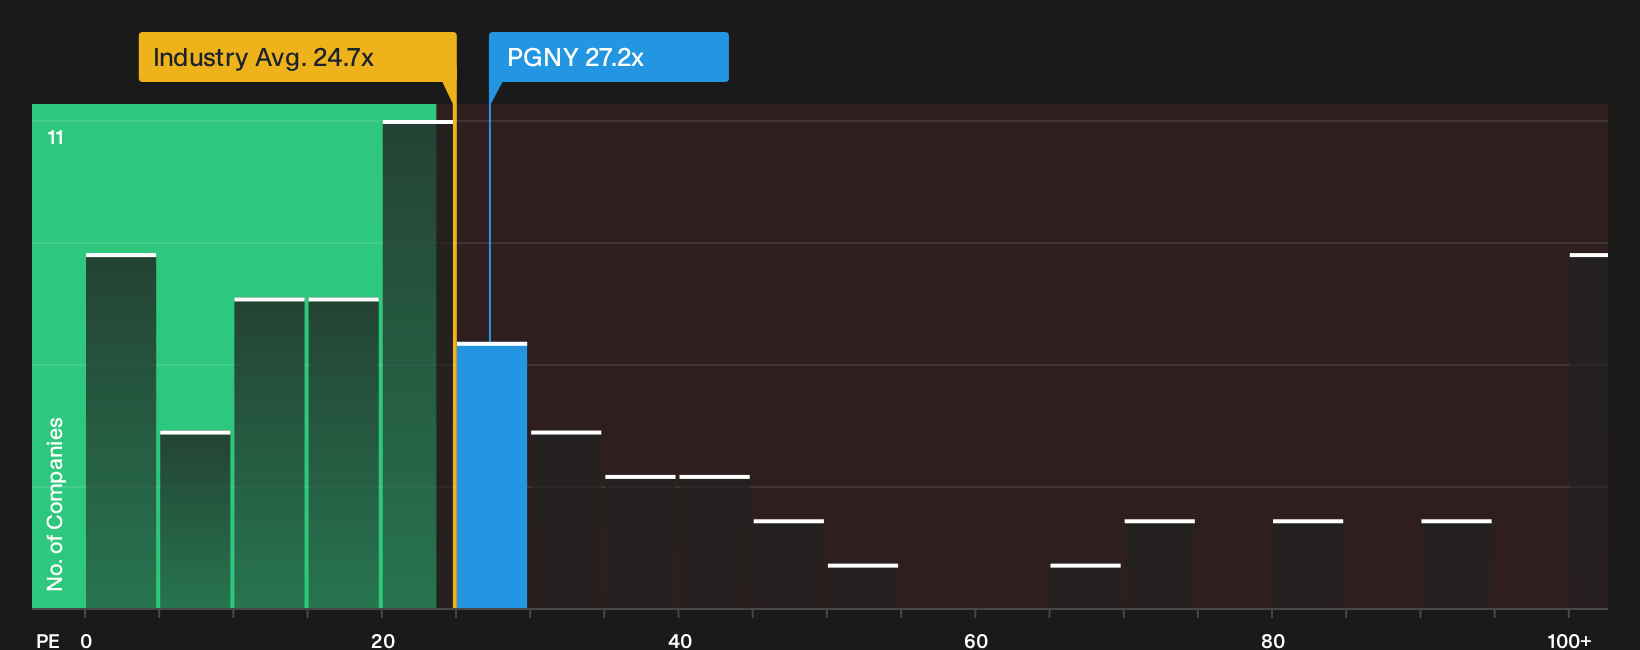
The P/E ratio suits Progyny because earnings are the main driver investors are watching. On this measure, the stock trades on roughly 27.2x, which is slightly above the broader Healthcare sector average of about 24.7x but below the peer group nearer 32.7x. The Fair Ratio benchmark, which blends in factors such as growth potential, profitability and risk, points to a level very close to where the shares change hands today, so the market price broadly matches what this framework implies for the earnings profile.
Because management is talking about a record 2027 selling season, that alignment matters. It suggests the recent enthusiasm already reflects a reasonably full view of Progyny's current earnings power, rather than a clear discount or a stretched premium on this metric. For an investor, the key question is whether those earnings can be sustained and strengthened enough to justify paying a mid 20s P/E instead of looking to cheaper Healthcare alternatives. Explore the numbers behind Progyny's P/E valuation.
The Progyny Narrative: What Would Justify Today's Price?
Narratives pick up where Progyny's valuation puzzle leaves off and spell out which paths for growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or richer than it does today on the Simply Wall St Community page. Each scenario links a fair value estimate to a distinct story about Progyny's potential catalysts and key risks so you can observe over time which version aligns most closely with actual developments.
One of the top community narratives on Progyny: 19% undervalued
"The valuation currently reflects that the recent share price decline following lower EBITDA guidance and modestly softer growth expectations is giving limited credit to Progyny's cash generation..."
Discover why this Narrative puts Progyny at 19% undervalued.
One more angle on Progyny that could change how you see the stock
There is a separate lens on Progyny that does not come from recent results or current multiples. It sits in where professional analysts think the business might be a few years from now. Explore where analysts expect Progyny to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com