
Saputo (TSX:SAP) Rebound Puts Its Efficiency Story And Valuation Back In Focus
Saputo (TSX:SAP) drew fresh interest after a 1.64% gain on 7 October 2026, as traders linked the move to shifting sentiment around dairy pricing, cost discipline, and upcoming operational milestones.
Saputo's latest move sits against a mixed backdrop, with a 7 day share price return of 2.39% following pressure that left the 90 day share price return down 6.04% and the year to date share price return down 5.29%.
Compare Saputo's rebound story with other dairy and food producers by scanning our hand picked list of list of solid balance sheet and fundamentals (7 results) to look for similar sentiment shifts and operational focus.
Saputo now trades with a recent bounce but a weaker 90 day and year to date track record. Does that mix still tilt the risk reward in favour of new buyers once valuation enters the picture?
Most Popular Narrative: 18% Undervalued
Saputo's most followed valuation story points to a fair value of CA$47.63 per share, above the last close of CA$39.02. This puts the current move in the context of a wider debate about how much of the efficiency and brand work is already reflected in the price.
Accelerating operational efficiency initiatives including recent large-scale capital investments in automation, network optimization, and SG&A reduction are driving substantial run-rate cost savings, margin expansion, and improved net earnings, with further upside as the final tranche of targeted efficiencies is achieved in the U.S. by fiscal year-end.
See why 28 investors see Saputo as 18% undervalued.
That fair value estimate of CA$47.63 relies on a discount rate of 6.354% and on analysts expecting Saputo to keep leaning on higher value dairy products and cost control while still managing risks around regulation, plant-based competition, and milk supply volatility.
Result: Fair Value of CA$47.63 (UNDERVALUED)
Still, the bullish Saputo narrative leans on assumptions that could be challenged by faster consumer shifts toward plant based alternatives or by tighter environmental regulation.
Find out about the key risks to this Saputo narrative.
Another View: Saputo Valuation Through The Earnings Lens
The fair value story around Saputo changes once you move from discounted cash flows to what investors are actually paying for each dollar of earnings today.
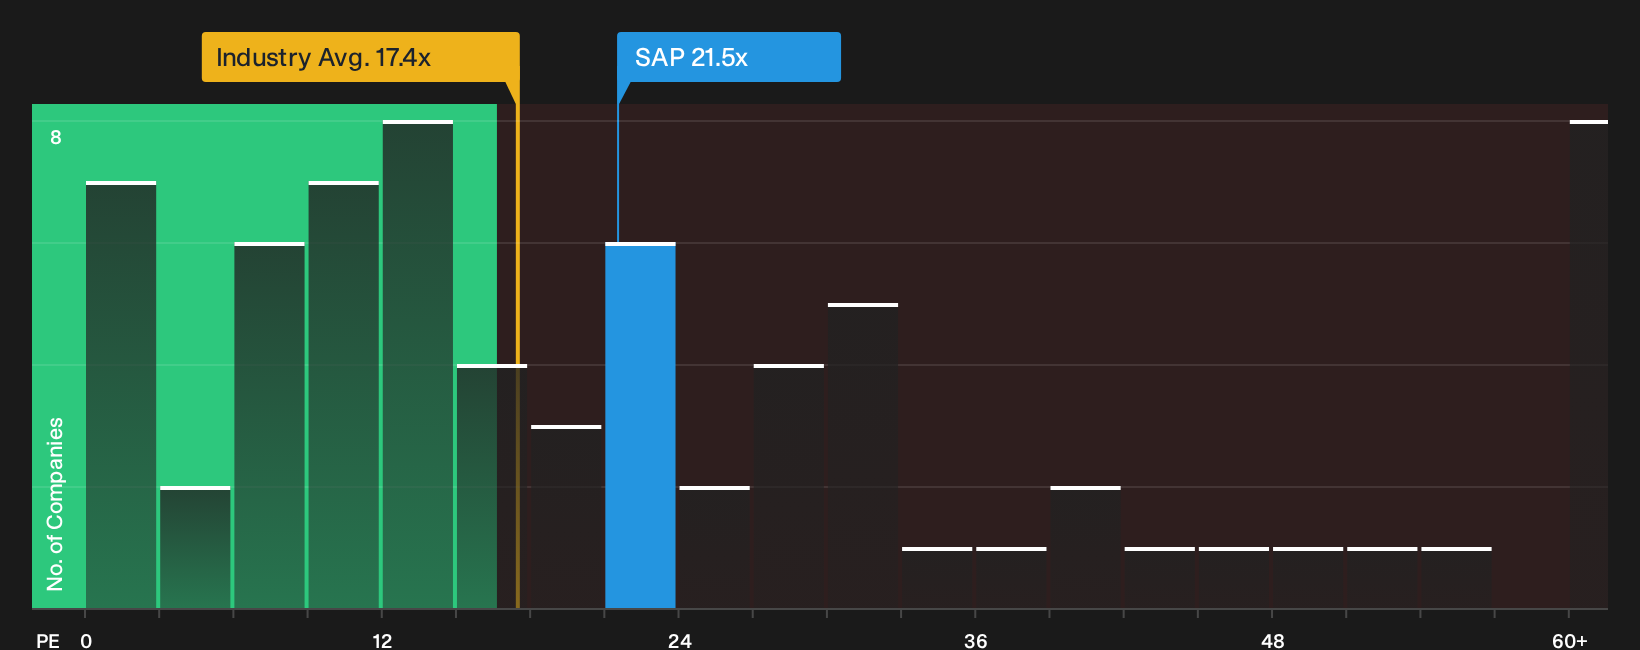
The stock trades on a P/E of 21.5x, which is far lower than the 45.9x peer average but above the 16.8x for the wider North American food group and higher than the 17.5x fair ratio. That mix hints at a company that screens cheaper than close comparables yet still carries some valuation risk if the market drifts back toward the lower fair ratio rather than the richer peer level.
For anyone weighing up Saputo, the open question is whether its execution and earnings quality justify staying closer to peers, or whether gravity pulls the multiple back toward that fair ratio first.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Saputo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of caution and optimism around Saputo feels familiar, treat that as your prompt to move fast and stress test the assumptions yourself using the 3 key rewards.
Looking for more Saputo investment ideas?
Do not stop your work with Saputo alone. Broaden your watchlist using targeted screeners that surface fresh opportunities before they become crowded trades.
- Target resilient compounding potential by scanning a curated list of companies that appear mispriced on quality and value using the 7 high quality undervalued stocks.
- Prioritise capital preservation and steadier price action by reviewing companies that score well on resilience through the 8 resilient stocks with low risk scores.
- Hunt for early stage potential by focusing on under-the-radar companies with strong fundamentals via the 9 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com