
CiDi (SEHK:3881) After Strong H1 Results Still Looks Below Narrative Fair Value
CiDi (SEHK:3881) has drawn fresh attention after recent share price softness, with the stock down 3.5% on the day and weaker over the past month and past 3 months. Investors are reassessing expectations.
That softer tone is not just a one day blip. CiDi’s latest share price of HK$19.6 comes after a 7 day share price return that declined 2.9% and a 90 day share price return that fell 5.9%, which points to fading momentum over the year rather than a sharp reset.
Scan beyond CiDi’s recent pullback and compare it with a curated group of stocks on the 620 high quality undiscovered gems that share strong fundamentals but remain under the radar.
With CiDi sliding over the past quarter yet still carrying an intrinsic discount estimate of 86.3%, the puzzle is simple: Does it make more sense to lean into this weakness now or wait for an even lower entry before the valuation work stacks up?
Most Popular Narrative: 37% Undervalued
CiDi’s current share price of HK$19.6 sits well below the narrative fair value estimate of HK$31.16. This frames the recent pullback very differently to the chart alone and shifts attention toward what is driving that valuation gap.
CiDi’s H1 2026 Results Show Margin Expansion As Revenue Nearly Doubles. CiDi (HK:3881) reported strong top-line growth in the first half of 2026, but the more notable development for investors may be what happened to its margins. For the six months ended June 30, 2026, the autonomous-driving and heavy-duty embodied AI company reported Revenue of RMB 804 million, up 97.0% year on year. Gross profit grew considerably faster, increasing 204% to RMB 212 million, while gross margin expanded from 17.1% to 26.4%. CiDi remains a company whose path to sustainable profitability needs to be watched closely. However, the latest results suggest that increasing commercial scale is beginning to translate into improved economics rather than greater margin pressure.
See why 2 investors see CiDi as 37% undervalued.
Result: Fair Value of HK$31.16 (UNDERVALUED)
Still, the CiDi thesis can crack if margin gains reverse or if heavy reliance on autonomous mining projects fails to translate into sustainably profitable contracts.
Find out about the key risks to this CiDi narrative.
Another View: CiDi’s P/S Tells A Different Story
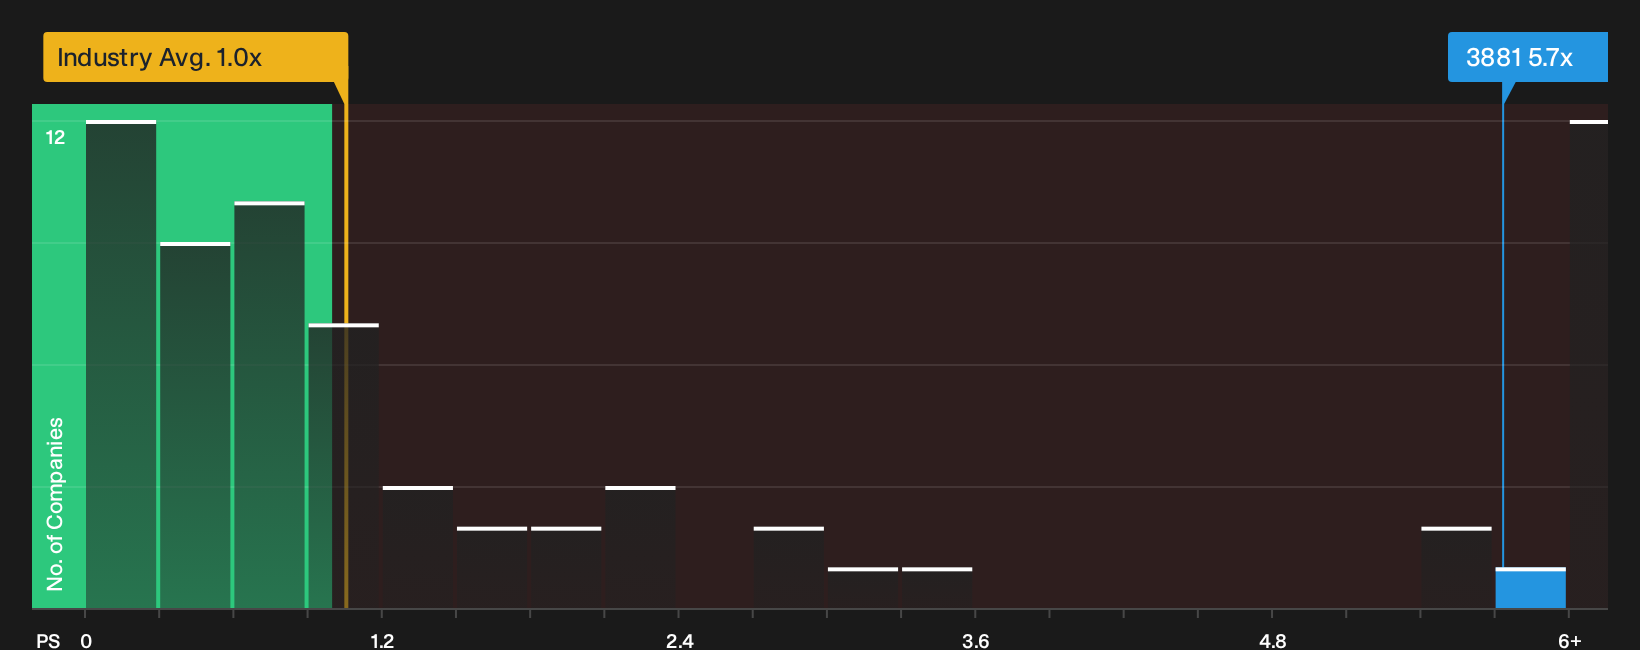
On one side, CiDi looks deeply discounted to a HK$31.16 narrative fair value, with an intrinsic discount estimate of 86.3%. On the other, the current P/S of 5.7x is slightly above the 5.4x fair ratio that the market could move toward.
The same 5.7x multiple also sits well above the Hong Kong Machinery sector average of 1x, which points to a richer tag than the wider group. That mix of potential upside on one model and premium pricing on another leaves a simple question for you: Which signal deserves more weight right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on CiDi can leave you torn, so move quickly and review the underlying data yourself before sentiment shifts again. Then weigh those potential upsides by checking the 2 key rewards.
Looking for more investment ideas beyond CiDi?
You have already done the hard work by scrutinising CiDi. Do not stop here when the same toolkit can help surface other opportunities before the crowd notices.
- Scan for potential opportunities in quality companies trading below their estimated value by reviewing the 180 high quality undervalued stocks.
- Explore income-focused ideas by checking the 227 dividend fortresses with higher yields supported by consistent payout histories.
- Manage portfolio risk by filtering for businesses with sturdier finances using the list of solid balance sheet and fundamentals (206 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com