
3 UK Growth Companies With High Insider Ownership And Up To 36% Earnings Growth
The United Kingdom's stock market has recently experienced fluctuations, with the FTSE 100 index closing lower amid concerns over weak trade data from China and its impact on global demand. In such uncertain times, investors often look for growth companies with strong fundamentals, such as high insider ownership and robust earnings potential, which can provide a measure of confidence in navigating volatile market conditions.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| Quantum Base Holdings (AIM:QUBE) | 31.8% | 111.8% |
| Mortgage Advice Bureau (Holdings) (LSE:MAB1) | 18.4% | 22.4% |
| Metals Exploration (AIM:MTL) | 15.9% | 118.9% |
| Hardide (AIM:HDD) | 20.8% | 76.2% |
| FDM Group (Holdings) (LSE:FDM) | 17.7% | 44.6% |
| Energean (LSE:ENOG) | 19.3% | 32.9% |
| EARNZ (AIM:EARN) | 10.1% | 90.6% |
| Crimson Tide (AIM:TIDE) | 33.5% | 119.1% |
| ActiveOps (AIM:AOM) | 22.2% | 81% |
Let's dive into some prime choices out of the screener.
Filtronic (AIM:FTC)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Filtronic plc designs, develops, manufactures, and sells radio frequency technology globally, with a market cap of £706.02 million.
Operations: The company generates revenue from its Wireless Communications Equipment segment, amounting to £55.53 million.
Insider Ownership: 12%
Earnings Growth Forecast: 36.3% p.a.
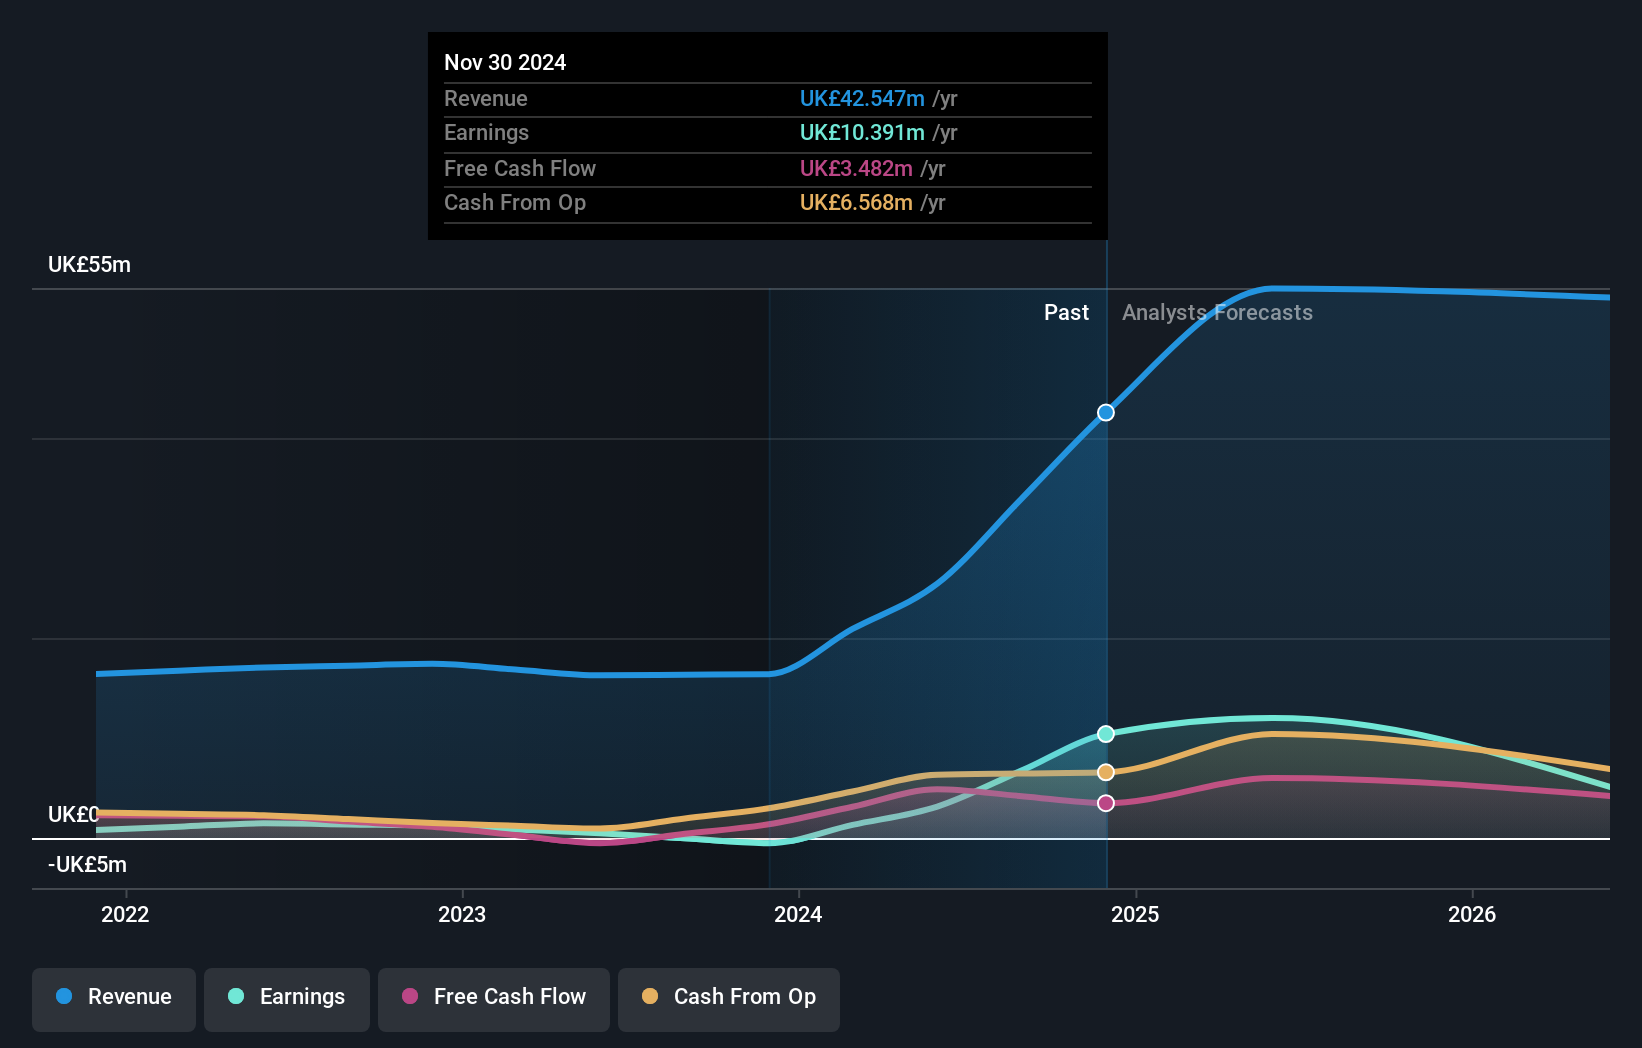
Filtronic has secured substantial contracts, including a $68.1 million order from SpaceX, enhancing revenue visibility for future fiscal years. Despite earnings forecast to grow significantly at 36.3% annually, profit margins have declined from 24.9% to 8.2%. Revenue growth is projected at 15.3%, outpacing the UK market's average of 3.7%, though this remains below high-growth benchmarks. The company's share price has been highly volatile recently, and insider trading activity over the past three months is not reported.
- Dive into the specifics of Filtronic here with our thorough growth forecast report.
- The analysis detailed in our Filtronic valuation report hints at an inflated share price compared to its estimated value.
Energean (LSE:ENOG)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Energean plc is involved in the exploration, production, and development of oil and gas, with a market cap of approximately £1.29 billion.
Operations: The company's revenue primarily stems from its oil and gas exploration and production segment, which generated $1.67 billion.
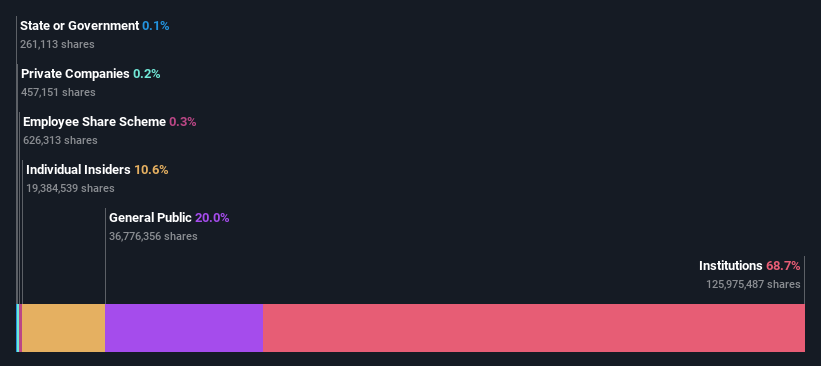
Insider Ownership: 19.3%
Earnings Growth Forecast: 32.9% p.a.
Energean's earnings are forecast to grow 32.88% annually, with profitability expected within three years, surpassing average market growth. Revenue is projected to increase at 6.6% per year, exceeding the UK market's 3.7%. Trading significantly below its estimated fair value enhances its appeal as an investment prospect. Recent insider activity shows more shares bought than sold over the past three months, though not in substantial volumes. Energean is actively seeking acquisitions and reported H1 net income of $159.64 million despite production challenges in Israel and Italy.
- Click to explore a detailed breakdown of our findings in Energean's earnings growth report.
- Insights from our recent valuation report point to the potential undervaluation of Energean shares in the market.
Luceco (LSE:LUCE)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Luceco plc, with a market cap of £304.27 million, designs, manufactures, and delivers residential and commercial electrification products and systems across the United Kingdom, Europe, the Americas, the Middle East, Africa, and the Asia Pacific.
Operations: Luceco's revenue is primarily derived from three segments: LED Lighting (£80.60 million), Portable Power (£72.40 million), and Wiring Accessories (£135.30 million).
Insider Ownership: 23%
Earnings Growth Forecast: 13.3% p.a.
Luceco's earnings are forecast to grow at 13.3% annually, outpacing the UK market average. Despite trading 30% below its estimated fair value, insider activity has shown more selling than buying recently. The company is pursuing acquisitions with leverage at a comfortable 1.5x bank EBITDA, aligning with its capital allocation strategy. Recent half-year results reported sales of £142.6 million and net income of £6.9 million, indicating steady growth amidst leadership changes with Dr Thorsten Müller as CEO.
- Click here and access our complete growth analysis report to understand the dynamics of Luceco.
- Upon reviewing our latest valuation report, Luceco's share price might be too pessimistic.

Make It Happen
- Click this link to deep-dive into the 63 companies within our Fast Growing UK Companies With High Insider Ownership screener.
- Interested In Other Possibilities? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com